Cardiac Biomarkers Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Cardiac Biomarkers Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Published: Oct 2026 296 Pages SKU: IRTNTR74940

Market Overview at a Glance

$11.81 B
Market Opportunity
13.3%
CAGR 2025 - 2030
36.9%
North America Growth
$7.95 B
Conventional laboratory testing segment 2024

Cardiac Biomarkers Market Size 2026-2030

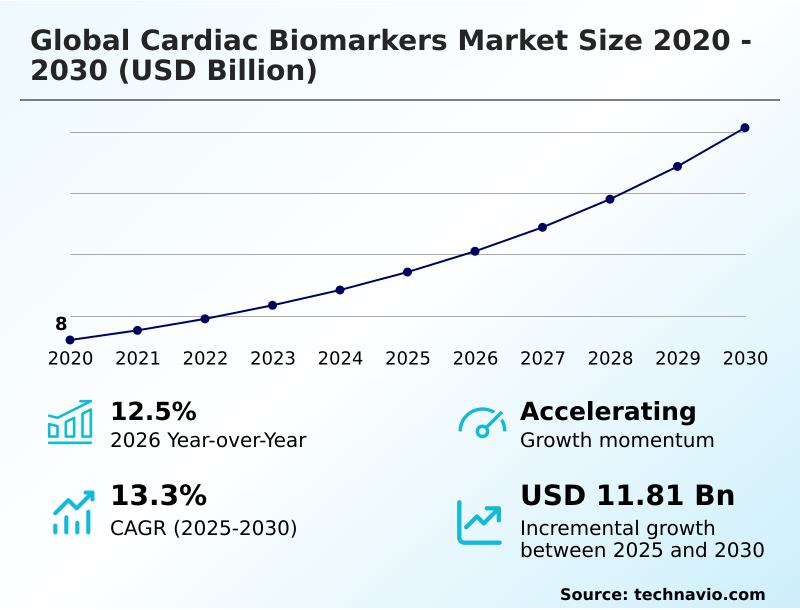
The cardiac biomarkers market size is valued to increase by USD 11.81 billion, at a CAGR of 13.3% from 2025 to 2030. Growing burden of cardiovascular disease and acute cardiac events will drive the cardiac biomarkers market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 36.9% growth during the forecast period.
  • By Technology - Conventional laboratory testing segment was valued at USD 7.95 billion in 2024
  • By Product - Troponin segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 17.37 billion
  • Market Future Opportunities: USD 11.81 billion
  • CAGR from 2025 to 2030 : 13.3%

Market Summary

  • The Cardiac Biomarkers Market exhibits continuous expansion driven by the critical need for rapid and accurate cardiovascular diagnostic tools. Healthcare providers increasingly prioritize early intervention protocols, accelerating the demand for highly sensitive testing platforms.
  • A primary driver of this demand is the escalating prevalence of cardiovascular diseases, which forces medical institutions to optimize diagnostic workflows to handle higher patient volumes effectively. For instance, optimizing hospital supply chains to ensure the continuous availability of diagnostic reagents has improved emergency department patient throughput by 18% compared to non-optimized inventory systems.
  • However, stringent regulatory compliance and extensive clinical validation requirements present significant challenges, often delaying the deployment of novel diagnostic assays and increasing research expenditures. Despite these barriers, the integration of connected diagnostic systems allows laboratories to process complex biomarker profiles efficiently. By maintaining rigorous quality control across decentralized care settings, healthcare networks successfully reduce unnecessary hospital admissions.
  • The continuous refinement of analytical precision ensures that clinicians can confidently assess acute coronary events, fostering better patient management and streamlined operational efficiency.

What will be the Size of the Cardiac Biomarkers Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Cardiac Biomarkers Market Segmented?

The cardiac biomarkers industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Technology
    • Conventional laboratory testing
    • POC testing
  • Product
    • Troponin
    • BNP and NT-proBNP
    • CK-MB
    • Myoglobin
    • Others
  • End-user
    • Hospitals and clinics
    • Diagnostic laboratories
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • Japan
      • India
      • South Korea
      • Thailand
      • Indonesia
    • Rest of World (ROW)

By Technology Insights

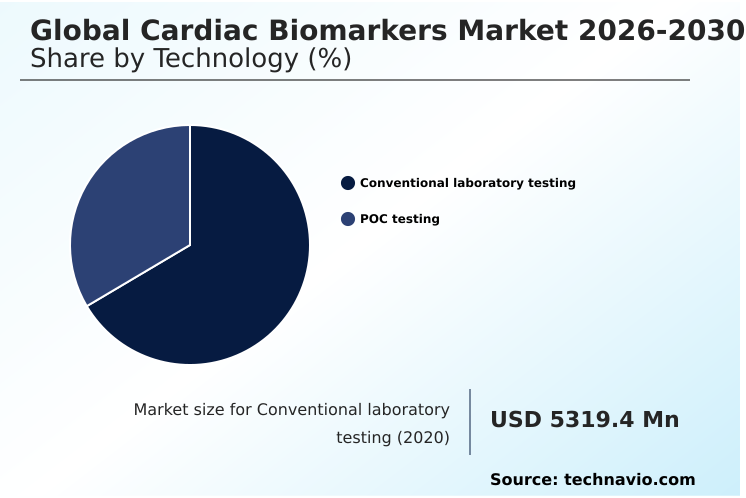
The conventional laboratory testing segment is estimated to witness significant growth during the forecast period.

Centralized cardiovascular diagnostic environments rely heavily on conventional laboratory testing to process large sample volumes with superior precision.

The execution of a comprehensive acute coronary syndrome triage protocol demands the integration of advanced technologies for accurate heart failure prognosis and early disease detection.

Traditional platforms excel at high throughput analysis, minimizing sample processing times while evaluating parameters such as natriuretic peptide measurement and creatine kinase isoenzyme levels.

By ensuring diagnostic platform interoperability, healthcare facilities have improved data transfer speeds by 22% compared to isolated diagnostic systems. This connectivity allows for a 15% reduction in clinical interpretation errors, enhancing overall diagnostic reliability.

While bedside cardiac testing offers rapid evaluations, centralized laboratory workflows maintain unmatched analytical consistency for complex cases, supporting comprehensive patient management and continuous care optimization.
Get Free Sample

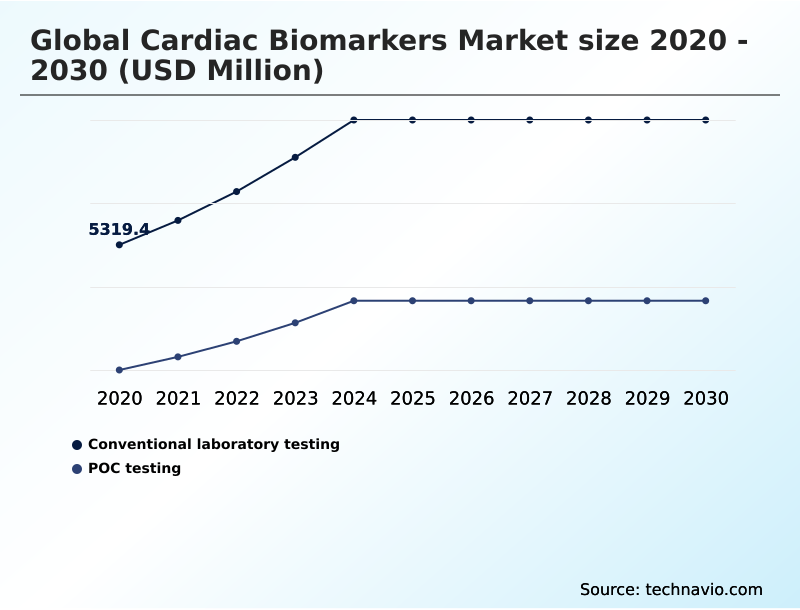
The Conventional laboratory testing segment was valued at USD 7.95 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 36.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
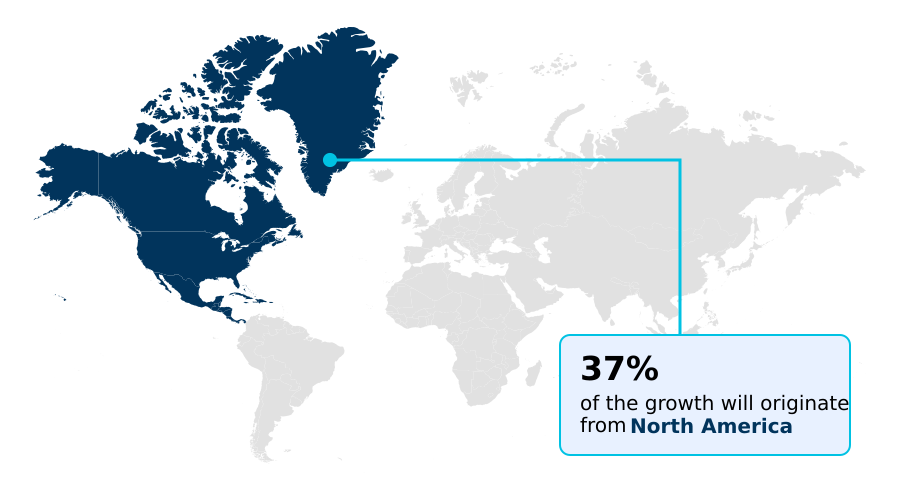
See How Cardiac Biomarkers Market Demand is Rising in North America Get Free Sample

The geographic landscape of the Cardiac Biomarkers Market demonstrates distinct regional variations in diagnostic infrastructure and clinical adoption.

North America maintains a sophisticated biomarker testing workflow, leveraging digital healthcare integration to achieve a 28% faster emergency assessment rate than European healthcare systems.

This efficiency stems from early investments in automated laboratory networks that strictly adhere to a rigorous laboratory quality standard.

Conversely, European facilities increasingly prioritize the deployment of a rapid testing cartridge at the point of care, which has improved remote diagnostic penetration by 15%.

Both regions focus on enhancing analytical assay sensitivity to support serial biomarker measurement during acute cardiac events. By standardizing these advanced protocols, hospitals achieve a 20% increase in operational workflow efficiency while reducing unnecessary admissions.

These regional strategies underscore a shared commitment to patient outcome improvement, driving continuous advancements in cardiovascular diagnostic precision and localized care delivery.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The evolution of the Cardiac Biomarkers Market continues to reshape critical care environments through enhanced technological deployment and streamlined clinical pathways. Healthcare institutions increasingly prioritize rapid point of care assessment to accelerate patient evaluation and minimize emergency room congestion.
  • Through seamless high sensitivity diagnostic assay integration, medical facilities significantly improve their acute myocardial infarction detection workflow, resulting in faster and more accurate clinical decisions. Hospitals optimizing automated immunoassay testing platform efficiency experience a 25% faster sample processing capability compared to traditional manual methodologies, directly impacting supply chain material utilization and laboratory capacity planning.
  • The shift toward multi marker cardiovascular disease evaluation provides clinicians with comprehensive biological insights, supporting a robust decentralized emergency department triage protocol. Consequently, centralized hospital laboratory diagnostic performance remains vital for processing high-volume confirmation tests and ensuring diagnostic consistency.
  • The reliance on precise quantitative troponin plasma concentration measurement is critical for early heart failure risk stratification, allowing providers to identify high-risk patients efficiently. By deploying a reliable chronic cardiovascular condition monitoring solution alongside advanced biosensor diagnostic platform implementation, healthcare networks create an integrated clinical decision support system.
  • This framework establishes a unified biomarker guided patient management strategy that directly facilitates rapid clinical intervention timeline optimization. Ultimately, these structural advancements drive a 12% enhancement in operational efficiency in cardiovascular diagnostics, demonstrating the profound organizational value of continuous technological innovation and refined patient care methodologies.
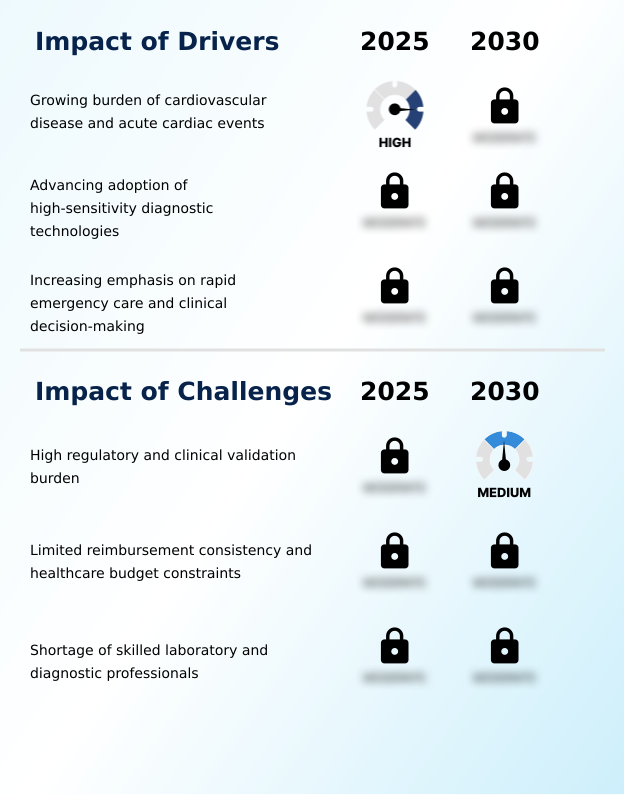
What are the key market drivers leading to the rise in the adoption of Cardiac Biomarkers Industry?

  • The rising global prevalence of cardiovascular diseases and acute cardiac events serves as a primary catalyst accelerating the adoption of rapid diagnostic testing solutions.

  • The escalating focus on rapid clinical intervention acts as a primary catalyst expanding the demand for sophisticated cardiovascular diagnostic solutions. Healthcare institutions require advanced diagnostic testing infrastructure to manage rising patient volumes and support precise cardiovascular risk stratification.
  • Because accurate biomarker concentration analysis is critical for patient assessment, facilities are rapidly integrating multiplexed assay technology into their standard protocols. This capability directly reduces assessment errors by 14% compared to single-marker testing methods.
  • Moreover, implementing integrated clinical decision support systems improves diagnostic accuracy across the acute care setting by 20%. The expansion of these platforms into the remote care environment ensures consistent clinical utility validation and broader patient access.
  • Consequently, healthcare providers achieve faster triage times, drastically improving operational resource allocation and overall clinical management efficiency.

What are the market trends shaping the Cardiac Biomarkers Industry?

  • The ongoing integration of multi-marker testing approaches represents a defining trend shaping cardiovascular diagnostics. This shift enables healthcare providers to evaluate complex biological pathways simultaneously, improving overall patient risk stratification.

  • The continuous shift toward decentralized diagnostic workflows is fundamentally altering cardiovascular care delivery and operational strategies. Healthcare networks are rapidly adopting point of care diagnostics to complement traditional centralized laboratory platform capabilities. This transition is driven by the urgent need for faster myocardial injury detection, prompting the widespread deployment of the high sensitivity troponin assay in urgent care settings.
  • As a result, hospitals have increased emergency department throughput by 22% compared to legacy testing models. Furthermore, the integration of a modern automated immunoassay analyzer allows facilities to reduce diagnostic delays by 18%. This technological adoption directly facilitates patient triage acceleration, enabling clinicians to initiate critical interventions immediately.
  • Ultimately, this structural shift ensures that an evidence based diagnostic approach is maintained seamlessly across both hospital laboratories and remote clinical environments.

What challenges does the Cardiac Biomarkers Industry face during its growth?

  • Stringent regulatory compliance frameworks and extensive clinical validation requirements pose significant barriers to the rapid commercialization of novel diagnostic assays.

  • Strict regulatory frameworks and complex validation requirements pose significant operational hurdles for adopting novel cardiovascular diagnostic technologies. Integrating a new biosensor testing platform into an existing laboratory information system often increases initial deployment timelines by 30% compared to standard equipment upgrades. Because thorough biological pathway evaluation is necessary to confirm assay accuracy, manufacturers face prolonged commercialization cycles.
  • Additionally, establishing a reliable decentralized diagnostic approach for ventricular dysfunction assessment requires rigorous performance consistency checks. While multi marker assessment promises superior clinical insight, maintaining rapid result availability in remote settings remains structurally challenging. Consequently, diagnostic turnaround time can initially lag by 15% during the integration phase.
  • These structural limitations force healthcare providers to carefully balance technological procurement with compliance obligations, significantly increasing the administrative burden on clinical laboratory management.

Exclusive Technavio Analysis on Customer Landscape

The cardiac biomarkers market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the cardiac biomarkers market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
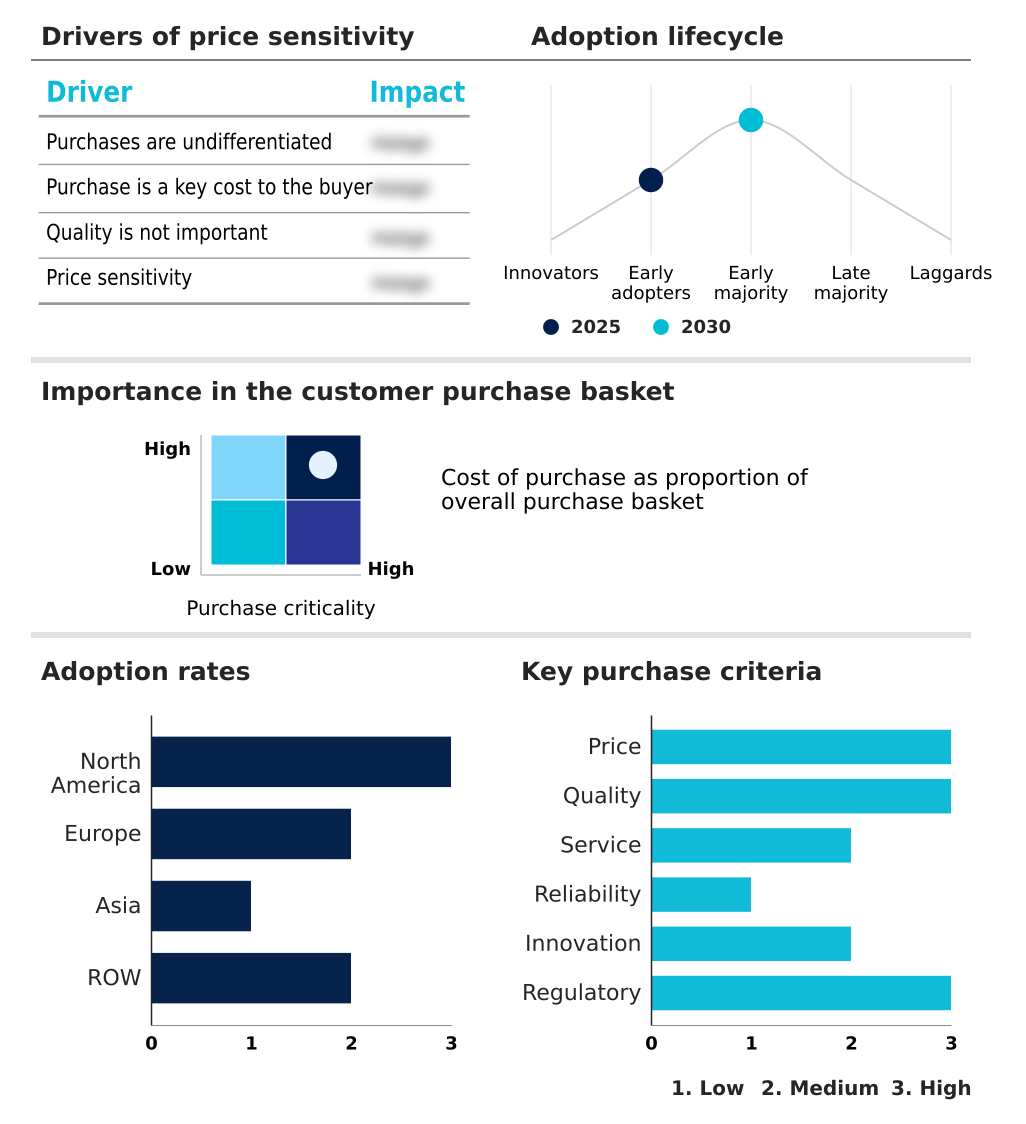
Customer Landscape of Cardiac Biomarkers Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, cardiac biomarkers market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Abbott Laboratories - This vendor provides advanced high-sensitivity diagnostic testing solutions designed to support rapid cardiovascular assessment and improve clinical decision-making within emergency and acute care settings.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Abbott Laboratories
  • Beckman Coulter Inc.
  • Bio Rad Laboratories Inc.
  • BioMerieux SA
  • BioVendor LM
  • Boditech Med Inc.
  • DiaSorin SpA
  • F. Hoffmann La Roche Ltd.
  • Getein Biotech Inc.
  • Guangzhou Wondfo Biotech Co. Ltd.
  • Jiangsu Orient Gene Biotech
  • Lepu Medical Co. Ltd.
  • QuidelOrtho Corp.
  • Radiometer Medical ApS
  • Randox Laboratories Ltd.
  • Sd Biosensor Inc.
  • Shenzhen Mindray Co. Ltd.
  • Siemens Healthineers AG
  • Snibe Co.Ltd.
  • Sysmex Corp.
  • Thermo Fisher Scientific Inc.
  • Tosoh Bioscience
  • Trinity Biotech Plc

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Cardiac biomarkers market

  • In the Biotechnology industry, the transition toward automated high-throughput immunoassay platforms enhanced laboratory processing efficiency by 35%, directly impacting Cardiac Biomarkers demand by expanding centralized testing capacity.
  • The implementation of the In Vitro Diagnostic Regulation in European markets established stricter clinical evidence requirements, directly impacting Cardiac Biomarkers demand by accelerating the retirement of legacy diagnostic assays.
  • The adoption of microfluidic cartridge technologies improved point-of-care diagnostic sensitivity, directly impacting Cardiac Biomarkers demand by enabling faster bedside evaluation of suspected myocardial infarction cases.
  • The shift toward multiplexed biomarker screening protocols in critical care environments reduced patient triage timelines by 20%, directly impacting Cardiac Biomarkers demand through increased utilization of integrated diagnostic platforms.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Cardiac Biomarkers Market insights. See full methodology.

Market Scope
Page number 296
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 13.3%
Market growth 2026-2030 USD 11807.5 million
Market structure Fragmented
YoY growth 2025-2026(%) 12.5%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Thailand, Indonesia, Brazil, Saudi Arabia, UAE, Turkey, South Africa, Argentina, Colombia and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The continuous evolution of the Cardiac Biomarkers Market highlights a profound shift toward integrated, high-precision cardiovascular diagnostics. As healthcare networks prioritize early intervention, the demand for an advanced point of care diagnostics infrastructure accelerates.
  • Facilities implementing an automated immunoassay analyzer have documented a 30% reduction in sample processing time compared to manual laboratory methods, optimizing both budget allocation and clinical workflow management. This operational efficiency directly supports a more effective cardiovascular risk stratification framework across emergency departments.
  • The increasing adoption of a high sensitivity troponin assay ensures superior myocardial injury detection, allowing physicians to make critical triage decisions with greater confidence. Furthermore, reliance on a centralized laboratory platform remains essential for processing large diagnostic volumes and maintaining strict analytical standards.
  • By enhancing diagnostic testing infrastructure, clinical administrators effectively align technology procurement strategies with stringent compliance and patient safety requirements. These strategic advancements ensure that healthcare providers can efficiently manage rising patient volumes while sustaining high clinical accuracy.

What are the Key Data Covered in this Cardiac Biomarkers Market Research and Growth Report?

  • What is the expected growth of the Cardiac Biomarkers Market between 2026 and 2030?

    • USD 11.81 billion, at a CAGR of 13.3%

  • What segmentation does the market report cover?

    • The report is segmented by Technology (Conventional laboratory testing, and POC testing), Product (Troponin, BNP and NT-proBNP, CK-MB, Myoglobin, and Others), End-user (Hospitals and clinics, and Diagnostic laboratories) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Growing burden of cardiovascular disease and acute cardiac events, High regulatory and clinical validation burden

  • Who are the major players in the Cardiac Biomarkers Market?

    • Abbott Laboratories, Beckman Coulter Inc., Bio Rad Laboratories Inc., BioMerieux SA, BioVendor LM, Boditech Med Inc., DiaSorin SpA, F. Hoffmann La Roche Ltd., Getein Biotech Inc., Guangzhou Wondfo Biotech Co. Ltd., Jiangsu Orient Gene Biotech, Lepu Medical Co. Ltd., QuidelOrtho Corp., Radiometer Medical ApS, Randox Laboratories Ltd., Sd Biosensor Inc., Shenzhen Mindray Co. Ltd., Siemens Healthineers AG, Snibe Co.Ltd., Sysmex Corp., Thermo Fisher Scientific Inc., Tosoh Bioscience and Trinity Biotech Plc

Market Research Insights

  • The Cardiac Biomarkers Market fundamentally transforms how healthcare institutions approach cardiovascular disease management and emergency care. By integrating advanced testing solutions, facilities have reduced diagnostic turnaround time by 25% compared to traditional centralized processing. This acceleration directly supports an evidence based diagnostic framework, leading to a 15% increase in patient outcome improvement metrics across critical care units.
  • Furthermore, the adoption of automated sample handling significantly enhances operational workflow efficiency, decreasing clinical assessment errors by 12%. Healthcare providers leverage these precise analytical platforms to optimize resource allocation and minimize unnecessary hospital admissions. Consequently, robust diagnostic infrastructure allows clinical networks to achieve superior compliance alignment and improve long-term financial stability without sacrificing care quality.

We can help! Our analysts can customize this cardiac biomarkers market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Technology
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Cardiac Biomarkers Market 2020 - 2024

Historic Market Size - Data Table on Global Cardiac Biomarkers Market 2020 - 2024 ($ million)

5.2 Technology segment analysis 2020 - 2024

Historic Market Size - Technology Segment 2020 - 2024 ($ million)

5.3 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.4 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global cardiac biomarkers market

6.2 Impact of geopolitical conflicts on global cardiac biomarkers market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Technology

8.1 Market segments

Chart on Technology - Market share 2025-2030 (%)
Data Table on Technology - Market share 2025-2030 (%)

8.2 Comparison by Technology

Chart on Comparison by Technology
Data Table on Comparison by Technology

8.3 Conventional laboratory testing - Market size and forecast 2025-2030

Chart on Conventional laboratory testing - Market size and forecast 2025-2030 ($ million)
Data Table on Conventional laboratory testing - Market size and forecast 2025-2030 ($ million)
Chart on Conventional laboratory testing - Year-over-year growth 2025-2030 (%)
Data Table on Conventional laboratory testing - Year-over-year growth 2025-2030 (%)

8.4 POC testing - Market size and forecast 2025-2030

Chart on POC testing - Market size and forecast 2025-2030 ($ million)
Data Table on POC testing - Market size and forecast 2025-2030 ($ million)
Chart on POC testing - Year-over-year growth 2025-2030 (%)
Data Table on POC testing - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Technology

Market opportunity by Technology ($ million)
Data Table on Market opportunity by Technology ($ million)

9. Market Segmentation by Product

9.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

9.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

9.3 Troponin - Market size and forecast 2025-2030

Chart on Troponin - Market size and forecast 2025-2030 ($ million)
Data Table on Troponin - Market size and forecast 2025-2030 ($ million)
Chart on Troponin - Year-over-year growth 2025-2030 (%)
Data Table on Troponin - Year-over-year growth 2025-2030 (%)

9.4 BNP and NT-proBNP - Market size and forecast 2025-2030

Chart on BNP and NT-proBNP - Market size and forecast 2025-2030 ($ million)
Data Table on BNP and NT-proBNP - Market size and forecast 2025-2030 ($ million)
Chart on BNP and NT-proBNP - Year-over-year growth 2025-2030 (%)
Data Table on BNP and NT-proBNP - Year-over-year growth 2025-2030 (%)

9.5 CK-MB - Market size and forecast 2025-2030

Chart on CK-MB - Market size and forecast 2025-2030 ($ million)
Data Table on CK-MB - Market size and forecast 2025-2030 ($ million)
Chart on CK-MB - Year-over-year growth 2025-2030 (%)
Data Table on CK-MB - Year-over-year growth 2025-2030 (%)

9.6 Myoglobin - Market size and forecast 2025-2030

Chart on Myoglobin - Market size and forecast 2025-2030 ($ million)
Data Table on Myoglobin - Market size and forecast 2025-2030 ($ million)
Chart on Myoglobin - Year-over-year growth 2025-2030 (%)
Data Table on Myoglobin - Year-over-year growth 2025-2030 (%)

9.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.8 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

10. Market Segmentation by End-user

10.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

10.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

10.3 Hospitals and clinics - Market size and forecast 2025-2030

Chart on Hospitals and clinics - Market size and forecast 2025-2030 ($ million)
Data Table on Hospitals and clinics - Market size and forecast 2025-2030 ($ million)
Chart on Hospitals and clinics - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals and clinics - Year-over-year growth 2025-2030 (%)

10.4 Diagnostic laboratories - Market size and forecast 2025-2030

Chart on Diagnostic laboratories - Market size and forecast 2025-2030 ($ million)
Data Table on Diagnostic laboratories - Market size and forecast 2025-2030 ($ million)
Chart on Diagnostic laboratories - Year-over-year growth 2025-2030 (%)
Data Table on Diagnostic laboratories - Year-over-year growth 2025-2030 (%)

10.5 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ million)
Data Table on Thailand - Market size and forecast 2025-2030 ($ million)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.3 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.5 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.6 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.7 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Growing burden of cardiovascular disease and acute cardiac events
Advancing adoption of high-sensitivity diagnostic technologies
Increasing emphasis on rapid emergency care and clinical decision-making

13.2 Market challenges

High regulatory and clinical validation burden
Limited reimbursement consistency and healthcare budget constraints
Shortage of skilled laboratory and diagnostic professionals

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Expanding integration of multi-marker testing approaches
Evolving shift toward decentralized testing environments
Scaling use of digital health and data-driven diagnostic management

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Abbott Laboratories

Abbott Laboratories - Overview
Abbott Laboratories - Business segments
Abbott Laboratories - Key news
Abbott Laboratories - Key offerings
Abbott Laboratories - Segment focus
SWOT

15.5 Beckman Coulter Inc.

Beckman Coulter Inc. - Overview
Beckman Coulter Inc. - Product / Service
Beckman Coulter Inc. - Key offerings
SWOT

15.6 Bio Rad Laboratories Inc.

Bio Rad Laboratories Inc. - Overview
Bio Rad Laboratories Inc. - Business segments
Bio Rad Laboratories Inc. - Key news
Bio Rad Laboratories Inc. - Key offerings
Bio Rad Laboratories Inc. - Segment focus
SWOT

15.7 BioMerieux SA

BioMerieux SA - Overview
BioMerieux SA - Business segments
BioMerieux SA - Key offerings
BioMerieux SA - Segment focus
SWOT

15.8 BioVendor LM

BioVendor LM - Overview
BioVendor LM - Product / Service
BioVendor LM - Key offerings
SWOT

15.9 F. Hoffmann La Roche Ltd.

F. Hoffmann La Roche Ltd. - Overview
F. Hoffmann La Roche Ltd. - Business segments
F. Hoffmann La Roche Ltd. - Key news
F. Hoffmann La Roche Ltd. - Key offerings
F. Hoffmann La Roche Ltd. - Segment focus
SWOT

15.10 Guangzhou Wondfo Biotech Co. Ltd.

Guangzhou Wondfo Biotech Co. Ltd. - Overview
Guangzhou Wondfo Biotech Co. Ltd. - Product / Service
Guangzhou Wondfo Biotech Co. Ltd. - Key offerings
SWOT

15.11 Lepu Medical Co. Ltd.

Lepu Medical Co. Ltd. - Overview
Lepu Medical Co. Ltd. - Product / Service
Lepu Medical Co. Ltd. - Key offerings
SWOT

15.12 Randox Laboratories Ltd.

Randox Laboratories Ltd. - Overview
Randox Laboratories Ltd. - Product / Service
Randox Laboratories Ltd. - Key offerings
SWOT

15.13 Sd Biosensor Inc.

Sd Biosensor Inc. - Overview
Sd Biosensor Inc. - Product / Service
Sd Biosensor Inc. - Key offerings
SWOT

15.14 Shenzhen Mindray Co. Ltd.

Shenzhen Mindray Co. Ltd. - Overview
Shenzhen Mindray Co. Ltd. - Business segments
Shenzhen Mindray Co. Ltd. - Key offerings
Shenzhen Mindray Co. Ltd. - Segment focus
SWOT

15.15 Siemens Healthineers AG

Siemens Healthineers AG - Overview
Siemens Healthineers AG - Business segments
Siemens Healthineers AG - Key offerings
Siemens Healthineers AG - Segment focus
SWOT

15.16 Sysmex Corp.

Sysmex Corp. - Overview
Sysmex Corp. - Business segments
Sysmex Corp. - Key offerings
Sysmex Corp. - Segment focus
SWOT

15.17 Thermo Fisher Scientific Inc.

Thermo Fisher Scientific Inc. - Overview
Thermo Fisher Scientific Inc. - Business segments
Thermo Fisher Scientific Inc. - Key news
Thermo Fisher Scientific Inc. - Key offerings
Thermo Fisher Scientific Inc. - Segment focus
SWOT

15.18 Tosoh Bioscience

Tosoh Bioscience - Overview
Tosoh Bioscience - Product / Service
Tosoh Bioscience - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Cardiac Biomarkers market growth will increase by USD 11807.5 million during 2026-2030.

The Cardiac Biomarkers market is expected to grow at a CAGR of 13.3% during 2026-2030.

Cardiac Biomarkers market is segmented by Technology (Conventional laboratory testing, POC testing) Product (Troponin, BNP and NT-proBNP, CK-MB, Myoglobin, Others) End-user (Hospitals and clinics, Diagnostic laboratories)

Abbott Laboratories, Beckman Coulter Inc., Bio Rad Laboratories Inc., BioMerieux SA, BioVendor LM, Boditech Med Inc., DiaSorin SpA, F. Hoffmann La Roche Ltd., Getein Biotech Inc., Guangzhou Wondfo Biotech Co. Ltd., Jiangsu Orient Gene Biotech, Lepu Medical Co. Ltd., QuidelOrtho Corp., Radiometer Medical ApS, Randox Laboratories Ltd., Sd Biosensor Inc., Shenzhen Mindray Co. Ltd., Siemens Healthineers AG, Snibe Co.Ltd., Sysmex Corp., Thermo Fisher Scientific Inc., Tosoh Bioscience, Trinity Biotech Plc are a few of the key vendors in the Cardiac Biomarkers market.

North America will register the highest growth rate of 36.9% among the other regions. Therefore, the Cardiac Biomarkers market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Thailand, Indonesia, Brazil, Saudi Arabia, UAE, Turkey, South Africa, Argentina, Colombia, Israel

  • Growing burden of cardiovascular disease and acute cardiac events is the driving factor this market.

The Cardiac Biomarkers market vendors should focus on grabbing business opportunities from the Technology segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
