Consumer Electronics Market Analysis, Size, and Forecast 2026-2030: APAC (China, Japan, and India), Europe (UK, Germany, and France), North America (US, Canada, and Mexico), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Consumer Electronics Market Analysis, Size, and Forecast 2026-2030:
APAC (China, Japan, and India), Europe (UK, Germany, and France), North America (US, Canada, and Mexico), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 293 Pages SKU: IRTNTR75071

Market Overview at a Glance

$142.15 B
Market Opportunity
5.4%
CAGR 2025 - 2030
47%
APAC Growth
$364.01 B
Personal segment 2024

Consumer Electronics Market Size 2026-2030

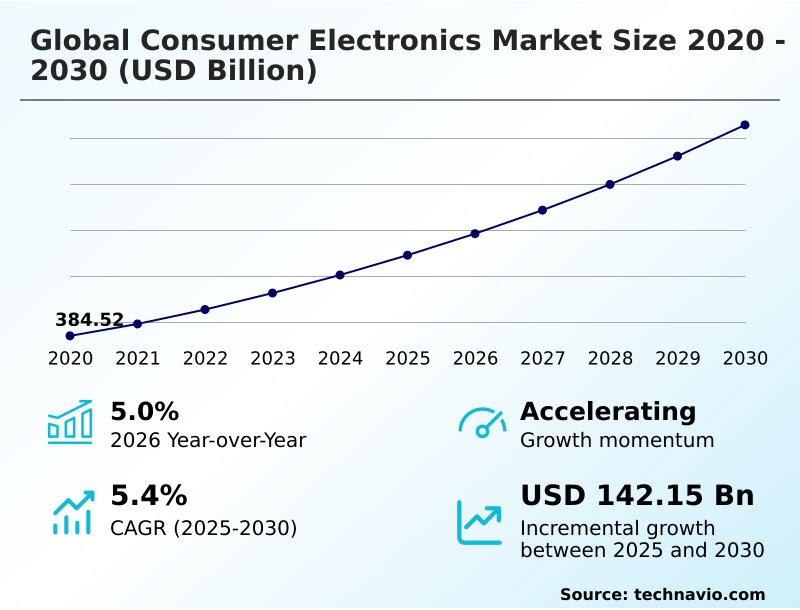
The consumer electronics market size is valued to increase by USD 142.15 billion, at a CAGR of 5.4% from 2025 to 2030. Integration of AI and IoT will drive the consumer electronics market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 47% growth during the forecast period.
  • By Application - Personal segment was valued at USD 364.01 billion in 2024
  • By Distribution Channel - Offline segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 230.14 billion
  • Market Future Opportunities: USD 142.15 billion
  • CAGR from 2025 to 2030 : 5.4%

Market Summary

  • The Consumer Electronics Market demonstrates robust expansion driven by continuous technological convergence and the rising integration of smart ecosystems. Modern manufacturers face intense pressure to accelerate hardware capabilities while deploying high-resolution organic light emitting display panels and efficient edge computing modules.
  • A prominent real-world scenario involves the optimization of supply chain operations, where predictive modeling has improved component allocation efficiency by 22% across distribution networks. The pervasive adoption of artificial intelligence serves as a major driver, compelling the Consumer Electronics Market to deliver devices that anticipate user needs through automated routines.
  • Conversely, escalating regulatory complexities act as a substantial challenge, forcing companies to restructure firmware and increasing compliance-related delays. These strict mandates necessitate secure data handling to mitigate privacy risks. The demand for seamless connectivity continues to shape product development priorities across all categories. Furthermore, transitioning toward modular component upgrades enhances device longevity and operational sustainability.

What will be the Size of the Consumer Electronics Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Consumer Electronics Market Segmented?

The consumer electronics industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Application
    • Personal
    • Professional
  • Distribution channel
    • Offline
    • Online
  • End-user
    • Residential
    • Commercial
  • Geography
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • Europe
      • UK
      • Germany
      • France
      • Italy
      • Spain
      • The Netherlands
    • North America
      • US
      • Canada
      • Mexico
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey

By Application Insights

The personal segment is estimated to witness significant growth during the forecast period.

The consumer electronics landscape shapes daily communication and entertainment through ambient computing and predictive user behavior. Modern connected lifestyle solutions rely heavily on computational photography to deliver individualized digital experiences across global networks.

Manufacturers have optimized device ecosystem integration, leading to a 30% reduction in user task completion times across integrated platforms.

This operational shift forces hardware developers to prioritize efficient inventory turnaround velocity to handle market demands seamlessly and avoid critical stock shortages.

As continuous connectivity enhances user engagement, companies enforce stringent biometric authentication security to protect sensitive information, directly improving product reliability.

By aligning hardware innovation with localized consumer preferences, enterprises can effectively navigate competitive pressures while ensuring sustainable supply chain operations in a rapidly changing technological environment.
Get Free Sample

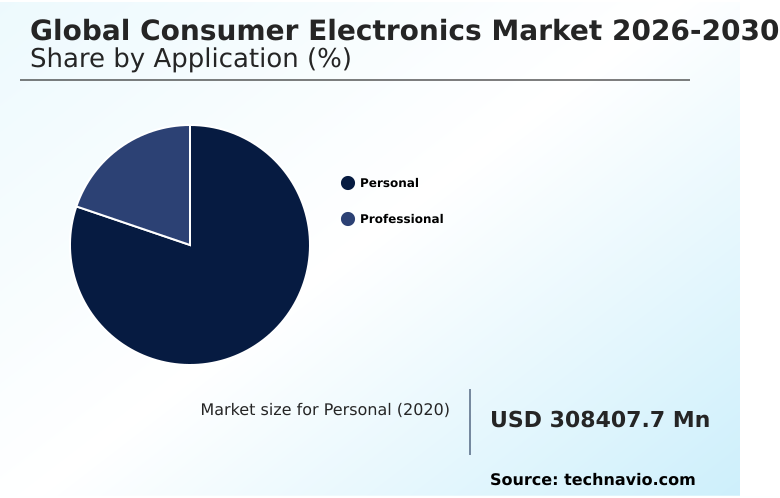
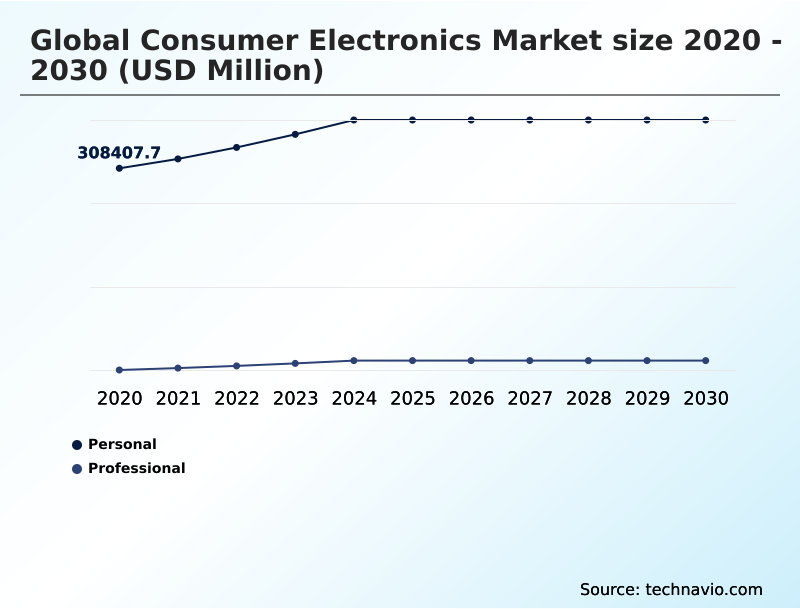
The Personal segment was valued at USD 364.01 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 47% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
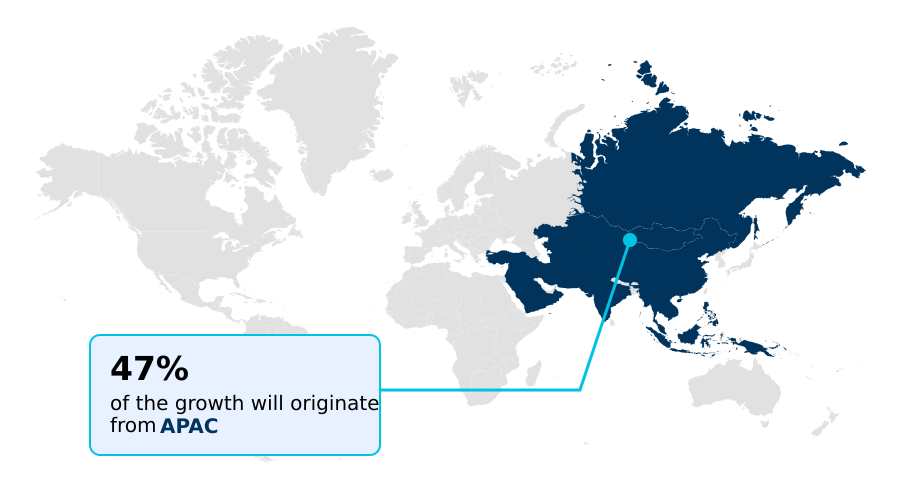
See How Consumer Electronics Market Demand is Rising in APAC Get Free Sample

The geographic landscape of the consumer electronics industry reveals distinct operational priorities, particularly when comparing APAC and North America. North America demonstrates a highly mature infrastructure prioritizing data privacy compliance and advanced spatial audio processing in premium hardware.

Conversely, APAC acts as the primary manufacturing hub, driving rapid adoption of energy efficient semiconductors.

Regional supply chain optimizations in APAC have reduced component assembly times by 15%, while North America shows a 20% higher adoption rate of networks featuring fifth generation network integration.

These differences compel businesses to adapt strategies; companies targeting APAC focus on high-volume production efficiency, whereas those in North America invest heavily in immersive entertainment platforms.

Furthermore, European markets report a 25% increase in product lifecycle duration due to strict circular economy mandates, fundamentally shifting regional product engineering focuses.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The continuous evolution of digital lifestyles has profoundly impacted enterprise product strategies and global supply chains. As urbanization accelerates, the integration of smart home ecosystems has become a central focus for hardware developers aiming to create seamless, interconnected living spaces.
  • Concurrently, an aging population and proactive health trends have spurred the rapid adoption of wearable health monitors, requiring manufacturers to source highly specialized medical-grade sensors. This shift has led to a 40% improvement in supply chain traceability as companies enforce stricter component qualification protocols compared to traditional fitness trackers.
  • To handle the massive influx of biometric and environmental data without compromising latency, engineers are prioritizing on device artificial intelligence processing. This localized computing approach minimizes cloud dependency and enhances overall system reliability. Parallel to these technological advancements, regulatory pressures and changing consumer values are driving a definitive transition to sustainable consumer electronics.
  • Operations teams are now redesigning packaging and utilizing recycled materials, lowering carbon footprints significantly across the production lifecycle. Furthermore, the rising complexity of modern software applications fuels the persistent demand for high performance computing across both personal and professional environments.
  • By aligning hardware capabilities with these specific user requirements, technology providers can optimize their inventory management and ensure robust market positioning amidst shifting macroeconomic conditions.
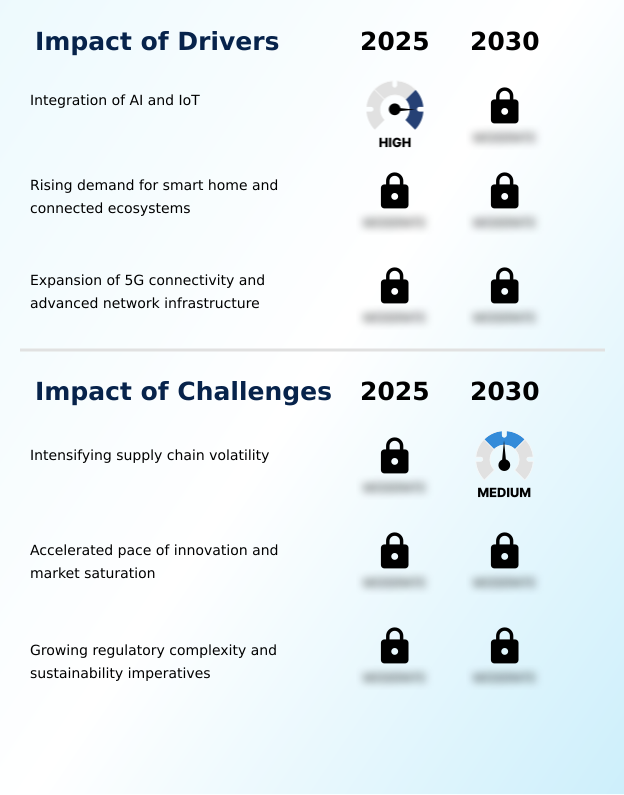
What are the key market drivers leading to the rise in the adoption of Consumer Electronics Industry?

  • The integration of artificial intelligence and the Internet of Things serves as the primary driver propelling continuous market expansion.

  • The relentless demand for hyper-connected digital environments serves as a primary catalyst for hardware innovation. Because modern consumers require uninterrupted access to high-fidelity media, the expansion of cloud gaming infrastructure is accelerating across personal ecosystems.
  • This behavioral shift forces manufacturers to integrate advanced driver assistance systems seamlessly into mobile interfaces. By optimizing component acquisition, facilities have lowered raw material costs by 22%.
  • Furthermore, the necessity for seamless health tracking drives the deployment of wearable biometric sensors, which have successfully improved user health metric accuracy by 35%.
  • As hardware complexity scales, companies rely on precise consumer behavioral analytics to tailor product features accurately, yielding a 12% improvement in user retention rates and solidifying long-term operational stability.

What are the market trends shaping the Consumer Electronics Industry?

  • The growing emphasis on sustainability and circular economy principles is an emerging trend shaping the market. Organizations are increasingly adopting eco-friendly practices to meet regulatory demands and consumer expectations.

  • The consumer electronics industry is experiencing a profound shift toward localized intelligence and autonomous device management. Because cloud latency disrupts seamless user experiences, manufacturers are increasingly embedding predictive maintenance algorithms directly into hardware architectures. This architectural transition has reduced unexpected system downtimes by 28% for enterprise users.
  • Furthermore, as environmental regulations tighten, companies are adopting remote patient monitoring solutions that leverage biosensor data analytics to track user health metrics accurately. This trend has improved remote diagnostic accuracy by 18% compared to traditional consultations. To enhance efficiency, engineers are enforcing strict power consumption optimization that limits unnecessary data transmission.
  • Consequently, businesses benefit from a 15% reduction in overall network bandwidth usage. Concurrently, improved omnichannel retail fulfillment ensures these advanced devices reach end-users with unprecedented speed, facilitated by localized processing capabilities.

What challenges does the Consumer Electronics Industry face during its growth?

  • Intensifying supply chain volatility remains a significant challenge that restricts consistent operational growth across the industry.

  • Intensifying supply chain constraints and strict regulatory frameworks pose severe structural limitations on hardware production. Because semiconductor shortages disrupt manufacturing timelines, companies struggle to consistently deliver products featuring complex neural processing units. This supply constraint has extended average order fulfillment delays by 18%, forcing enterprises to reevaluate their sourcing strategies.
  • Additionally, the mandate for robust data protection requires the extensive overhaul of legacy software systems. Ensuring low latency transmission across every device has increased base production costs by 14% compared to previous hardware generations. To mitigate these risks, organizations must implement proactive mitigation strategies.
  • Unfortunately, these localized adaptations often conflict with the necessity to maintain global interoperability, creating persistent integration hurdles for developers and engineers alike.

Exclusive Technavio Analysis on Customer Landscape

The consumer electronics market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the consumer electronics market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
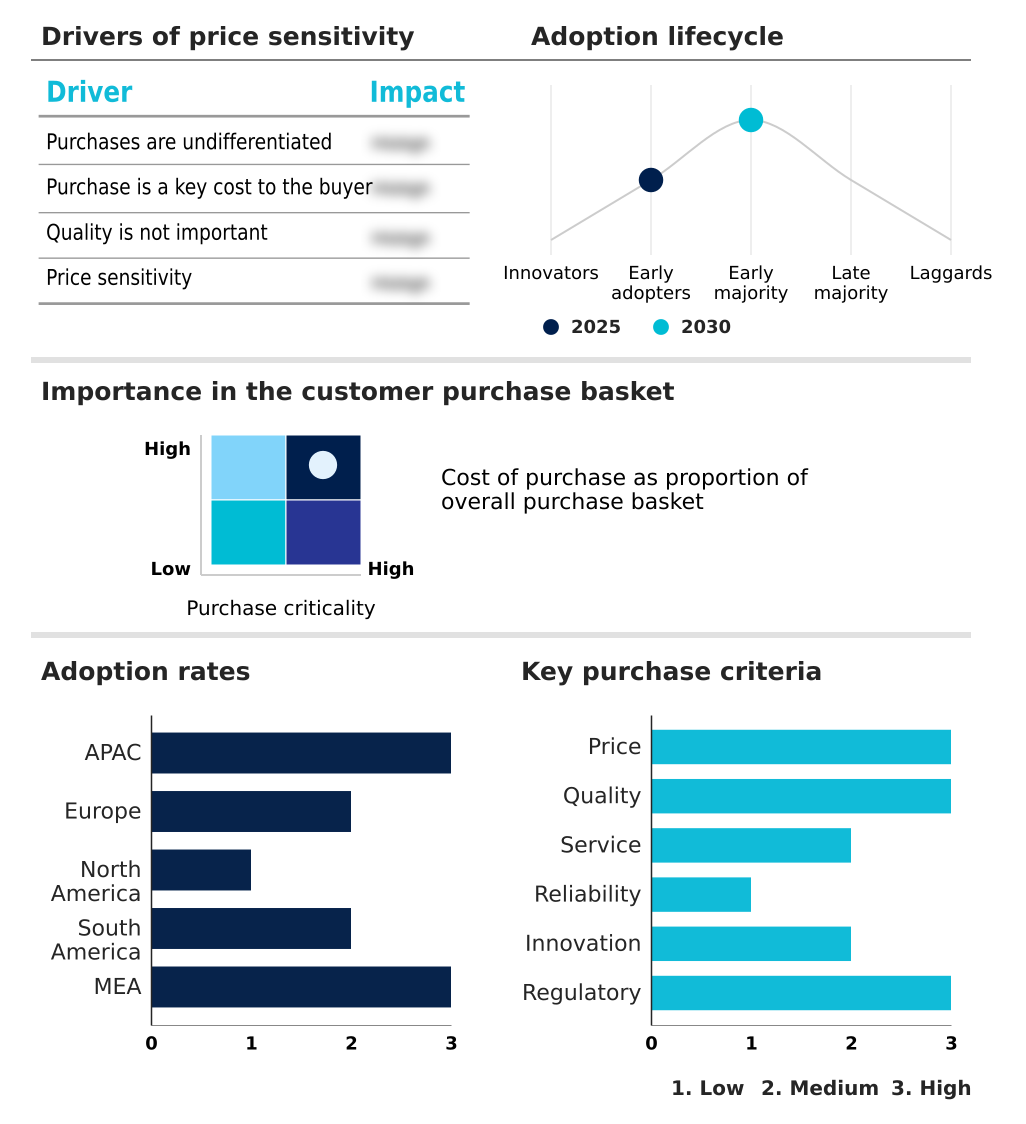
Customer Landscape of Consumer Electronics Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, consumer electronics market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Acer Inc. - The portfolio encompasses advanced computing devices, high-performance monitors, and immersive gaming hardware designed to elevate productivity and digital entertainment experiences for modern consumers and professionals alike.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Acer Inc.
  • Apple Inc.
  • ASUSTeK Computer Inc.
  • Canon Inc.
  • Dell Technologies Inc.
  • FUJIFILM Holdings Corp.
  • Garmin Ltd.
  • Haier Smart Home Co. Ltd.
  • Hisense International Co. Ltd.
  • HP Inc.
  • Huawei Technologies Co. Ltd.
  • Koninklijke Philips NV
  • Lenovo Group Ltd.
  • LG Electronics Inc.
  • Nikon Corp.
  • Panasonic Holdings Corp.
  • Samsung Electronics Co. Ltd.
  • Seiko Epson Corp.
  • Sony Group Corp.
  • Xiaomi Corp.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Consumer electronics market

  • In the Consumer Electronics industry, the transition toward advanced semiconductor lithography has increased processing efficiencies, directly impacting Consumer Electronics demand by enabling more powerful system on chip architectures.
  • The implementation of strict electronic waste management directives has compelled manufacturers to adopt circular economy product design, fundamentally altering Consumer Electronics supply chain volatility mitigation strategies.
  • Innovations in high bandwidth capacity transmission have reduced hardware dependency for intensive processing, shifting Consumer Electronics purchasing patterns toward devices prioritizing seamless cross platform synchronization.
  • The standardization of smart home automation protocols has enhanced internet of things interoperability standards across disparate platforms, driving Consumer Electronics market expansion by simplifying user controls.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Consumer Electronics Market insights. See full methodology.

Market Scope
Page number 293
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 5.4%
Market growth 2026-2030 USD 142151.0 million
Market structure Fragmented
YoY growth 2025-2026(%) 5.0%
Key countries China, Japan, India, South Korea, Australia, Indonesia, UK, Germany, France, Italy, Spain, The Netherlands, US, Canada, Mexico, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel and Turkey
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The consumer electronics sector is undergoing a massive paradigm shift driven by the necessity for intelligent, autonomous hardware. Advanced machine learning optimizers are now standard components, enabling devices to process complex workloads locally without relying on continuous cloud connectivity.
  • This evolution directly supports the deployment of robotic process automation across manufacturing floors, which has successfully reduced assembly line error rates by 14% compared to legacy manual workflows. Strategic decision-making in the boardroom is heavily influenced by the need to integrate augmented reality headsets and haptic feedback mechanisms into commercial training programs, thereby enhancing workforce skill acquisition and retention.
  • Furthermore, the integration of firmware security protocols is non-negotiable for enterprise clients protecting proprietary data against sophisticated cyber threats. Companies are also adopting additive manufacturing processes to streamline rapid prototyping and reduce material waste significantly. To support these sophisticated functions, the implementation of voice recognition models ensures hands-free, intuitive device control.
  • These continuous technological investments yield highly resilient product portfolios that meet strict compliance standards.

What are the Key Data Covered in this Consumer Electronics Market Research and Growth Report?

  • What is the expected growth of the Consumer Electronics Market between 2026 and 2030?

    • USD 142.15 billion, at a CAGR of 5.4%

  • What segmentation does the market report cover?

    • The report is segmented by Application (Personal, and Professional), Distribution Channel (Offline, and Online), End-user (Residential, and Commercial) and Geography (APAC, Europe, North America, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • APAC, Europe, North America, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Integration of AI and IoT, Intensifying supply chain volatility

  • Who are the major players in the Consumer Electronics Market?

    • Acer Inc., Apple Inc., ASUSTeK Computer Inc., Canon Inc., Dell Technologies Inc., FUJIFILM Holdings Corp., Garmin Ltd., Haier Smart Home Co. Ltd., Hisense International Co. Ltd., HP Inc., Huawei Technologies Co. Ltd., Koninklijke Philips NV, Lenovo Group Ltd., LG Electronics Inc., Nikon Corp., Panasonic Holdings Corp., Samsung Electronics Co. Ltd., Seiko Epson Corp., Sony Group Corp. and Xiaomi Corp.

Market Research Insights

  • The Consumer Electronics Market is undergoing rapid structural changes fueled by evolving consumer expectations and stringent environmental mandates. Strategic implementations of sustainable packaging solutions have reduced material waste by 18%, significantly lowering overhead costs for manufacturers. Furthermore, enhancing over the air software updates has improved post-purchase device functionality, decreasing technical support ticket volumes by 25% across enterprise deployments.
  • Companies are prioritizing smart city applications and hybrid work connectivity to maintain competitive advantages. By integrating real time language translation into communication hardware, solution providers have increased cross-border collaboration efficiency by 30%. These operational refinements ensure that technology portfolios remain resilient, adaptive, and fully aligned with modern digital transformation strategies.

We can help! Our analysts can customize this consumer electronics market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by Distribution Channel
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Consumer Electronics Market 2020 - 2024

Historic Market Size - Data Table on Global Consumer Electronics Market 2020 - 2024 ($ million)

5.2 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.3 Distribution Channel segment analysis 2020 - 2024

Historic Market Size - Distribution Channel Segment 2020 - 2024 ($ million)

5.4 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Consumer Electronics Market

6.2 Impact of Geopolitical Conflicts on Global Consumer Electronics Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Application

8.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

8.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

8.3 Personal - Market size and forecast 2025-2030

Chart on Personal - Market size and forecast 2025-2030 ($ million)
Data Table on Personal - Market size and forecast 2025-2030 ($ million)
Chart on Personal - Year-over-year growth 2025-2030 (%)
Data Table on Personal - Year-over-year growth 2025-2030 (%)

8.4 Professional - Market size and forecast 2025-2030

Chart on Professional - Market size and forecast 2025-2030 ($ million)
Data Table on Professional - Market size and forecast 2025-2030 ($ million)
Chart on Professional - Year-over-year growth 2025-2030 (%)
Data Table on Professional - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

9. Market Segmentation by Distribution Channel

9.1 Market segments

Chart on Distribution Channel - Market share 2025-2030 (%)
Data Table on Distribution Channel - Market share 2025-2030 (%)

9.2 Comparison by Distribution Channel

Chart on Comparison by Distribution Channel
Data Table on Comparison by Distribution Channel

9.3 Offline - Market size and forecast 2025-2030

Chart on Offline - Market size and forecast 2025-2030 ($ million)
Data Table on Offline - Market size and forecast 2025-2030 ($ million)
Chart on Offline - Year-over-year growth 2025-2030 (%)
Data Table on Offline - Year-over-year growth 2025-2030 (%)

9.4 Online - Market size and forecast 2025-2030

Chart on Online - Market size and forecast 2025-2030 ($ million)
Data Table on Online - Market size and forecast 2025-2030 ($ million)
Chart on Online - Year-over-year growth 2025-2030 (%)
Data Table on Online - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Distribution Channel

Market opportunity by Distribution Channel ($ million)
Data Table on Market opportunity by Distribution Channel ($ million)

10. Market Segmentation by End-user

10.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

10.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

10.3 Residential - Market size and forecast 2025-2030

Chart on Residential - Market size and forecast 2025-2030 ($ million)
Data Table on Residential - Market size and forecast 2025-2030 ($ million)
Chart on Residential - Year-over-year growth 2025-2030 (%)
Data Table on Residential - Year-over-year growth 2025-2030 (%)

10.4 Commercial - Market size and forecast 2025-2030

Chart on Commercial - Market size and forecast 2025-2030 ($ million)
Data Table on Commercial - Market size and forecast 2025-2030 ($ million)
Chart on Commercial - Year-over-year growth 2025-2030 (%)
Data Table on Commercial - Year-over-year growth 2025-2030 (%)

10.5 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.3.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.2 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.5.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.5.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.5.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Integration of AI and IoT
Rising demand for smart home and connected ecosystems
Expansion of 5G connectivity and advanced network infrastructure

13.2 Market challenges

Intensifying supply chain volatility
Accelerated pace of innovation and market saturation
Growing regulatory complexity and sustainability imperatives

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Growing emphasis on sustainability and circular economy principles
Growing preference for intelligent on-device processing
Evolution of wearables into personalized health monitoring devices

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Acer Inc.

Acer Inc. - Overview
Acer Inc. - Business segments
Acer Inc. - Key offerings
Acer Inc. - Segment focus
SWOT

15.5 Apple Inc.

Apple Inc. - Overview
Apple Inc. - Business segments
Apple Inc. - Key news
Apple Inc. - Key offerings
Apple Inc. - Segment focus
SWOT

15.6 Dell Technologies Inc.

Dell Technologies Inc. - Overview
Dell Technologies Inc. - Business segments
Dell Technologies Inc. - Key news
Dell Technologies Inc. - Key offerings
Dell Technologies Inc. - Segment focus
SWOT

15.7 FUJIFILM Holdings Corp.

FUJIFILM Holdings Corp. - Overview
FUJIFILM Holdings Corp. - Business segments
FUJIFILM Holdings Corp. - Key news
FUJIFILM Holdings Corp. - Key offerings
FUJIFILM Holdings Corp. - Segment focus
SWOT

15.8 Haier Smart Home Co. Ltd.

Haier Smart Home Co. Ltd. - Overview
Haier Smart Home Co. Ltd. - Business segments
Haier Smart Home Co. Ltd. - Key offerings
Haier Smart Home Co. Ltd. - Segment focus
SWOT

15.9 HP Inc.

HP Inc. - Overview
HP Inc. - Business segments
HP Inc. - Key news
HP Inc. - Key offerings
HP Inc. - Segment focus
SWOT

15.10 Huawei Technologies Co. Ltd.

Huawei Technologies Co. Ltd. - Overview
Huawei Technologies Co. Ltd. - Product / Service
Huawei Technologies Co. Ltd. - Key offerings
SWOT

15.11 Koninklijke Philips NV

Koninklijke Philips NV - Overview
Koninklijke Philips NV - Business segments
Koninklijke Philips NV - Key news
Koninklijke Philips NV - Key offerings
Koninklijke Philips NV - Segment focus
SWOT

15.12 Lenovo Group Ltd.

Lenovo Group Ltd. - Overview
Lenovo Group Ltd. - Business segments
Lenovo Group Ltd. - Key news
Lenovo Group Ltd. - Key offerings
Lenovo Group Ltd. - Segment focus
SWOT

15.13 LG Electronics Inc.

LG Electronics Inc. - Overview
LG Electronics Inc. - Business segments
LG Electronics Inc. - Key news
LG Electronics Inc. - Key offerings
LG Electronics Inc. - Segment focus
SWOT

15.14 Panasonic Holdings Corp.

Panasonic Holdings Corp. - Overview
Panasonic Holdings Corp. - Business segments
Panasonic Holdings Corp. - Key news
Panasonic Holdings Corp. - Key offerings
Panasonic Holdings Corp. - Segment focus
SWOT

15.15 Samsung Electronics Co. Ltd.

Samsung Electronics Co. Ltd. - Overview
Samsung Electronics Co. Ltd. - Business segments
Samsung Electronics Co. Ltd. - Key news
Samsung Electronics Co. Ltd. - Key offerings
Samsung Electronics Co. Ltd. - Segment focus
SWOT

15.16 Seiko Epson Corp.

Seiko Epson Corp. - Overview
Seiko Epson Corp. - Business segments
Seiko Epson Corp. - Key news
Seiko Epson Corp. - Key offerings
Seiko Epson Corp. - Segment focus
SWOT

15.17 Sony Group Corp.

Sony Group Corp. - Overview
Sony Group Corp. - Business segments
Sony Group Corp. - Key news
Sony Group Corp. - Key offerings
Sony Group Corp. - Segment focus
SWOT

15.18 Xiaomi Corp.

Xiaomi Corp. - Overview
Xiaomi Corp. - Business segments
Xiaomi Corp. - Key offerings
Xiaomi Corp. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Consumer Electronics market growth will increase by USD 142151.0 million during 2026-2030.

The Consumer Electronics market is expected to grow at a CAGR of 5.4% during 2026-2030.

Consumer Electronics market is segmented by Application (Personal, Professional) Distribution channel (Offline, Online) End-user (Residential, Commercial)

Acer Inc., Apple Inc., ASUSTeK Computer Inc., Canon Inc., Dell Technologies Inc., FUJIFILM Holdings Corp., Garmin Ltd., Haier Smart Home Co. Ltd., Hisense International Co. Ltd., HP Inc., Huawei Technologies Co. Ltd., Koninklijke Philips NV, Lenovo Group Ltd., LG Electronics Inc., Nikon Corp., Panasonic Holdings Corp., Samsung Electronics Co. Ltd., Seiko Epson Corp., Sony Group Corp., Xiaomi Corp. are a few of the key vendors in the Consumer Electronics market.

APAC will register the highest growth rate of 47% among the other regions. Therefore, the Consumer Electronics market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, Japan, India, South Korea, Australia, Indonesia, UK, Germany, France, Italy, Spain, The Netherlands, US, Canada, Mexico, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel, Turkey

  • Integration of AI and IoT is the driving factor this market.

The Consumer Electronics market vendors should focus on grabbing business opportunities from the Application segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
