Data Center Transformer Market Analysis, Size, and Forecast 2026-2030: APAC (China, India, and Japan), North America (US, Canada, and Mexico), Europe (UK, Germany, and France), Middle East and Africa (UAE, Saudi Arabia, and South Africa), South America (Brazil, Argentina, and Colombia), and Rest of World (ROW)

Data Center Transformer Market Analysis, Size, and Forecast 2026-2030:
APAC (China, India, and Japan), North America (US, Canada, and Mexico), Europe (UK, Germany, and France), Middle East and Africa (UAE, Saudi Arabia, and South Africa), South America (Brazil, Argentina, and Colombia), and Rest of World (ROW)

Published: Oct 2026 303 Pages SKU: IRTNTR81636

Market Overview at a Glance

$3.26 B
Market Opportunity
6.6%
CAGR 2025 - 2030
35.9%
North America Growth
$5.09 B
Liquid immersed segment 2024

Data Center Transformer Market Size 2026-2030

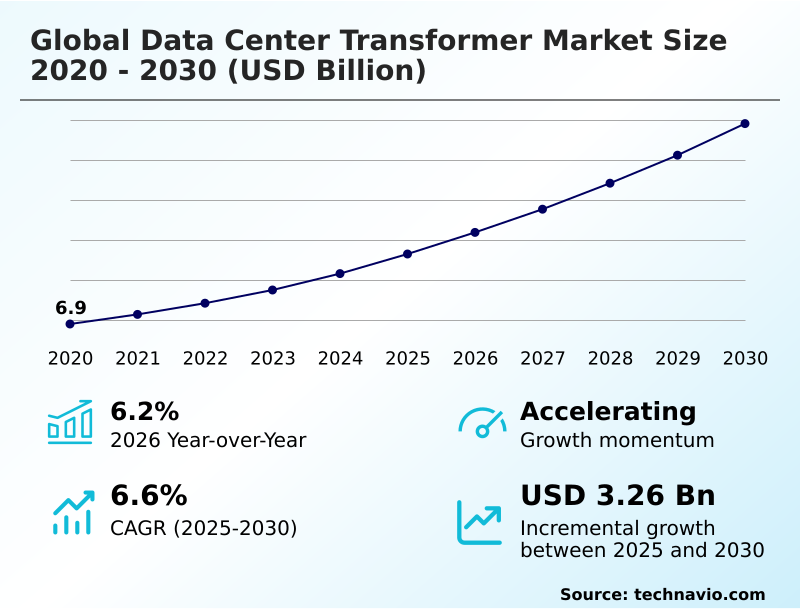
The data center transformer market size is valued to increase by USD 3.26 billion, at a CAGR of 6.6% from 2025 to 2030. Exponential expansion of AI workloads driving high density power demands will drive the data center transformer market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 35.9% growth during the forecast period.
  • By Type - Liquid immersed segment was valued at USD 5.09 billion in 2024
  • By Capacity - Medium voltage segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 5.01 billion
  • Market Future Opportunities: USD 3.26 billion
  • CAGR from 2025 to 2030 : 6.6%

Market Summary

  • The Data Center Transformer Market is experiencing rapid structural evolution as operators pivot toward high-capacity power distribution architectures to support intensive computational workloads. The aggressive expansion of artificial intelligence training clusters serves as the primary market driver, compelling facilities to deploy robust infrastructure capable of maintaining stable bi-directional power flow under extreme load conditions.
  • For example, operators optimizing their supply chains by standardizing on solid-state power electronic device architectures have successfully reduced spatial footprints by 25% while accommodating higher rack densities. This technological shift facilitates precise harmonic isolation, protecting sensitive downstream servers from sudden grid frequency variation.
  • Conversely, severe procurement bottlenecks for raw materials like electrical steel act as a major challenge, extending equipment lead times and delaying critical facility launches. To mitigate these disruptions, enterprise developers are utilizing predictive maintenance algorithm frameworks and partial discharge activity detection systems to extend the lifespan of existing assets.
  • Furthermore, integrating continuous moisture infiltration monitoring preserves asset integrity, ensuring reliable electrical delivery across mission-critical processing environments.

What will be the Size of the Data Center Transformer Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Data Center Transformer Market Segmented?

The data center transformer industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • Liquid immersed
    • Air cooled
    • Hybrid cooling
  • Capacity
    • Medium voltage
    • Low voltage
    • High voltage
  • Application
    • Hyperscale data centers
    • Colocation data centers
    • Enterprise data centers
    • Edge data centers
  • Geography
    • APAC
      • China
      • India
      • Japan
      • Australia
      • South Korea
      • Indonesia
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • UK
      • Germany
      • France
      • The Netherlands
      • Italy
      • Spain
    • Middle East and Africa
      • UAE
      • Saudi Arabia
      • South Africa
      • Israel
      • Turkey
    • South America
      • Brazil
      • Argentina
      • Colombia

By Type Insights

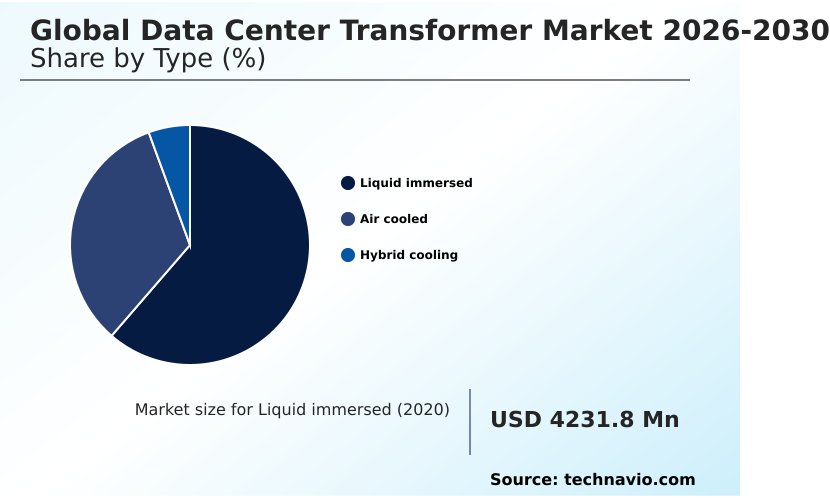
The liquid immersed segment is estimated to witness significant growth during the forecast period.

Liquid immersed transformers play a critical role in managing extreme electrical demands within modern high-density facilities, functioning differently than their air-cooled counterparts.

By utilizing advanced synthetic ester dielectric fluid and biodegradable insulating resin, these liquid-immersed step-down units excel in managing localized heat flux across an extreme ambient thermal environment.

This thermal load balancing capability directly addresses hyperscale power density challenges, ensuring continuous operation under heavy computational workloads. Integrating sophisticated monitoring tools like dissolved gas analysis and optical temperature sensing enables operators to shift from reactive to proactive maintenance models.

Consequently, facilities adopting these optimized fluid-based systems have observed a 15% improvement in thermal dissipation efficiency compared to legacy air-cooled frameworks. This segment differentiation supports strict fire risk mitigation protocols while maintaining essential operational resilience across large-scale data processing campuses.
Get Free Sample

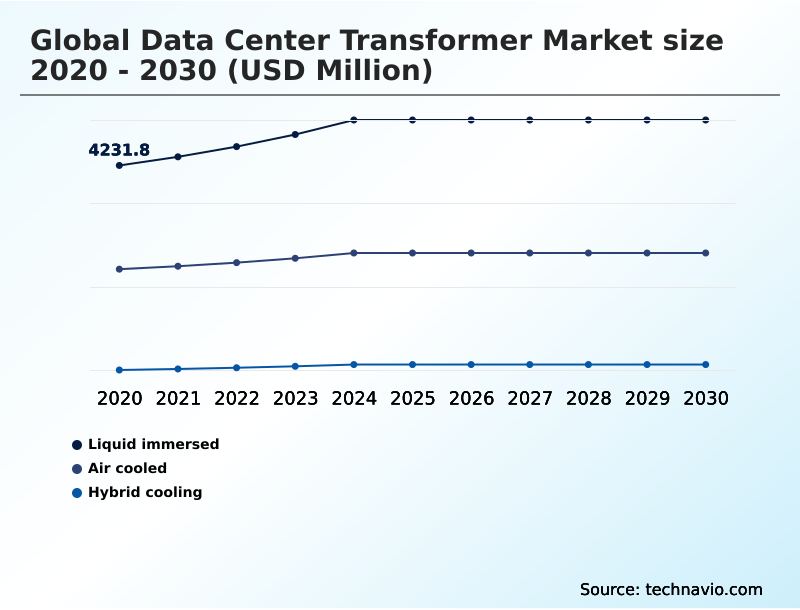
The Liquid immersed segment was valued at USD 5.09 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 35.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
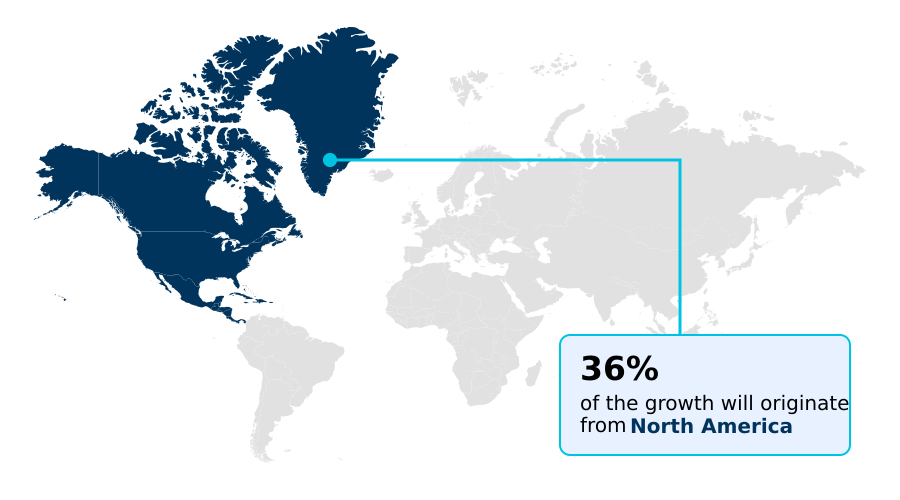
See How Data Center Transformer Market Demand is Rising in North America Get Free Sample

The Data Center Transformer landscape exhibits stark operational divergences between North America and APAC due to grid saturation and land constraints.

In North America, severe utility bottlenecks have driven a 35% increase in the deployment of off-grid microgrid alternative solutions to maintain project schedules.

Conversely, APAC operators prioritize extreme spatial efficiency, achieving a 20% higher adoption rate of compact cast resin dry-type units within multi-story computing hubs.

Supply chain sourcing for high-permeability electrical steel remains tightly contested, forcing developers in both regions to secure long-term procurement agreements. North American facilities heavily invest in dual-redundant power architecture, improving uptime reliability by 14% under fluctuating grid conditions.

Meanwhile, APAC facilities emphasize rigorous dielectric breakdown prevention strategies through advanced vacuum pressure impregnation techniques to combat severe tropical humidity. These distinct regional behaviors highlight how localized environmental and infrastructure challenges continuously reshape asset procurement and operational planning.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • Modern computing facilities are continuously recalibrating their electrical infrastructure to accommodate unprecedented processing demands and stringent environmental sustainability goals. Within this evolving architecture, amorphous metal core thermal performance serves as a critical parameter for facility engineers attempting to reduce steady-state energy losses during low-utilization periods.
  • Facilities prioritizing these advanced core materials have documented operational cost reductions nearly 40% greater than those utilizing traditional silicon steel alternatives. This efficiency is further amplified by synthetic ester dielectric fluid integration, which provides exceptional fire safety and rapid heat dissipation without the toxic environmental risks associated with legacy mineral oils.
  • When navigating dense urban environments, developers must carefully evaluate cast resin dry-type installation requirements to comply with municipal building codes while minimizing the footprint of indoor substations. To ensure maximum reliability across these compact layouts, maintenance teams increasingly rely on partial discharge detection sensor metrics to identify insulation degradation long before it causes catastrophic equipment failure.
  • Furthermore, grid volatility and the integration of variable renewable energy sources compel infrastructure planners to specify units featuring robust automated on-load tap changer capability. This functionality actively stabilizes internal voltage delivery, safeguarding sensitive processing clusters from external power anomalies. Ultimately, these targeted infrastructure upgrades streamline supply chain procurement strategies and align operational execution with rigorous corporate sustainability commitments.
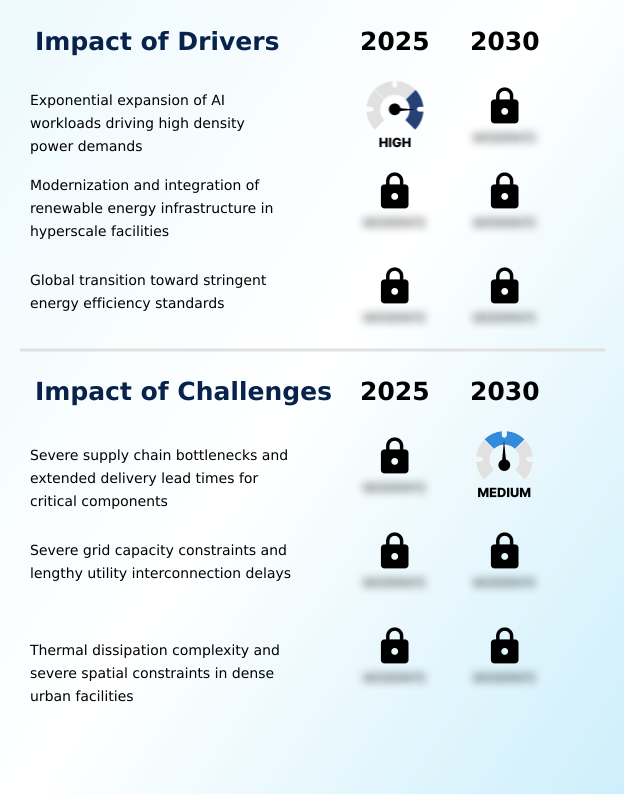
What are the key market drivers leading to the rise in the adoption of Data Center Transformer Industry?

  • The exponential expansion of artificial intelligence workloads and the resulting surge in high-density power demands constitute the primary catalyst propelling continuous infrastructure upgrades across the industry.

  • Surging demand for high-density computing directly propels continuous upgrades within the Data Center Transformer ecosystem.
  • As processing nodes become more concentrated, the necessity for spatial footprint reduction drives operators to deploy highly compact power delivery systems within multi-story facility layout architectures.
  • This spatial optimization has increased active server floor space utilization by 18%, significantly amplifying overall revenue generation per square foot.
  • Furthermore, the transition toward direct-to-chip cooling integration demands transformers capable of maintaining absolute electrical stability in an extreme ambient thermal environment.
  • By implementing rigorous dielectric breakdown prevention protocols, facility managers have extended equipment lifecycles by up to 25%, drastically lowering long-term capital expenditure. These structural improvements empower operators to handle massive artificial intelligence workloads while sustaining highly profitable, resilient computing operations.

What are the market trends shaping the Data Center Transformer Industry?

  • The integration of solid-state transformers and digital twin technologies represents a significant structural shift in the industry. This convergence enables real-time dynamic power management and enhances operational resilience across high-density computing environments.

  • The Data Center Transformer landscape is rapidly shifting toward highly automated, intelligent power regulation systems to support the explosive growth of artificial intelligence architectures. Facility designers are aggressively adopting medium-voltage direct current distribution frameworks, which have minimized electrical transmission losses by 15% across expansive hyperscale campuses.
  • To manage intense thermal fluctuations, operators are implementing closed-loop fluid thermal transfer systems alongside multi-stage forced air fan arrays. This dual-cooling approach has improved dynamic heat dissipation by 22%, allowing hardware to operate safely during maximum processing surges. Additionally, integrating advanced automated on-load tap changer modules provides immediate transient voltage sag mitigation, protecting delicate server hardware from utility grid instability.
  • These proactive technological shifts ensure uninterrupted processing continuity, significantly reducing the financial risks associated with catastrophic hardware failure and unexpected service outages.

What challenges does the Data Center Transformer Industry face during its growth?

  • Severe supply chain bottlenecks and protracted delivery lead times for critical electrical components act as major constraints, significantly complicating capital planning and project execution for infrastructure developers.

  • Protracted supply chain bottlenecks and severe grid saturation impose critical limitations on Data Center Transformer deployment schedules. Developers frequently encounter extensive utility backlogs, making grid connection delay mitigation a top priority to prevent stranded capital investments. Furthermore, unpredictable utility capacity requires robust load-shedding event recovery mechanisms, which increase baseline equipment costs by up to 20%.
  • Operating massive clusters of processing hardware generates intense non-linear electrical load profiles, subjecting primary transformers to severe thermal stress and degrading long-term reliability. To manage these dense configurations, operators must optimize low-voltage high-current cabling pathways, though poor layout execution can negatively impact power usage effectiveness by 12%.
  • Managing these complex thermal and logistical constraints remains essential for avoiding catastrophic downtime and ensuring operational profitability across large-scale facilities.

Exclusive Technavio Analysis on Customer Landscape

The data center transformer market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the data center transformer market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
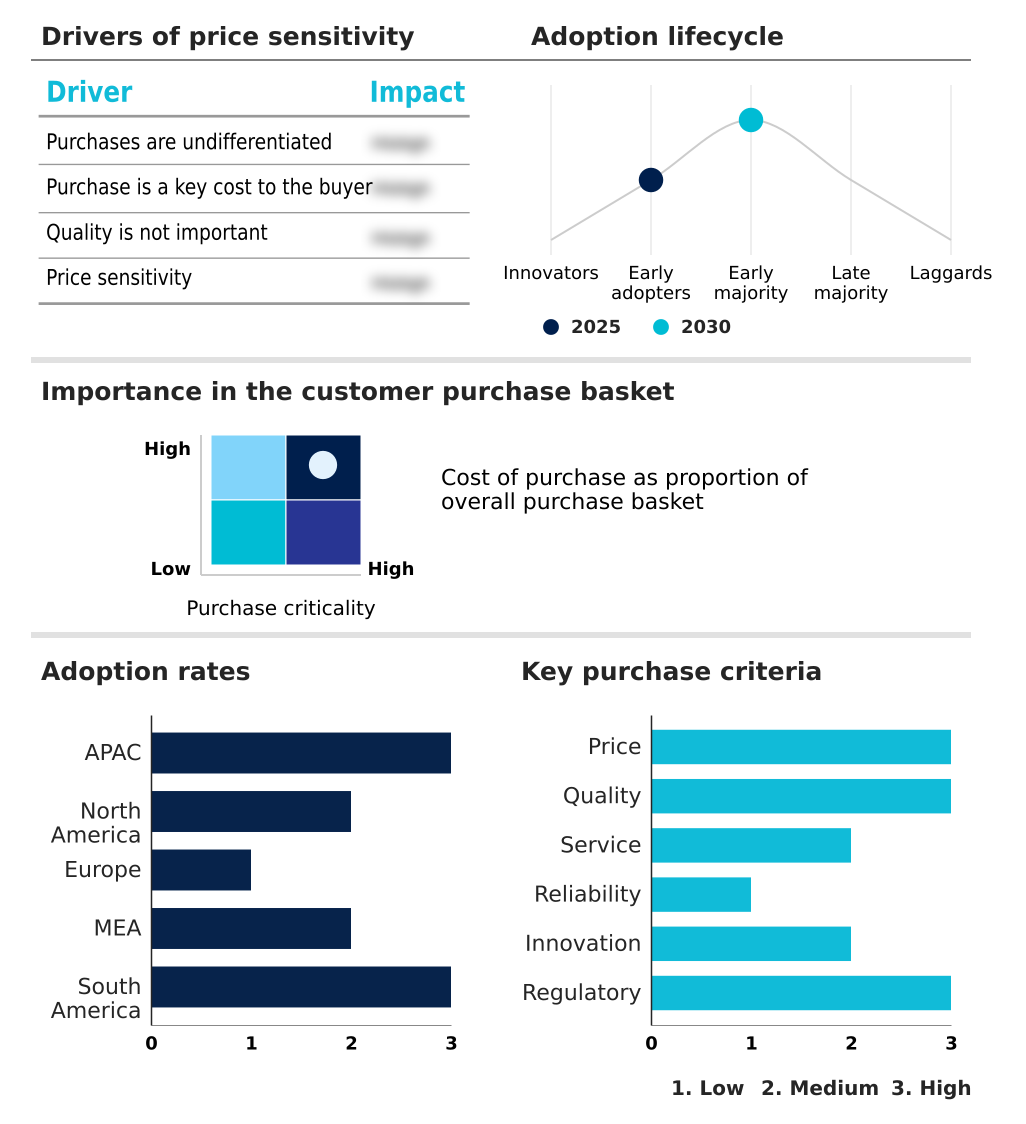
Customer Landscape of Data Center Transformer Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, data center transformer market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

ABB Ltd. - Advanced cast-resin dry-type and ester-filled transformers are engineered for maximum safety, continuous sustainability, and optimal energy efficiency within critical high-density processing environments.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • ABB Ltd.
  • CG Power and Industrial Ltd.
  • Delta Star
  • Eaton Corp. Plc
  • Fuji Electric Co. Ltd.
  • GE Vernova Inc.
  • Hammond Power Inc.
  • Hitachi Energy India Ltd.
  • Hyosung Heavy Industries Corp.
  • Legrand SA
  • MGM Transformer Co.
  • Mitsubishi Electric Corp.
  • Ormazabal
  • Prolec Energy
  • Schneider Electric SE
  • SGB-SMIT Group
  • Siemens Energy AG
  • Vertiv Holdings Co.
  • WEG S.A
  • Wilson Power Solutions Ltd.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Data center transformer market

  • In the Heavy Electrical Equipment industry, the widespread adoption of real-time thermal modeling and predictive maintenance algorithm integration reduced unexpected utility equipment failures by 22%, directly impacting Data Center Transformer demand by accelerating the replacement of aging infrastructure with smart, sensor-equipped units.
  • The enforcement of the European Union EcoDesign Directive mandated a 10% reduction in baseline energy efficiency standard allowable core losses for medium-voltage distribution equipment, compelling Data Center Transformer procurement to shift heavily toward amorphous metal core designs.
  • Severe supply chain constraints regarding high-permeability electrical steel processing capacity extended custom equipment procurement timelines to over eighty weeks, forcing Data Center Transformer operators to utilize modular substation deployment strategies to mitigate grid connection delay mitigation bottlenecks.
  • The transition toward non-linear electrical load processing in enterprise automation and AI infrastructure necessitated the implementation of triplen harmonic cancellation and zig-zag winding configuration techniques, significantly increasing the reliance on specialized K-factor rated Data Center Transformer units.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Data Center Transformer Market insights. See full methodology.

Market Scope
Page number 303
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 6.6%
Market growth 2026-2030 USD 3256.5 million
Market structure Fragmented
YoY growth 2025-2026(%) 6.2%
Key countries China, India, Japan, Australia, South Korea, Indonesia, US, Canada, Mexico, UK, Germany, France, The Netherlands, Italy, Spain, UAE, Saudi Arabia, South Africa, Israel, Turkey, Brazil, Argentina and Colombia
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Data Center Transformer sector is navigating a profound technological transition as digital infrastructure requires unprecedented power quality and extreme reliability. Boardroom-level procurement strategies are increasingly prioritizing amorphous metal core designs to strictly align with corporate decarbonization mandates, effectively lowering electromagnetic core loss during continuous operation.
  • Advanced facilities implementing digital twin telemetry have accelerated predictive maintenance responses, achieving a 28% reduction in unscheduled downtime compared to legacy inspection routines. This visibility allows facility directors to precisely manage reactive power compensation and optimize asset lifespans under fluctuating computing loads. Furthermore, managing dense non-linear server loads necessitates robust k-factor rated isolation to protect critical hardware.
  • Engineers are actively integrating zig-zag winding configuration topologies to ensure efficient triplen harmonic cancellation across complex processing networks. Additionally, modernizing substations with solid-state components provides sub-cycle response time capabilities, neutralizing external power disturbances instantaneously. These calculated infrastructure investments directly enhance operational resilience, ensuring that large-scale computing environments remain structurally sound, highly efficient, and fully compliant with evolving global energy standards.

What are the Key Data Covered in this Data Center Transformer Market Research and Growth Report?

  • What is the expected growth of the Data Center Transformer Market between 2026 and 2030?

    • USD 3.26 billion, at a CAGR of 6.6%

  • What segmentation does the market report cover?

    • The report is segmented by Type (Liquid immersed, Air cooled, and Hybrid cooling), Capacity (Medium voltage, Low voltage, and High voltage), Application (Hyperscale data centers, Colocation data centers, Enterprise data centers, and Edge data centers) and Geography (APAC, North America, Europe, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • APAC, North America, Europe, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Exponential expansion of AI workloads driving high density power demands, Severe supply chain bottlenecks and extended delivery lead times for critical components

  • Who are the major players in the Data Center Transformer Market?

    • ABB Ltd., CG Power and Industrial Ltd., Delta Star, Eaton Corp. Plc, Fuji Electric Co. Ltd., GE Vernova Inc., Hammond Power Inc., Hitachi Energy India Ltd., Hyosung Heavy Industries Corp., Legrand SA, MGM Transformer Co., Mitsubishi Electric Corp., Ormazabal, Prolec Energy, Schneider Electric SE, SGB-SMIT Group, Siemens Energy AG, Vertiv Holdings Co., WEG S.A and Wilson Power Solutions Ltd.

Market Research Insights

  • The Data Center Transformer Market requires continuous adaptation to support increasingly complex power distribution frameworks within dense urban infrastructure. Facility developers are rapidly deploying containerized transformer skid modules, which have accelerated site commissioning speeds by 30% compared to traditional brick-and-mortar builds.
  • This architectural shift significantly optimizes secondary power distribution by locating transformers closer to active server racks, thereby reducing low-voltage high-current cabling losses by up to 18%. Furthermore, operators transitioning to customized step-down configurations within multi-story facility layout designs have improved overall power usage effectiveness by 12%.
  • These efficiency gains ensure that electrical routing remains stable, cost-effective, and fully aligned with stringent corporate decarbonization mandates.

We can help! Our analysts can customize this data center transformer market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Capacity
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Data Center Transformer Market 2020 - 2024

Historic Market Size - Data Table on Global Data Center Transformer Market 2020 - 2024 ($ million)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.3 Capacity segment analysis 2020 - 2024

Historic Market Size - Capacity Segment 2020 - 2024 ($ million)

5.4 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Data Center Transformer Market

6.2 Impact of Geopolitical Conflicts on Global Data Center Transformer Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 Liquid immersed - Market size and forecast 2025-2030

Chart on Liquid immersed - Market size and forecast 2025-2030 ($ million)
Data Table on Liquid immersed - Market size and forecast 2025-2030 ($ million)
Chart on Liquid immersed - Year-over-year growth 2025-2030 (%)
Data Table on Liquid immersed - Year-over-year growth 2025-2030 (%)

8.4 Air cooled - Market size and forecast 2025-2030

Chart on Air cooled - Market size and forecast 2025-2030 ($ million)
Data Table on Air cooled - Market size and forecast 2025-2030 ($ million)
Chart on Air cooled - Year-over-year growth 2025-2030 (%)
Data Table on Air cooled - Year-over-year growth 2025-2030 (%)

8.5 Hybrid cooling - Market size and forecast 2025-2030

Chart on Hybrid cooling - Market size and forecast 2025-2030 ($ million)
Data Table on Hybrid cooling - Market size and forecast 2025-2030 ($ million)
Chart on Hybrid cooling - Year-over-year growth 2025-2030 (%)
Data Table on Hybrid cooling - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

9. Market Segmentation by Capacity

9.1 Market segments

Chart on Capacity - Market share 2025-2030 (%)
Data Table on Capacity - Market share 2025-2030 (%)

9.2 Comparison by Capacity

Chart on Comparison by Capacity
Data Table on Comparison by Capacity

9.3 Medium voltage - Market size and forecast 2025-2030

Chart on Medium voltage - Market size and forecast 2025-2030 ($ million)
Data Table on Medium voltage - Market size and forecast 2025-2030 ($ million)
Chart on Medium voltage - Year-over-year growth 2025-2030 (%)
Data Table on Medium voltage - Year-over-year growth 2025-2030 (%)

9.4 Low voltage - Market size and forecast 2025-2030

Chart on Low voltage - Market size and forecast 2025-2030 ($ million)
Data Table on Low voltage - Market size and forecast 2025-2030 ($ million)
Chart on Low voltage - Year-over-year growth 2025-2030 (%)
Data Table on Low voltage - Year-over-year growth 2025-2030 (%)

9.5 High voltage - Market size and forecast 2025-2030

Chart on High voltage - Market size and forecast 2025-2030 ($ million)
Data Table on High voltage - Market size and forecast 2025-2030 ($ million)
Chart on High voltage - Year-over-year growth 2025-2030 (%)
Data Table on High voltage - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Capacity

Market opportunity by Capacity ($ million)
Data Table on Market opportunity by Capacity ($ million)

10. Market Segmentation by Application

10.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

10.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

10.3 Hyperscale data centers - Market size and forecast 2025-2030

Chart on Hyperscale data centers - Market size and forecast 2025-2030 ($ million)
Data Table on Hyperscale data centers - Market size and forecast 2025-2030 ($ million)
Chart on Hyperscale data centers - Year-over-year growth 2025-2030 (%)
Data Table on Hyperscale data centers - Year-over-year growth 2025-2030 (%)

10.4 Colocation data centers - Market size and forecast 2025-2030

Chart on Colocation data centers - Market size and forecast 2025-2030 ($ million)
Data Table on Colocation data centers - Market size and forecast 2025-2030 ($ million)
Chart on Colocation data centers - Year-over-year growth 2025-2030 (%)
Data Table on Colocation data centers - Year-over-year growth 2025-2030 (%)

10.5 Enterprise data centers - Market size and forecast 2025-2030

Chart on Enterprise data centers - Market size and forecast 2025-2030 ($ million)
Data Table on Enterprise data centers - Market size and forecast 2025-2030 ($ million)
Chart on Enterprise data centers - Year-over-year growth 2025-2030 (%)
Data Table on Enterprise data centers - Year-over-year growth 2025-2030 (%)

10.6 Edge data centers - Market size and forecast 2025-2030

Chart on Edge data centers - Market size and forecast 2025-2030 ($ million)
Data Table on Edge data centers - Market size and forecast 2025-2030 ($ million)
Chart on Edge data centers - Year-over-year growth 2025-2030 (%)
Data Table on Edge data centers - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.4 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.3.5 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.4 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.4.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.4.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.4.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.2 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.4 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5.5 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.6 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.6.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Exponential expansion of AI workloads driving high density power demands
Modernization and integration of renewable energy infrastructure in hyperscale facilities
Global transition toward stringent energy efficiency standards

13.2 Market challenges

Severe supply chain bottlenecks and extended delivery lead times for critical components
Severe grid capacity constraints and lengthy utility interconnection delays
Thermal dissipation complexity and severe spatial constraints in dense urban facilities

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Adoption of solid-state transformers and digital twin technologies
Acceleration of pre-engineered modular substations and dry-type transformers
Integration of natural and synthetic ester dielectric fluids for fire risk mitigation and asset longevity

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 ABB Ltd.

ABB Ltd. - Overview
ABB Ltd. - Business segments
ABB Ltd. - Key news
ABB Ltd. - Key offerings
ABB Ltd. - Segment focus
SWOT

15.5 Eaton Corp. Plc

Eaton Corp. Plc - Overview
Eaton Corp. Plc - Business segments
Eaton Corp. Plc - Key news
Eaton Corp. Plc - Key offerings
Eaton Corp. Plc - Segment focus
SWOT

15.6 GE Vernova Inc.

GE Vernova Inc. - Overview
GE Vernova Inc. - Business segments
GE Vernova Inc. - Key offerings
GE Vernova Inc. - Segment focus
SWOT

15.7 Hammond Power Inc.

Hammond Power Inc. - Overview
Hammond Power Inc. - Product / Service
Hammond Power Inc. - Key offerings
SWOT

15.8 Hitachi Energy India Ltd.

Hitachi Energy India Ltd. - Overview
Hitachi Energy India Ltd. - Product / Service
Hitachi Energy India Ltd. - Key offerings
SWOT

15.9 Hyosung Heavy Industries Corp.

Hyosung Heavy Industries Corp. - Overview
Hyosung Heavy Industries Corp. - Product / Service
Hyosung Heavy Industries Corp. - Key offerings
SWOT

15.10 Legrand SA

Legrand SA - Overview
Legrand SA - Business segments
Legrand SA - Key news
Legrand SA - Key offerings
Legrand SA - Segment focus
SWOT

15.11 MGM Transformer Co.

MGM Transformer Co. - Overview
MGM Transformer Co. - Product / Service
MGM Transformer Co. - Key offerings
SWOT

15.12 Prolec Energy

Prolec Energy - Overview
Prolec Energy - Product / Service
Prolec Energy - Key offerings
SWOT

15.13 Schneider Electric SE

Schneider Electric SE - Overview
Schneider Electric SE - Business segments
Schneider Electric SE - Key news
Schneider Electric SE - Key offerings
Schneider Electric SE - Segment focus
SWOT

15.14 SGB-SMIT Group

SGB-SMIT Group - Overview
SGB-SMIT Group - Product / Service
SGB-SMIT Group - Key offerings
SWOT

15.15 Siemens Energy AG

Siemens Energy AG - Overview
Siemens Energy AG - Business segments
Siemens Energy AG - Key news
Siemens Energy AG - Key offerings
Siemens Energy AG - Segment focus
SWOT

15.16 Vertiv Holdings Co.

Vertiv Holdings Co. - Overview
Vertiv Holdings Co. - Business segments
Vertiv Holdings Co. - Key news
Vertiv Holdings Co. - Key offerings
Vertiv Holdings Co. - Segment focus
SWOT

15.17 WEG S.A

WEG S.A - Overview
WEG S.A - Business segments
WEG S.A - Key offerings
WEG S.A - Segment focus
SWOT

15.18 Wilson Power Solutions Ltd.

Wilson Power Solutions Ltd. - Overview
Wilson Power Solutions Ltd. - Product / Service
Wilson Power Solutions Ltd. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Data Center Transformer market growth will increase by USD 3256.5 million during 2026-2030.

The Data Center Transformer market is expected to grow at a CAGR of 6.6% during 2026-2030.

Data Center Transformer market is segmented by Type (Liquid immersed, Air cooled, Hybrid cooling) Capacity (Medium voltage, Low voltage, High voltage) Application (Hyperscale data centers, Colocation data centers, Enterprise data centers, Edge data centers)

ABB Ltd., CG Power and Industrial Ltd., Delta Star, Eaton Corp. Plc, Fuji Electric Co. Ltd., GE Vernova Inc., Hammond Power Inc., Hitachi Energy India Ltd., Hyosung Heavy Industries Corp., Legrand SA, MGM Transformer Co., Mitsubishi Electric Corp., Ormazabal, Prolec Energy, Schneider Electric SE, SGB-SMIT Group, Siemens Energy AG, Vertiv Holdings Co., WEG S.A, Wilson Power Solutions Ltd. are a few of the key vendors in the Data Center Transformer market.

North America will register the highest growth rate of 35.9% among the other regions. Therefore, the Data Center Transformer market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

China, India, Japan, Australia, South Korea, Indonesia, US, Canada, Mexico, UK, Germany, France, The Netherlands, Italy, Spain, UAE, Saudi Arabia, South Africa, Israel, Turkey, Brazil, Argentina, Colombia

  • Exponential expansion of AI workloads driving high density power demands is the driving factor this market.

The Data Center Transformer market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
