Human Organoids Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Human Organoids Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Published: Oct 2026 299 Pages SKU: IRTNTR73882

Market Overview at a Glance

$1.55 B
Market Opportunity
16.7%
CAGR 2025 - 2030
39.8%
North America Growth
$488.4 Mn
Pharma and biotech companies segment 2024

Human Organoids Market Size 2026-2030

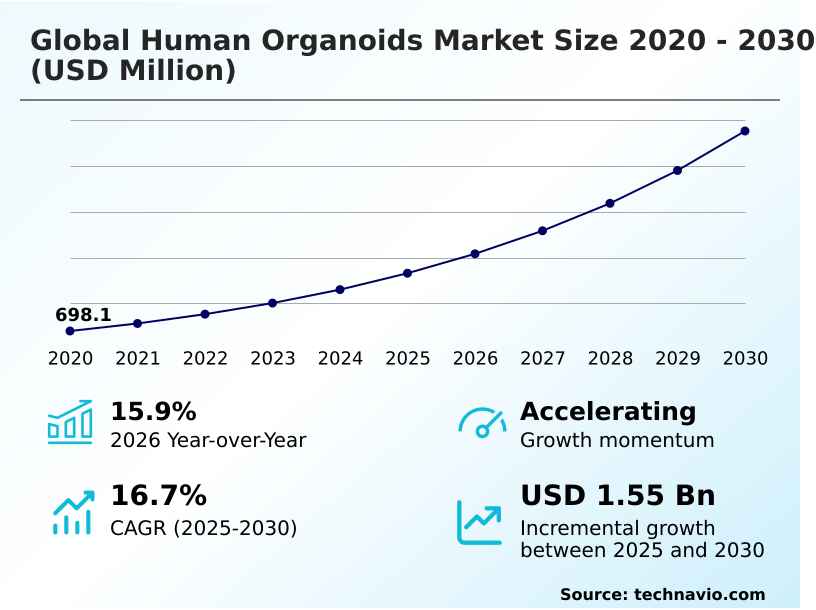
The human organoids market size is valued to increase by USD 1.55 billion, at a CAGR of 16.7% from 2025 to 2030. Increasing adoption of organoid-based models in drug discovery programs will drive the human organoids market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 39.8% growth during the forecast period.
  • By End-user - Pharma and biotech companies segment was valued at USD 488.4 million in 2024
  • By Source - Adult stem cells segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 2.18 billion
  • Market Future Opportunities: USD 1.55 billion
  • CAGR from 2025 to 2030 : 16.7%

Market Summary

  • The Human Organoids Market is expanding rapidly as pharmaceutical and biomedical organizations transition toward more predictive and physiologically relevant preclinical testing frameworks. By integrating stem cell engineering with automated screening technologies, researchers can now evaluate complex biological interactions with unprecedented accuracy.
  • For instance, laboratories implementing ai enabled analytical platforms for organoid imaging have improved data processing efficiency by 35% compared to manual interpretation methods, directly accelerating target identification pipelines. The increasing demand for precision medicine serves as a primary driver, compelling healthcare providers to adopt patient-derived models to evaluate therapeutic responses before initiating clinical trials, which significantly optimizes treatment selection.
  • Conversely, the high operational expenses associated with specialized reagents, advanced biobanking infrastructure, and long-term cultivation cycles restrict broader scalability and pose a persistent challenge for emerging research institutions. The integration of predictive data processing continues to enhance experimental reproducibility across complex tissue assays.
  • Furthermore, the shift toward cross tissue biological investigations allows researchers to replicate systemic human responses, fundamentally altering the trajectory of modern therapeutic development.

What will be the Size of the Human Organoids Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Human Organoids Market Segmented?

The human organoids industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • End-user
    • Pharma and biotech companies
    • Contract research organizations
    • Academic and research institutes
    • Others
  • Source
    • Adult stem cells
    • iPSCs
    • ESCs
    • Others
  • Product
    • Organoid models
    • Media and supplements
    • Reagents
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • Japan
      • India
      • South Korea
      • Indonesia
      • Thailand
    • Rest of World (ROW)

By End-user Insights

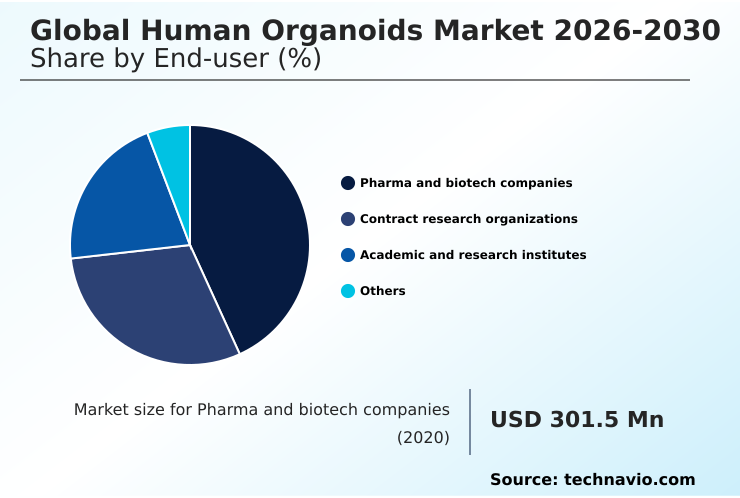
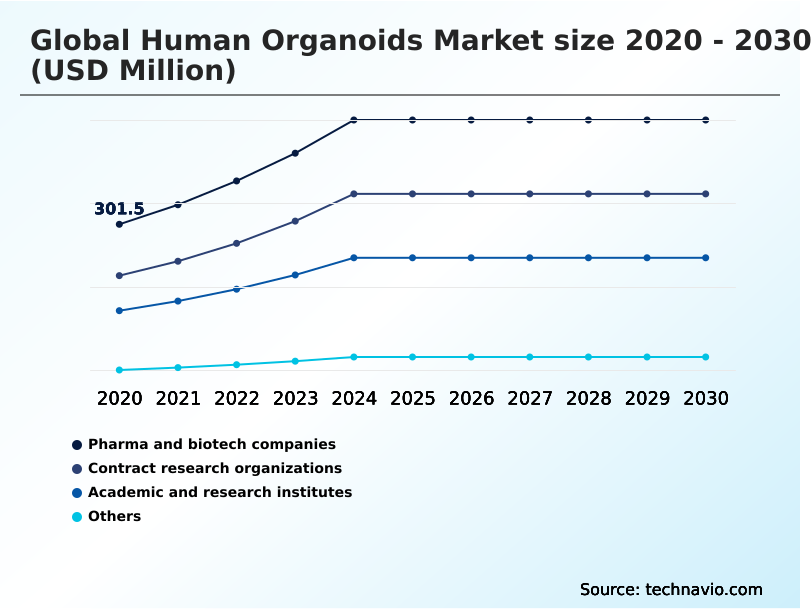
The pharma and biotech companies segment is estimated to witness significant growth during the forecast period.

The pharmaceutical and biotechnology segment of the Human Organoids landscape focuses on accelerating early-stage therapeutic development and reducing late-stage clinical failures. Organizations increasingly integrate disease modeling platforms to improve the physiological relevance of their preclinical testing frameworks.

By leveraging advanced stem cell differentiation and mapping complex tissue morphogenesis, these end-users generate highly predictive data earlier in the research pipeline.

This transition from traditional in vitro testing to human-relevant biological models has improved drug screening efficiency by 22% while accelerating biomarker identification processes. Consequently, organizations achieve a 15% reduction in false-positive therapeutic candidates during translational oncology validation.

These enhanced predictive capabilities directly optimize resource allocation and provide superior clinical decision support, driving structural improvements in how pharmaceutical entities evaluate toxicity, target engagement, and overall therapeutic efficacy prior to human trials.
Get Free Sample

The Pharma and biotech companies segment was valued at USD 488.4 million in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 39.8% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
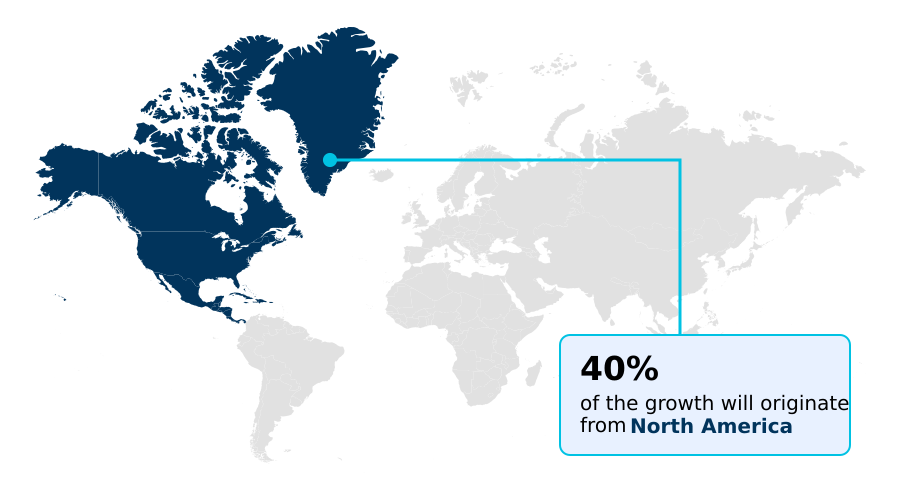
See How Human Organoids Market Demand is Rising in North America Get Free Sample

The geographic landscape of the Human Organoids reveals distinct structural disparities driven by localized infrastructure investments and regulatory frameworks.

North America currently exhibits a 24% higher adoption rate of microphysiological systems compared to Europe, largely fueled by aggressive integration of high content imaging systems across robust pharmaceutical networks.

This regional advantage allows North American biomedical facilities to enhance preclinical research productivity and optimize large scale testing infrastructures more rapidly.

Conversely, Europe is advancing biological complexity replication through strong academic-industry partnerships and stringent regulatory standards prioritizing alternatives to animal testing, yielding a 16% improvement in cross-laboratory experimental reproducibility.

Both regions are heavily leveraging laboratory automation capabilities to mitigate the operational burdens associated with complex tissue cultivation.

By transitioning toward standardized organoid biobanking and automated workflows, organizations across these leading geographies are fundamentally improving translational medicine outcomes, reducing late-stage clinical failures, and establishing higher benchmarks for precision healthcare applications.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The evolution of the Human Organoids reflects a critical shift from basic cellular research to highly integrated industrial applications. Pharmaceutical enterprises are heavily investing in predictive human tissue disease models to minimize the inherent risks of clinical development, seeking biological environments that closely mimic actual physiological responses.
  • By incorporating patient derived tumor organoid assays, oncology researchers can evaluate individual therapeutic sensitivities with exceptional accuracy, offering a stark contrast to the generalized assumptions historically tied to animal testing. Operations utilizing these advanced models report a nearly 30% greater success rate in identifying viable therapeutic candidates during early phase screening compared to traditional methodologies.
  • To support this expanding demand, the industry is increasingly focused on establishing scalable stem cell organoid production. This transition requires sophisticated supply chain coordination for specialized media, reagents, and bioengineering equipment. Furthermore, the deployment of automated high throughput organoid screening is transforming laboratory economics by drastically lowering the margin of human error and optimizing workflow processing speeds.
  • As these technologies mature, healthcare institutions are actively transitioning toward physiologically relevant personalized medicine platforms, enabling clinicians to make data-driven treatment decisions tailored to individual genetic profiles. This fundamental realignment in research methodology not only improves operational efficiency but also ensures stricter alignment with emerging global compliance mandates that advocate for the reduction of conventional animal-based testing paradigms.
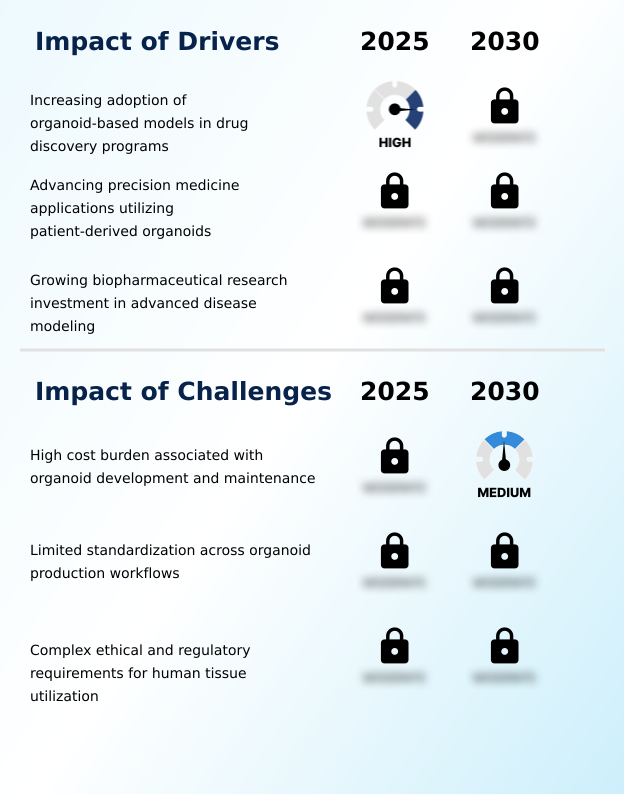
What are the key market drivers leading to the rise in the adoption of Human Organoids Industry?

  • The increasing adoption of advanced organoid-based models within drug discovery programs serves as a primary catalyst accelerating overall market expansion.

  • The increasing necessity for highly accurate therapeutic response evaluation is acting as a primary catalyst for the widespread adoption of patient derived organoids within modern drug development.
  • Pharmaceutical organizations are abandoning conventional two-dimensional cell lines in favor of structurally complex three dimensional tissue models that accurately mirror human disease pathology.
  • This behavioral shift is driven by the urgent need to mitigate the high failure rates associated with traditional animal testing.
  • Consequently, laboratories utilizing human relevant preclinical platforms have increased early-stage compound screening accuracy by 28% and accelerated target validation workflows by nearly 20%.
  • By incorporating these sophisticated biological systems, healthcare institutions are successfully expanding precision medicine applications, allowing clinicians to optimize individualized treatment regimens while substantially reducing the operational costs tied to ineffective therapeutic interventions.

What are the market trends shaping the Human Organoids Industry?

  • The expanding integration of AI-enabled analytics within research workflows represents a defining trend in the industry. This technological shift automates complex data interpretation and enhances the overall efficiency of high-throughput experimental processes.

  • The adoption of multi organ configurations is fundamentally reshaping biomedical research workflows by bridging the critical gap between isolated cellular studies and full systemic physiological modeling. Driven by the need to understand complex drug interactions across different tissues, laboratories are rapidly transitioning toward interconnected biological systems.
  • This structural shift is largely enabled by advanced fluidics integration, which allows researchers to simulate blood flow and systemic nutrient exchange with unprecedented accuracy. By replicating these dynamic environments, organizations have improved their predictive toxicity detection capabilities by 32% compared to traditional single-organ models.
  • Furthermore, the incorporation of predictive data processing facilitates real-time cellular behavior analysis, resulting in a 25% reduction in data interpretation delays. These technological innovations directly lower the risk of late-stage clinical failures by providing pharmaceutical developers with highly reliable, human-relevant insights much earlier in the product development lifecycle.

What challenges does the Human Organoids Industry face during its growth?

  • The substantial financial burden associated with the development, infrastructure, and ongoing maintenance of sophisticated organoid platforms remains a significant challenge restricting broader industry implementation.

  • The structural complexity of maintaining stable human tissue models poses severe operational constraints across the biopharmaceutical sector. Researchers face substantial difficulties in standardizing extracellular matrix technologies, which are highly susceptible to batch-to-batch variability and biological degradation. Because induced pluripotent stem cells require highly specific environmental conditions to differentiate accurately, laboratories must navigate extremely delicate and long term cultivation cycles.
  • These demanding requirements increase baseline laboratory maintenance costs by approximately 35% compared to standard in vitro methods, significantly straining research budgets. Additionally, the challenge of achieving consistent experimental reproducibility enhancement within these complex biological environments results in a 15% delay in project timelines due to mandatory validation reruns.
  • These technical and financial barriers heavily restrict scalability, complicating the broader integration of organoid systems into high throughput regenerative medicine research and commercial drug screening operations.

Exclusive Technavio Analysis on Customer Landscape

The human organoids market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the human organoids market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
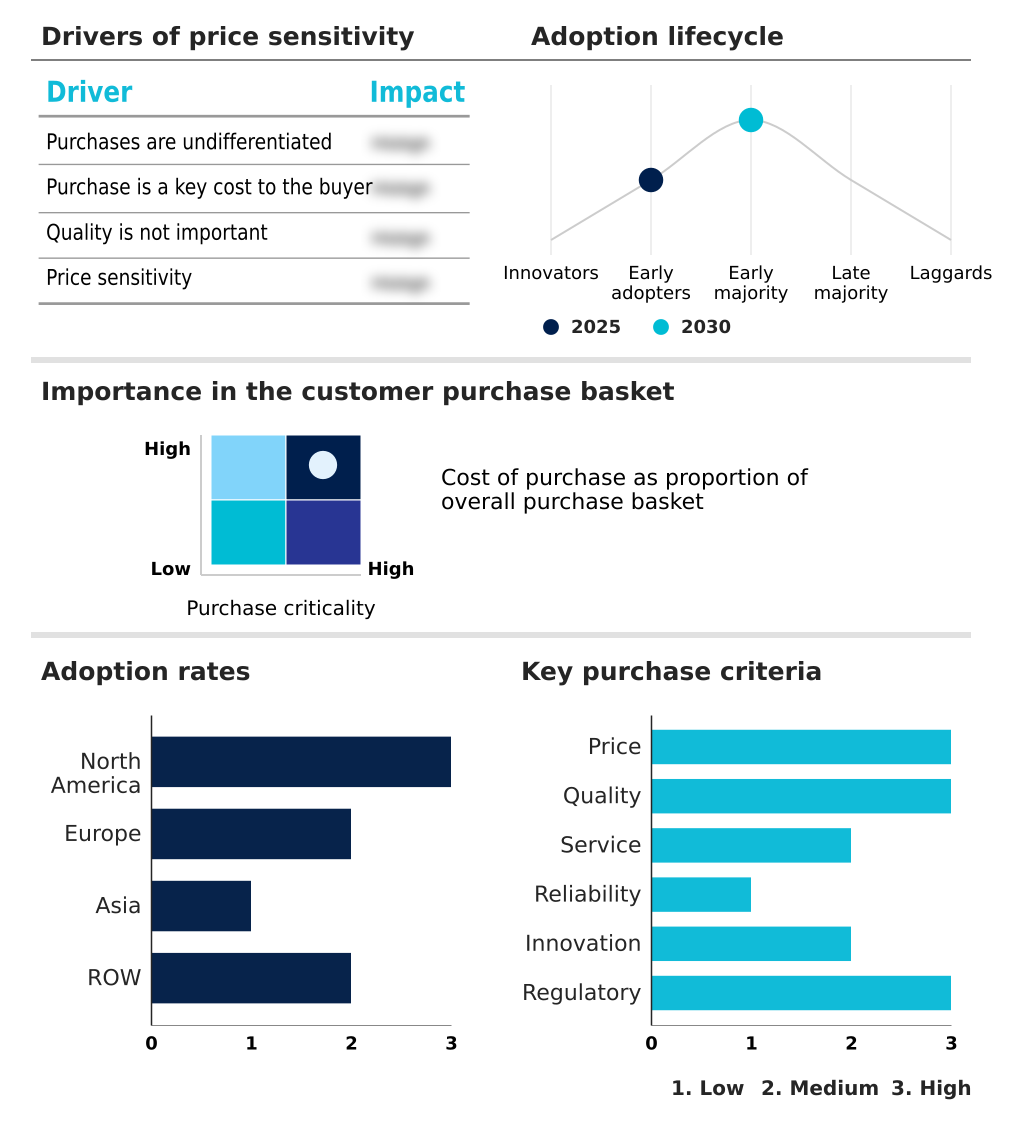
Customer Landscape of Human Organoids Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, human organoids market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

3DNamics Inc. - Comprehensive offerings include pluripotent stem cell-derived three-dimensional tissue models and motorized bioreactor platforms designed to facilitate neurological disorder research and enhance preclinical drug screening capabilities.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • 3DNamics Inc.
  • ACROBiosystems Co. Ltd.
  • BICO Group AB
  • BioIVT LLC
  • CN Bio Innovations Ltd.
  • Corning Inc.
  • Cypre Inc.
  • Emulate Inc.
  • InSphero AG
  • Kirkstall Ltd.
  • MIMETAS BV
  • Molecular Device LLC
  • Neuromics Inc.
  • Pandorum Technologies Pvt. Ltd.
  • Sigma Aldrich Chemicals Ltd.
  • Sino Biological Inc.
  • STEMCELL Technologies Inc.
  • The Organoid Co
  • Thermo Fisher Scientific Inc.
  • ZenBio Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Human organoids market

  • In the Biotechnology industry, the transition toward human relevant preclinical platforms for predictive toxicology testing has directly increased demand for Human Organoids by requiring biologically representative tissues that reduce reliance on conventional animal models.
  • Regulatory shifts emphasizing precision medicine applications have prompted pharmaceutical developers to adopt standardized experimental workflows, accelerating the integration of three-dimensional cellular systems for individualized therapeutic evaluation and oncology screening.
  • Advancements in laboratory automation capabilities and high throughput screening technologies have optimized large scale testing infrastructures, improving the scalability of complex tissue culture processes and lowering operational bottlenecks within the Human Organoids landscape.
  • The commercial expansion of microphysiological systems featuring advanced fluidics integration has enhanced cellular behavior analysis, enabling researchers to maintain complex biological environments over extended cultivation periods and driving greater adoption of interconnected tissue models.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Human Organoids Market insights. See full methodology.

Market Scope
Page number 299
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 16.7%
Market growth 2026-2030 USD 1551.3 million
Market structure Fragmented
YoY growth 2025-2026(%) 15.9%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Indonesia, Thailand, Brazil, Saudi Arabia, UAE, Turkey, South Africa, Argentina, Colombia and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The commercial trajectory of the Human Organoids is being defined by a rapid transition from exploratory academic research to standardized industrial deployment. Organizations are prioritizing organoid biobanking to secure diverse, patient-specific biological assets essential for advancing precision medicine and complex therapeutic development.
  • The strategic integration of automated cell culture platforms allows research facilities to dramatically reduce operational bottlenecks, achieving a 40% improvement in batch consistency compared to manual handling techniques. This scalability is further supported by the widespread adoption of synthetic hydrogel matrices and specialized recombinant growth factors, which eliminate lot-to-lot variability and ensure highly controlled experimental environments.
  • As pharmaceutical leaders focus on optimizing product strategy and reducing clinical attrition, genomic sequencing integration with three-dimensional tissue models has become critical for robust target discovery. Furthermore, extensive reliance on translational oncology validation ensures that early-stage drug candidates are evaluated against structurally accurate biological systems before entering trials.
  • The growing availability of customized research services enables smaller biotechnology firms to leverage these sophisticated capabilities, accelerating biomedical innovation across the entire life sciences ecosystem.

What are the Key Data Covered in this Human Organoids Market Research and Growth Report?

  • What is the expected growth of the Human Organoids Market between 2026 and 2030?

    • USD 1.55 billion, at a CAGR of 16.7%

  • What segmentation does the market report cover?

    • The report is segmented by End-user (Pharma and biotech companies, Contract research organizations, Academic and research institutes, and Others), Source (Adult stem cells, iPSCs, ESCs, and Others), Product (Organoid models, Media and supplements, and Reagents) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Increasing adoption of organoid-based models in drug discovery programs, High cost burden associated with organoid development and maintenance

  • Who are the major players in the Human Organoids Market?

    • 3DNamics Inc., ACROBiosystems Co. Ltd., BICO Group AB, BioIVT LLC, CN Bio Innovations Ltd., Corning Inc., Cypre Inc., Emulate Inc., InSphero AG, Kirkstall Ltd., MIMETAS BV, Molecular Device LLC, Neuromics Inc., Pandorum Technologies Pvt. Ltd., Sigma Aldrich Chemicals Ltd., Sino Biological Inc., STEMCELL Technologies Inc., The Organoid Co, Thermo Fisher Scientific Inc. and ZenBio Inc.

Market Research Insights

  • The Human Organoids Market is fundamentally restructuring drug discovery workflows by providing biologically accurate human tissue models that bridge the gap between in vitro testing and clinical trials. Organizations integrating these advanced platforms have achieved a 28% improvement in identifying toxicological risks early in the development cycle, significantly reducing downstream failure rates.
  • Furthermore, the adoption of patient-derived models for personalized treatment strategies has accelerated clinical screening times by 15% compared to traditional cell lines. These platforms enhance biomarker identification processes by enabling researchers to observe physiological responses within highly controlled environments.
  • By optimizing target validation efforts through scalable and reproducible tissue modeling, pharmaceutical entities are streamlining operational efficiencies and maximizing the return on investment for complex therapeutic programs.

We can help! Our analysts can customize this human organoids market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Source
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Human Organoids Market 2020 - 2024

Historic Market Size - Data Table on Global Human Organoids Market 2020 - 2024 ($ million)

5.2 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.3 Source segment analysis 2020 - 2024

Historic Market Size - Source Segment 2020 - 2024 ($ million)

5.4 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global human organoids market

6.2 Impact of geopolitical conflicts on global human organoids market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by End-user

8.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

8.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

8.3 Pharma and biotech companies - Market size and forecast 2025-2030

Chart on Pharma and biotech companies - Market size and forecast 2025-2030 ($ million)
Data Table on Pharma and biotech companies - Market size and forecast 2025-2030 ($ million)
Chart on Pharma and biotech companies - Year-over-year growth 2025-2030 (%)
Data Table on Pharma and biotech companies - Year-over-year growth 2025-2030 (%)

8.4 Contract research organizations - Market size and forecast 2025-2030

Chart on Contract research organizations - Market size and forecast 2025-2030 ($ million)
Data Table on Contract research organizations - Market size and forecast 2025-2030 ($ million)
Chart on Contract research organizations - Year-over-year growth 2025-2030 (%)
Data Table on Contract research organizations - Year-over-year growth 2025-2030 (%)

8.5 Academic and research institutes - Market size and forecast 2025-2030

Chart on Academic and research institutes - Market size and forecast 2025-2030 ($ million)
Data Table on Academic and research institutes - Market size and forecast 2025-2030 ($ million)
Chart on Academic and research institutes - Year-over-year growth 2025-2030 (%)
Data Table on Academic and research institutes - Year-over-year growth 2025-2030 (%)

8.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.7 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

9. Market Segmentation by Source

9.1 Market segments

Chart on Source - Market share 2025-2030 (%)
Data Table on Source - Market share 2025-2030 (%)

9.2 Comparison by Source

Chart on Comparison by Source
Data Table on Comparison by Source

9.3 Adult stem cells - Market size and forecast 2025-2030

Chart on Adult stem cells - Market size and forecast 2025-2030 ($ million)
Data Table on Adult stem cells - Market size and forecast 2025-2030 ($ million)
Chart on Adult stem cells - Year-over-year growth 2025-2030 (%)
Data Table on Adult stem cells - Year-over-year growth 2025-2030 (%)

9.4 iPSCs - Market size and forecast 2025-2030

Chart on iPSCs - Market size and forecast 2025-2030 ($ million)
Data Table on iPSCs - Market size and forecast 2025-2030 ($ million)
Chart on iPSCs - Year-over-year growth 2025-2030 (%)
Data Table on iPSCs - Year-over-year growth 2025-2030 (%)

9.5 ESCs - Market size and forecast 2025-2030

Chart on ESCs - Market size and forecast 2025-2030 ($ million)
Data Table on ESCs - Market size and forecast 2025-2030 ($ million)
Chart on ESCs - Year-over-year growth 2025-2030 (%)
Data Table on ESCs - Year-over-year growth 2025-2030 (%)

9.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.7 Market opportunity by Source

Market opportunity by Source ($ million)
Data Table on Market opportunity by Source ($ million)

10. Market Segmentation by Product

10.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

10.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

10.3 Organoid models - Market size and forecast 2025-2030

Chart on Organoid models - Market size and forecast 2025-2030 ($ million)
Data Table on Organoid models - Market size and forecast 2025-2030 ($ million)
Chart on Organoid models - Year-over-year growth 2025-2030 (%)
Data Table on Organoid models - Year-over-year growth 2025-2030 (%)

10.4 Media and supplements - Market size and forecast 2025-2030

Chart on Media and supplements - Market size and forecast 2025-2030 ($ million)
Data Table on Media and supplements - Market size and forecast 2025-2030 ($ million)
Chart on Media and supplements - Year-over-year growth 2025-2030 (%)
Data Table on Media and supplements - Year-over-year growth 2025-2030 (%)

10.5 Reagents - Market size and forecast 2025-2030

Chart on Reagents - Market size and forecast 2025-2030 ($ million)
Data Table on Reagents - Market size and forecast 2025-2030 ($ million)
Chart on Reagents - Year-over-year growth 2025-2030 (%)
Data Table on Reagents - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5.6 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ million)
Data Table on Thailand - Market size and forecast 2025-2030 ($ million)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.3 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.5 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.6 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.7 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Increasing adoption of organoid-based models in drug discovery programs
Advancing precision medicine applications utilizing patient-derived organoids
Growing biopharmaceutical research investment in advanced disease modeling

13.2 Market challenges

High cost burden associated with organoid development and maintenance
Limited standardization across organoid production workflows
Complex ethical and regulatory requirements for human tissue utilization

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Expanding integration of AI-enabled analytics in organoid research workflows
Evolving multi-organoid platforms for cross-tissue biological investigations
Growing collaboration between academic institutions and biotechnology companies for organoid commercialization

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 ACROBiosystems Co. Ltd.

ACROBiosystems Co. Ltd. - Overview
ACROBiosystems Co. Ltd. - Product / Service
ACROBiosystems Co. Ltd. - Key offerings
SWOT

15.5 BICO Group AB

BICO Group AB - Overview
BICO Group AB - Business segments
BICO Group AB - Key offerings
BICO Group AB - Segment focus
SWOT

15.6 BioIVT LLC

BioIVT LLC - Overview
BioIVT LLC - Product / Service
BioIVT LLC - Key offerings
SWOT

15.7 Corning Inc.

Corning Inc. - Overview
Corning Inc. - Business segments
Corning Inc. - Key offerings
Corning Inc. - Segment focus
SWOT

15.8 Cypre Inc.

Cypre Inc. - Overview
Cypre Inc. - Product / Service
Cypre Inc. - Key offerings
SWOT

15.9 Emulate Inc.

Emulate Inc. - Overview
Emulate Inc. - Product / Service
Emulate Inc. - Key offerings
SWOT

15.10 InSphero AG

InSphero AG - Overview
InSphero AG - Product / Service
InSphero AG - Key offerings
SWOT

15.11 MIMETAS BV

MIMETAS BV - Overview
MIMETAS BV - Product / Service
MIMETAS BV - Key offerings
SWOT

15.12 Molecular Device LLC

Molecular Device LLC - Overview
Molecular Device LLC - Product / Service
Molecular Device LLC - Key offerings
SWOT

15.13 Pandorum Technologies Pvt. Ltd.

Pandorum Technologies Pvt. Ltd. - Overview
Pandorum Technologies Pvt. Ltd. - Product / Service
Pandorum Technologies Pvt. Ltd. - Key offerings
SWOT

15.14 Sigma Aldrich Chemicals Ltd.

Sigma Aldrich Chemicals Ltd. - Overview
Sigma Aldrich Chemicals Ltd. - Product / Service
Sigma Aldrich Chemicals Ltd. - Key offerings
SWOT

15.15 Sino Biological Inc.

Sino Biological Inc. - Overview
Sino Biological Inc. - Product / Service
Sino Biological Inc. - Key offerings
SWOT

15.16 STEMCELL Technologies Inc.

STEMCELL Technologies Inc. - Overview
STEMCELL Technologies Inc. - Product / Service
STEMCELL Technologies Inc. - Key offerings
SWOT

15.17 Thermo Fisher Scientific Inc.

Thermo Fisher Scientific Inc. - Overview
Thermo Fisher Scientific Inc. - Business segments
Thermo Fisher Scientific Inc. - Key news
Thermo Fisher Scientific Inc. - Key offerings
Thermo Fisher Scientific Inc. - Segment focus
SWOT

15.18 ZenBio Inc.

ZenBio Inc. - Overview
ZenBio Inc. - Product / Service
ZenBio Inc. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Human Organoids market growth will increase by USD 1551.3 million during 2026-2030.

The Human Organoids market is expected to grow at a CAGR of 16.7% during 2026-2030.

Human Organoids market is segmented by End-user (Pharma and biotech companies, Contract research organizations, Academic and research institutes, Others) Source (Adult stem cells, iPSCs, ESCs, Others) Product (Organoid models, Media and supplements, Reagents)

3DNamics Inc., ACROBiosystems Co. Ltd., BICO Group AB, BioIVT LLC, CN Bio Innovations Ltd., Corning Inc., Cypre Inc., Emulate Inc., InSphero AG, Kirkstall Ltd., MIMETAS BV, Molecular Device LLC, Neuromics Inc., Pandorum Technologies Pvt. Ltd., Sigma Aldrich Chemicals Ltd., Sino Biological Inc., STEMCELL Technologies Inc., The Organoid Co, Thermo Fisher Scientific Inc., ZenBio Inc. are a few of the key vendors in the Human Organoids market.

North America will register the highest growth rate of 39.8% among the other regions. Therefore, the Human Organoids market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Indonesia, Thailand, Brazil, Saudi Arabia, UAE, Turkey, South Africa, Argentina, Colombia, Israel

  • Increasing adoption of organoid-based models in drug discovery programs is the driving factor this market.

The Human Organoids market vendors should focus on grabbing business opportunities from the End-user segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
