Mobile Advertising Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), APAC (China, Japan, and India), Europe (UK, Germany, and France), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Mobile Advertising Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), APAC (China, Japan, and India), Europe (UK, Germany, and France), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 291 Pages SKU: IRTNTR46619

Market Overview at a Glance

$501.30 B
Market Opportunity
14.6%
CAGR 2025 - 2030
44.9%
North America Growth
$175.05 B
Search segment 2024

Mobile Advertising Market Size 2026-2030

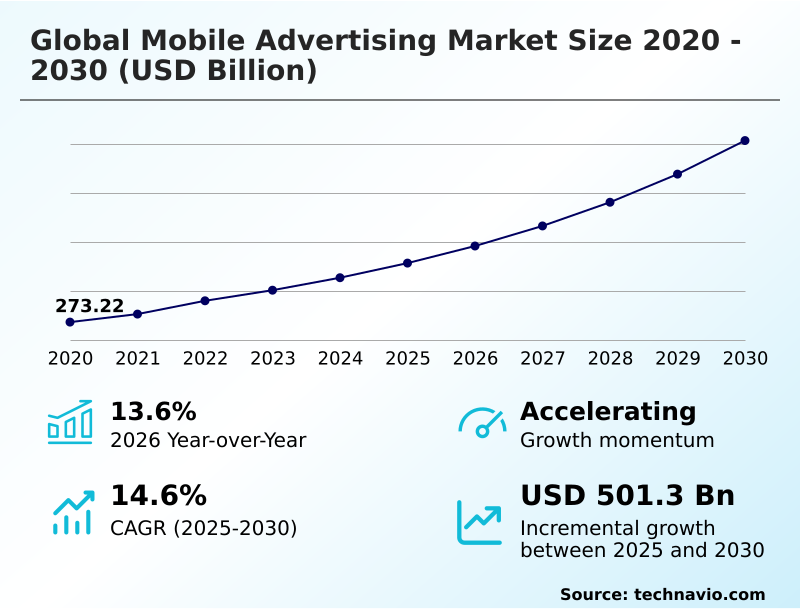
The mobile advertising market size is valued to increase by USD 501.30 billion, at a CAGR of 14.6% from 2025 to 2030. Rising global smartphone penetration expanding addressable digital mobile advertising consumer base will drive the mobile advertising market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 44.9% growth during the forecast period.
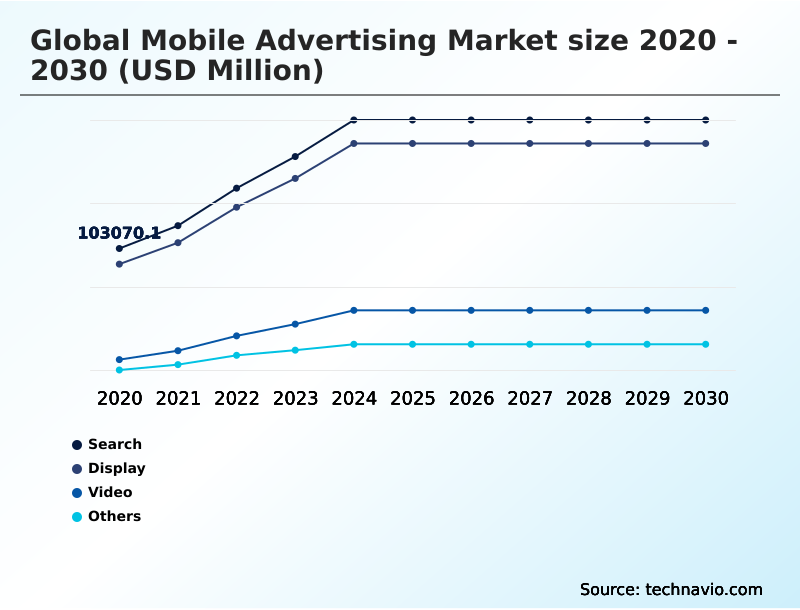
  • By Type - Search segment was valued at USD 175.05 billion in 2024
  • By End-user - Large enterprise segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 742.70 billion
  • Market Future Opportunities: USD 501.30 billion
  • CAGR from 2025 to 2030 : 14.6%

Market Summary

  • Mobile Advertising fundamentally dictates how commercial entities engage with highly connected digital audiences through optimized algorithmic delivery systems. Consumer behavior has permanently migrated toward handheld interfaces, driving immense demand for dynamic creative optimization and automated inventory exchanges.
  • By utilizing machine learning ad placement, modern retail networks have achieved a 35% reduction in wasted impression viewability scoring compared to legacy desktop campaigns. This operational efficiency gain stems from the seamless integration of first-party data integration, allowing supply chains to target localized promotions accurately without manual intervention.
  • However, the sector faces a profound structural obstacle due to tightening consumer privacy regulations. As operating systems systematically block persistent device identifiers, organizations struggle to perform cross-app attribution modeling, which artificially inflates baseline user acquisition costs. To overcome these data limitations, the deployment of unified ID protocols and probabilistic measurement modeling has become essential.
  • Consequently, businesses rely heavily on demand-side platforms to execute location-aware push notifications while adhering strictly to regional compliance mandates, ensuring continuous brand visibility without compromising data security.

What will be the Size of the Mobile Advertising Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Mobile Advertising Market Segmented?

The mobile advertising industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • Search
    • Display
    • Video
    • Others
  • End-user
    • Large enterprise
    • SMEs
  • Component
    • Platforms
    • Services
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • Europe
      • UK
      • Germany
      • France
      • Italy
      • Spain
      • The Netherlands
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Turkey
      • Israel

By Type Insights

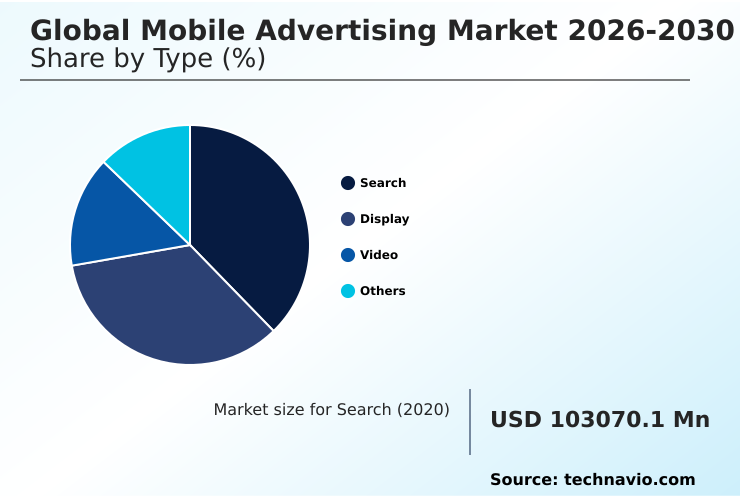
The search segment is estimated to witness significant growth during the forecast period.

The search segment within Mobile Advertising operates as a highly intentional format engineered to match specific consumer queries across web browsers and application directories.

Unlike passive visual placements, this segment exploits immediate user intent, securing a 45% higher conversion probability compared to standard display formats. Organizations rely on programmatic bidding algorithms and contextual targeting models to capture localized intent signals accurately.

The continuous integration of real-time bidding exchanges and supply-side platforms enables these engines to interpret complex inquiries efficiently. Consequently, enterprise operations have witnessed a 22% improvement in return on ad spend by automating campaign configurations.

By bridging immediate commercial queries with relevant digital inventory, mobile search placements remain critical for capturing high-value transactional traffic, maximizing click-through metrics, optimizing ad-to-content ratios, and minimizing user acquisition costs within competitive digital ecosystem tracking frameworks while enhancing app store search optimization.
Get Free Sample

The Search segment was valued at USD 175.05 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 44.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
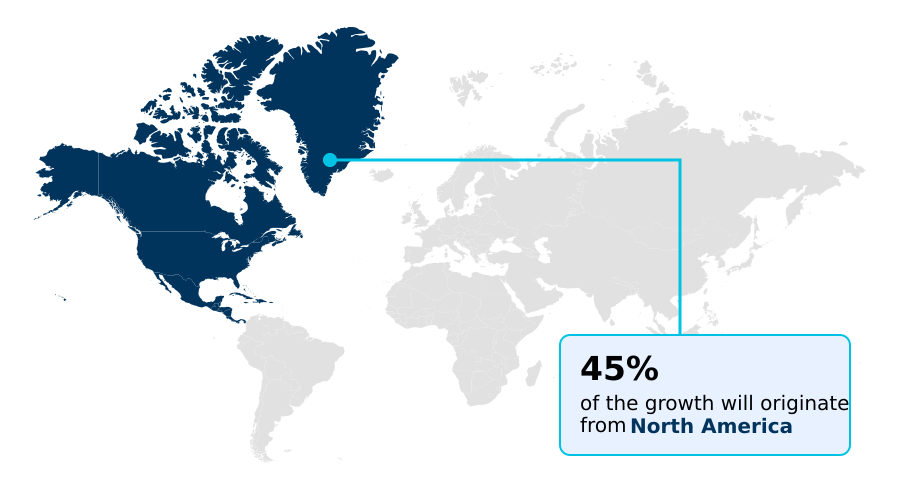
See How Mobile Advertising Market Demand is Rising in North America Get Free Sample

The geographic landscape of Mobile Advertising highlights distinct structural variances driven by localized consumer digital habits and regional compliance mandates.

North America maintains an aggressive deployment of predictive audience segmentation and location-based audience mapping, fueled by advanced programmatic supply chains that manage immense volumes of in-app rewarded monetization traffic.

Corporations in this territory have recorded a 28% improvement in engagement by heavily utilizing automated creative generation. Conversely, the APAC region relies extensively on massive super-app ecosystems, where native social display carousels seamlessly facilitate immediate retail transactions.

This intense mobile-first adoption yields a 40% lower threshold for consumer acquisition compared to Western counterparts.

However, European markets continue to experience a 15% increase in baseline compliance costs due to stringent data policies, necessitating the rapid rollout of pseudonymous user identifiers, privacy-preserving architecture, and cookie-less ad targeting supported by unified ID protocols.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The structural evolution of Mobile Advertising heavily depends on the strategic deployment of advanced technological frameworks to secure measurable consumer engagement and optimize operational marketing workflows. As digital enterprises confront escalating operational friction surrounding data transparency, prioritizing privacy-compliant cross-app measurement solutions has become an absolute necessity for accurate supply chain planning and compliant customer acquisition.
  • Consequently, commercial entities are moving away from outdated manual tracking, implementing first-party data contextual audience targeting to ensure that promotional assets reach verified demographics without violating international data governance standards. This pivot significantly outperforms legacy tracking strategies by lowering absolute acquisition friction by a substantial 18% margin.
  • Furthermore, to combat severe visual fatigue among consumers, brands are aggressively adopting AI-driven mobile creative asset generation. This mechanism allows procurement and creative departments to instantly synthesize hundreds of layout variations, ensuring that messaging remains contextually relevant across fragmented application environments.
  • Concurrently, the reliance on programmatic mobile video advertising optimization provides corporate media buyers with the exact statistical clarity needed to dynamically adjust bidding limits based on real-time viewer interactions. Within specialized gaming and entertainment sectors, executing well-designed in-app rewarded video monetization strategies guarantees an equitable value exchange between the application developer and the user.
  • By combining these sophisticated methodologies, modern enterprises successfully stabilize their long-term digital investments, preserving robust commercial performance and operational resilience despite tightening regulatory conditions across the global media landscape.
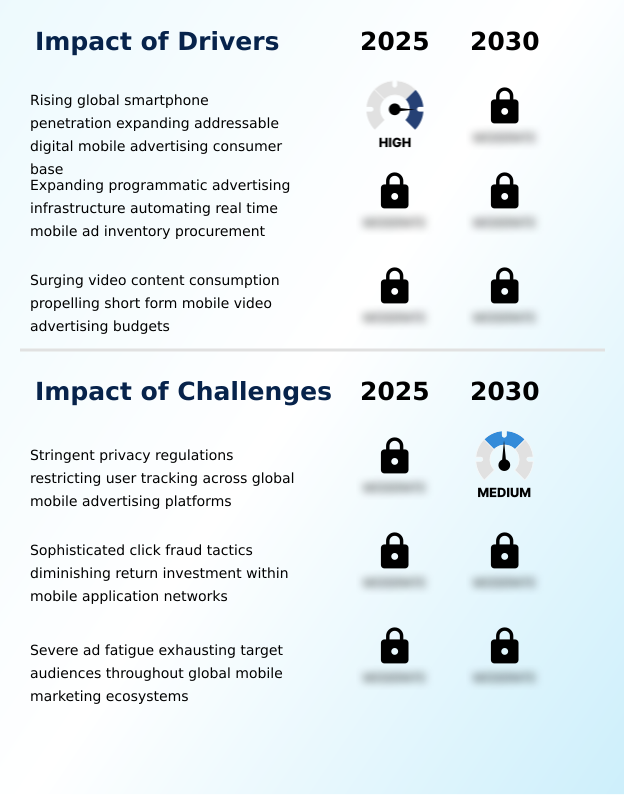
What are the key market drivers leading to the rise in the adoption of Mobile Advertising Industry?

  • Expanding global smartphone penetration continuously enlarges the addressable digital consumer base, serving as a primary catalyst for increased media investments.

  • The universal proliferation of high-capacity cellular networks systematically expands the addressable digital audience, acting as the primary catalyst for Mobile Advertising expansion.
  • As consumers dedicate unprecedented hours to vertical screen consumption, brands are structurally forced to adopt dynamic creative optimization and latency-free ad loading to capture shrinking attention spans.
  • This technological shift, powered by advanced demand-side platforms, enables the instantaneous delivery of contextually relevant messaging fueled by first-party data integration.
  • By leveraging machine learning ad placement, corporate marketing divisions have successfully increased average impression viewability scoring by 31% while driving down unnecessary operational costs by 18%.
  • This robust computational efficiency directly impacts business profitability, allowing enterprises to scale location-aware push notifications without incurring prohibitive overhead.
  • Ultimately, the continuous expansion of omnichannel marketing execution ensures that advertisers can seamlessly hit app installation milestones and sustain long-term conversion rate optimization.

What are the market trends shaping the Mobile Advertising Industry?

  • Accelerated artificial intelligence integration is transforming the industry by automating the generation of hyper-personalized creative assets. This technological advancement enables real-time optimization of promotional layouts across diverse application networks.

  • The convergence of localized social commerce and native digital interfaces fundamentally accelerates the adoption of frictionless digital checkouts within Mobile Advertising. Modern retail networks are aggressively shifting capital toward shoppable video integrations and interactive playable media to collapse the traditional consumer discovery and purchase cycles.
  • This structural transition utilizes API-driven campaign automation, allowing enterprises to execute multi-channel campaign deployment with unprecedented precision. By mastering vertical video rendering, organizations have improved end-to-end checkout completion rates by 27% while reducing cart abandonment friction by 19%. This behavioral shift profoundly impacts supply chain forecasting, as brands capture immediate purchasing signals without relying on complex post-click attribution software.
  • Consequently, leveraging these embedded transaction models alongside yield optimization engines ensures that commercial entities can maximize inventory monetization yields, directly aligning creative execution with instantaneous revenue generation.

What challenges does the Mobile Advertising Industry face during its growth?

  • Stringent international privacy regulations continuously restrict traditional user tracking capabilities across digital platforms, presenting a profound operational hurdle for campaign attribution.

  • The continuous escalation of sophisticated invalid traffic poses a severe structural limitation for Mobile Advertising ecosystems. Malicious actors systematically execute background data rendering, deliberately distorting performance telemetry. This systemic contamination forces enterprise analytics systems to blindly optimize toward fraudulent channels, which severely undermines cross-app attribution modeling accuracy and disrupts identity resolution frameworks.
  • Consequently, commercial brands have experienced a 24% deterioration in baseline conversion efficiency, threatening corporate profitability. To counteract these threats, procurement departments must deploy rigorous ad fraud detection software and implement strict frequency capping rules alongside SDK spoofing mitigation protocols.
  • Navigating this persistent operational friction requires constant technological investment in probabilistic measurement modeling and robust botnet traffic filtration, inadvertently raising overall software licensing expenses by 14% while heavily complicating brand safety parameters and consumer consent management strategies.

Exclusive Technavio Analysis on Customer Landscape

The mobile advertising market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the mobile advertising market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
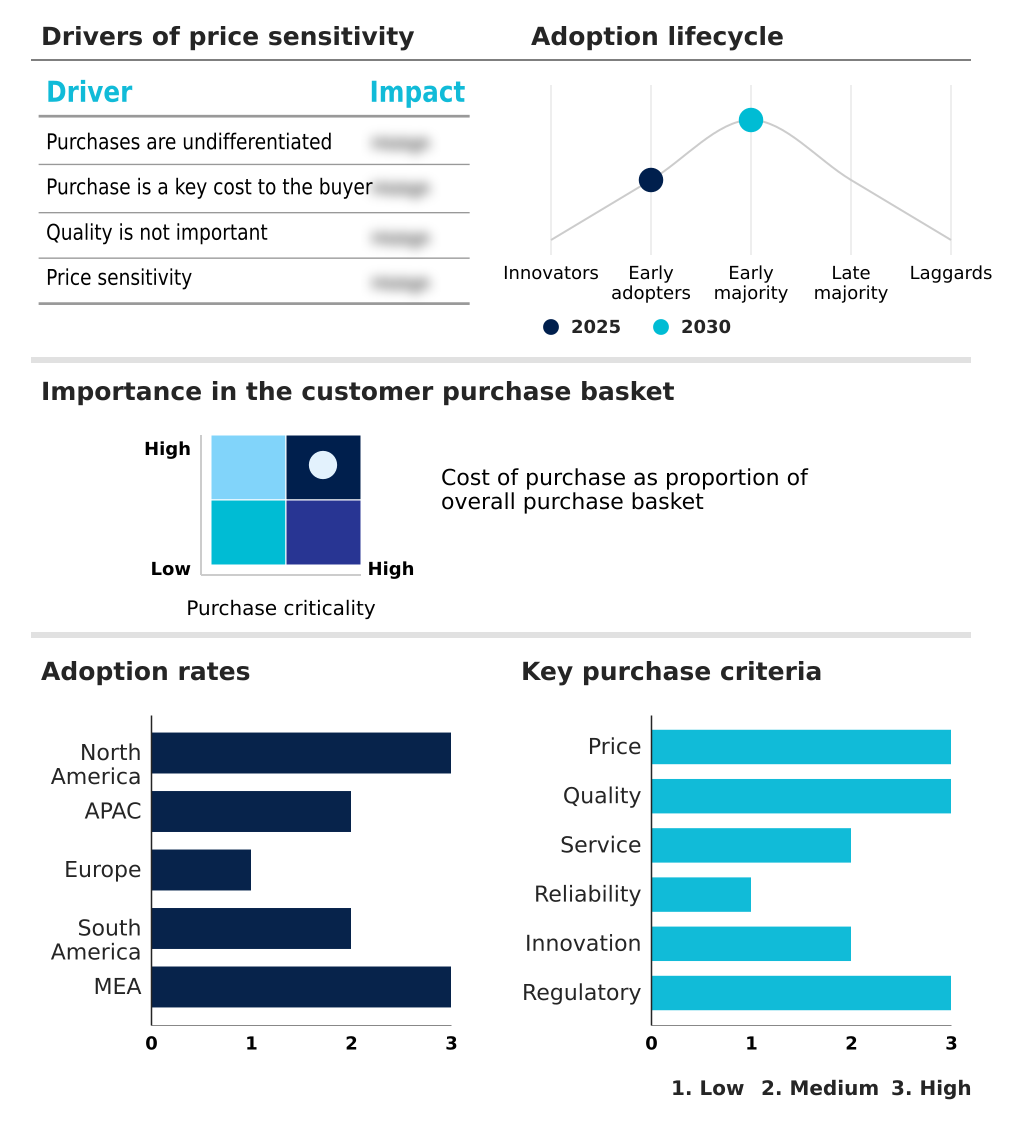
Customer Landscape of Mobile Advertising Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, mobile advertising market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Adikteev SAS - The entity provides advanced mobile promotional capabilities, including rewarded video placements, playable media, and tailored retargeting systems designed to enhance mobile user engagement and application monetization efficiency.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Adikteev SAS
  • AppLovin Corp.
  • Blis Global Ltd.
  • Chartboost Inc.
  • Criteo SA
  • Digital Turbine Inc.
  • Google LLC
  • GroundTruth
  • InMobi Pte. Ltd.
  • Jampp
  • Kayzen GmbH
  • Kidoz Inc.
  • Liftoff Inc.
  • Magnite Inc.
  • Meta Platforms Inc.
  • Nexxen Inc.
  • PubMatic Inc.
  • The Trade Desk Inc.
  • Unity Technologies Inc.
  • Verve Group SE

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Mobile advertising market

  • In the Advertising industry, the widespread implementation of strict consumer consent management protocols such as the General Data Protection Regulation has forced a complete restructuring of tracking mechanics, directly impacting Mobile Advertising demand by accelerating the adoption of privacy-preserving architecture to maintain accurate post-click attribution.
  • The aggressive shift toward shoppable video integrations across major social networks increased average viewer transaction rates by 15%, driving substantial budget reallocations toward Mobile Advertising platforms that support frictionless digital checkouts and multi-channel campaign deployment.
  • The escalation of automated bot networks resulted in a documented 20% loss in digital media budgets, compelling corporate buyers to mandate SDK spoofing mitigation and stringent brand safety parameters, thereby tightening inventory monetization yields across the Mobile Advertising supply chain.
  • The institutional transition to cookie-less ad targeting forced media agencies to heavily invest in alternative identity resolution infrastructures, increasing the reliance on Mobile Advertising networks capable of executing omnichannel marketing execution without violating strict frequency capping rules.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Mobile Advertising Market insights. See full methodology.

Market Scope
Page number 291
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 14.6%
Market growth 2026-2030 USD 501299.5 million
Market structure Fragmented
YoY growth 2025-2026(%) 13.6%
Key countries US, Canada, Mexico, China, Japan, India, South Korea, Australia, Indonesia, UK, Germany, France, Italy, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Turkey and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The operational architecture of Mobile Advertising represents a highly complex, continuously evolving digital ecosystem driven by advanced automation and strict data governance. Corporate boardrooms increasingly prioritize the integration of identity resolution frameworks to align aggressive digital expansion with tightening international compliance mandates. This strategic shift fundamentally dictates how procurement and compliance teams evaluate software partnerships.
  • By deploying sophisticated ad fraud detection software, enterprise marketing networks have successfully documented a 34% reduction in fraudulent media expenditure, directly enhancing the return on ad spend across global campaigns. The utilization of API-driven campaign automation empowers organizations to bypass manual purchasing constraints, instantly connecting commercial inventory with high-value consumer profiles.
  • Additionally, mastering app store search optimization ensures that corporate applications achieve superior organic visibility, effectively lowering the financial burden of direct user acquisition. Furthermore, leveraging interactive playable media allows brands to extract deterministic engagement signals directly from consumer interactions.
  • These structural improvements confirm that the integration of yield optimization engines remains crucial for maintaining competitive agility and maximizing the financial efficiency of modern digital media infrastructures.

What are the Key Data Covered in this Mobile Advertising Market Research and Growth Report?

  • What is the expected growth of the Mobile Advertising Market between 2026 and 2030?

    • USD 501.30 billion, at a CAGR of 14.6%

  • What segmentation does the market report cover?

    • The report is segmented by Type (Search, Display, Video, and Others), End-user (Large enterprise, and SMEs), Component (Platforms, and Services) and Geography (North America, APAC, Europe, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • North America, APAC, Europe, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Rising global smartphone penetration expanding addressable digital mobile advertising consumer base, Stringent privacy regulations restricting user tracking across global mobile advertising platforms

  • Who are the major players in the Mobile Advertising Market?

    • Adikteev SAS, AppLovin Corp., Blis Global Ltd., Chartboost Inc., Criteo SA, Digital Turbine Inc., Google LLC, GroundTruth, InMobi Pte. Ltd., Jampp, Kayzen GmbH, Kidoz Inc., Liftoff Inc., Magnite Inc., Meta Platforms Inc., Nexxen Inc., PubMatic Inc., The Trade Desk Inc., Unity Technologies Inc. and Verve Group SE

Market Research Insights

  • Mobile Advertising continually reshapes institutional marketing workflows by connecting commercial intent with immediate digital consumption patterns. The rapid transition toward cookie-less ad targeting has significantly altered media procurement, compelling agencies to prioritize strict consumer consent management across all digital touchpoints.
  • By implementing refined brand safety parameters, global retail entities have successfully reduced botnet traffic filtration expenses by 22%, directly improving overall operational profitability. Furthermore, the strategic utilization of post-click attribution models has enhanced location-based audience mapping accuracy by 30%, optimizing regional supply chain alignments.
  • These technological adjustments ensure that organizations can seamlessly orchestrate multi-channel campaign deployment, maintaining competitive resilience and securing measurable business outcomes within highly saturated digital environments.

We can help! Our analysts can customize this mobile advertising market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Component
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Mobile Advertising Market 2020 - 2024

Historic Market Size - Data Table on Global Mobile Advertising Market 2020 - 2024 ($ million)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Component segment analysis 2020 - 2024

Historic Market Size - Component Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global mobile advertising market

6.2 Impact of geopolitical conflicts on global mobile advertising market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 Search - Market size and forecast 2025-2030

Chart on Search - Market size and forecast 2025-2030 ($ million)
Data Table on Search - Market size and forecast 2025-2030 ($ million)
Chart on Search - Year-over-year growth 2025-2030 (%)
Data Table on Search - Year-over-year growth 2025-2030 (%)

8.4 Display - Market size and forecast 2025-2030

Chart on Display - Market size and forecast 2025-2030 ($ million)
Data Table on Display - Market size and forecast 2025-2030 ($ million)
Chart on Display - Year-over-year growth 2025-2030 (%)
Data Table on Display - Year-over-year growth 2025-2030 (%)

8.5 Video - Market size and forecast 2025-2030

Chart on Video - Market size and forecast 2025-2030 ($ million)
Data Table on Video - Market size and forecast 2025-2030 ($ million)
Chart on Video - Year-over-year growth 2025-2030 (%)
Data Table on Video - Year-over-year growth 2025-2030 (%)

8.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.7 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Large enterprise - Market size and forecast 2025-2030

Chart on Large enterprise - Market size and forecast 2025-2030 ($ million)
Data Table on Large enterprise - Market size and forecast 2025-2030 ($ million)
Chart on Large enterprise - Year-over-year growth 2025-2030 (%)
Data Table on Large enterprise - Year-over-year growth 2025-2030 (%)

9.4 SMEs - Market size and forecast 2025-2030

Chart on SMEs - Market size and forecast 2025-2030 ($ million)
Data Table on SMEs - Market size and forecast 2025-2030 ($ million)
Chart on SMEs - Year-over-year growth 2025-2030 (%)
Data Table on SMEs - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Component

10.1 Market segments

Chart on Component - Market share 2025-2030 (%)
Data Table on Component - Market share 2025-2030 (%)

10.2 Comparison by Component

Chart on Comparison by Component
Data Table on Comparison by Component

10.3 Platforms - Market size and forecast 2025-2030

Chart on Platforms - Market size and forecast 2025-2030 ($ million)
Data Table on Platforms - Market size and forecast 2025-2030 ($ million)
Chart on Platforms - Year-over-year growth 2025-2030 (%)
Data Table on Platforms - Year-over-year growth 2025-2030 (%)

10.4 Services - Market size and forecast 2025-2030

Chart on Services - Market size and forecast 2025-2030 ($ million)
Data Table on Services - Market size and forecast 2025-2030 ($ million)
Chart on Services - Year-over-year growth 2025-2030 (%)
Data Table on Services - Year-over-year growth 2025-2030 (%)

10.5 Market opportunity by Component

Market opportunity by Component ($ million)
Data Table on Market opportunity by Component ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.4.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.4.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.4.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.4.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.4.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.4.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.2 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising global smartphone penetration expanding addressable digital mobile advertising consumer base
Expanding programmatic advertising infrastructure automating real time mobile ad inventory procurement
Surging video content consumption propelling short form mobile video advertising budgets

13.2 Market challenges

Stringent privacy regulations restricting user tracking across global mobile advertising platforms
Sophisticated click fraud tactics diminishing return investment within mobile application networks
Severe ad fatigue exhausting target audiences throughout global mobile marketing ecosystems

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Accelerated AI integration automating hyper personalized mobile advertising creative generation
Rapid expansion mobile social commerce blurring discovery purchase cycles within applications
Widespread adoption cookieless identity frameworks overcoming platform level identity tracking restrictions

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Adikteev SAS

Adikteev SAS - Overview
Adikteev SAS - Product / Service
Adikteev SAS - Key offerings
SWOT

15.5 AppLovin Corp.

AppLovin Corp. - Overview
AppLovin Corp. - Business segments
AppLovin Corp. - Key offerings
AppLovin Corp. - Segment focus
SWOT

15.6 Blis Global Ltd.

Blis Global Ltd. - Overview
Blis Global Ltd. - Product / Service
Blis Global Ltd. - Key offerings
SWOT

15.7 Chartboost Inc.

Chartboost Inc. - Overview
Chartboost Inc. - Product / Service
Chartboost Inc. - Key offerings
SWOT

15.8 Criteo SA

Criteo SA - Overview
Criteo SA - Product / Service
Criteo SA - Key offerings
SWOT

15.9 Digital Turbine Inc.

Digital Turbine Inc. - Overview
Digital Turbine Inc. - Business segments
Digital Turbine Inc. - Key offerings
Digital Turbine Inc. - Segment focus
SWOT

15.10 Google LLC

Google LLC - Overview
Google LLC - Product / Service
Google LLC - Key offerings
SWOT

15.11 GroundTruth

GroundTruth - Overview
GroundTruth - Product / Service
GroundTruth - Key offerings
SWOT

15.12 Magnite Inc.

Magnite Inc. - Overview
Magnite Inc. - Product / Service
Magnite Inc. - Key offerings
SWOT

15.13 Meta Platforms Inc.

Meta Platforms Inc. - Overview
Meta Platforms Inc. - Business segments
Meta Platforms Inc. - Key offerings
Meta Platforms Inc. - Segment focus
SWOT

15.14 Nexxen Inc.

Nexxen Inc. - Overview
Nexxen Inc. - Product / Service
Nexxen Inc. - Key offerings
SWOT

15.15 PubMatic Inc.

PubMatic Inc. - Overview
PubMatic Inc. - Business segments
PubMatic Inc. - Key offerings
PubMatic Inc. - Segment focus
SWOT

15.16 The Trade Desk Inc.

The Trade Desk Inc. - Overview
The Trade Desk Inc. - Product / Service
The Trade Desk Inc. - Key offerings
SWOT

15.17 Unity Technologies Inc.

Unity Technologies Inc. - Overview
Unity Technologies Inc. - Business segments
Unity Technologies Inc. - Key offerings
Unity Technologies Inc. - Segment focus
SWOT

15.18 Verve Group SE

Verve Group SE - Overview
Verve Group SE - Business segments
Verve Group SE - Key offerings
Verve Group SE - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Mobile Advertising market growth will increase by USD 501299.5 million during 2026-2030.

The Mobile Advertising market is expected to grow at a CAGR of 14.6% during 2026-2030.

Mobile Advertising market is segmented by Type (Search, Display, Video, Others) End-user (Large enterprise, SMEs) Component (Platforms, Services)

Adikteev SAS, AppLovin Corp., Blis Global Ltd., Chartboost Inc., Criteo SA, Digital Turbine Inc., Google LLC, GroundTruth, InMobi Pte. Ltd., Jampp, Kayzen GmbH, Kidoz Inc., Liftoff Inc., Magnite Inc., Meta Platforms Inc., Nexxen Inc., PubMatic Inc., The Trade Desk Inc., Unity Technologies Inc., Verve Group SE are a few of the key vendors in the Mobile Advertising market.

North America will register the highest growth rate of 44.9% among the other regions. Therefore, the Mobile Advertising market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, China, Japan, India, South Korea, Australia, Indonesia, UK, Germany, France, Italy, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Turkey, Israel

  • Rising global smartphone penetration expanding addressable digital mobile advertising consumer base is the driving factor this market.

The Mobile Advertising market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
