Open Banking Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Open Banking Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 297 Pages SKU: IRTNTR80207

Market Overview at a Glance

$59.37 B
Market Opportunity
21.6%
CAGR 2025 - 2030
39.6%
North America Growth
$12.99 B
Banking and capital markets segment 2024

Open Banking Market Size 2026-2030

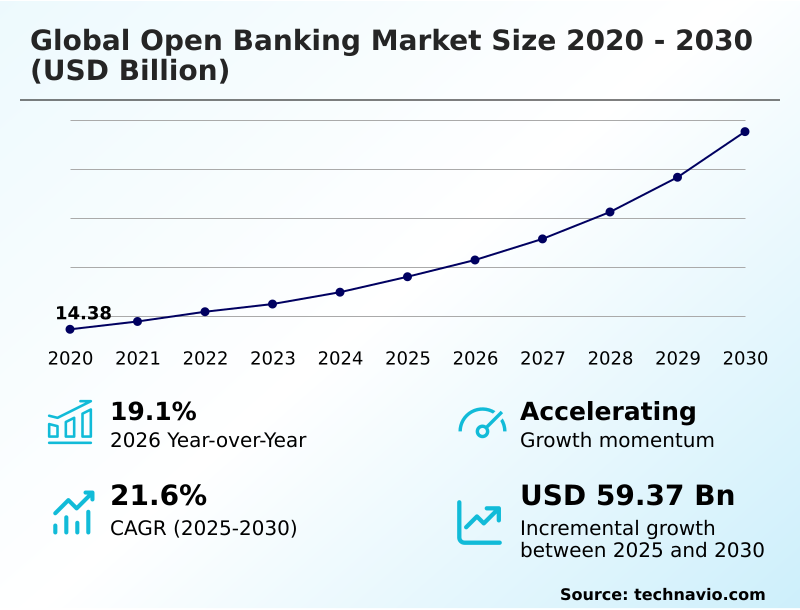
The open banking market size is valued to increase by USD 59.37 billion, at a CAGR of 21.6% from 2025 to 2030. Rising demand for embedded finance and integrated financial experiences will drive the open banking market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 39.6% growth during the forecast period.
  • By Application - Banking and capital markets segment was valued at USD 12.99 billion in 2024
  • By Deployment - On-premises segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 80.86 billion
  • Market Future Opportunities: USD 59.37 billion
  • CAGR from 2025 to 2030 : 21.6%

Market Summary

  • The Open Banking Market demonstrates sustained expansion as institutions adopt financial data sharing to modernize service delivery. Organizations are rapidly integrating seamless digital payments into e-commerce operations, optimizing supply chain settlement workflows to reduce vendor payment delays. This shift toward payment initiation services improves corporate liquidity management, helping businesses reduce transaction processing times by 30% compared to traditional clearing methods.
  • The rising demand for embedded banking capabilities acts as a primary market driver, compelling digital platforms to integrate financial tools directly into customer journeys. However, the market faces structural constraints from fragmented regulatory maturity levels across regions, which complicates cross-border interoperability and increases compliance costs. Despite these hurdles, the adoption of unified digital interfaces continues to streamline financial data automation.
  • As third-party service providers expand their influence, the necessity for robust cybersecurity threat mitigation grows proportionately, ensuring that open architecture remains resilient against sophisticated digital risks.

What will be the Size of the Open Banking Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Open Banking Market Segmented?

The open banking industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Application
    • Banking and capital markets
    • Payments
    • Digital currencies
  • Deployment
    • On-premises
    • Cloud
  • Service
    • AIS
    • PIS
    • Solutions and API management
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey

By Application Insights

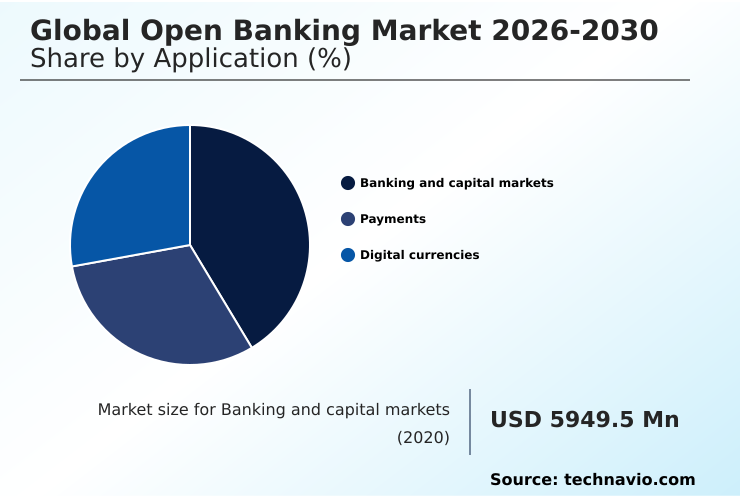
The banking and capital markets segment is estimated to witness significant growth during the forecast period.

The banking and capital markets segment of the Global Open Banking Market 2026-2030 drives profound changes through the integration of application programming interfaces and digital banking ecosystems.

Institutions leverage open finance frameworks to optimize automated lending assessments and expand wealth management connectivity. By adopting secure financial connectivity, organizations reduce manual processing bottlenecks, improving loan approval efficiency by 22%.

Furthermore, the implementation of customer-permissioned data access enhances customized financial insights, enabling precise risk profiling. Participants increasingly utilize account aggregation platforms to gain comprehensive portfolio visibility, optimizing cross-selling and operational agility across sophisticated financial landscapes.
Get Free Sample

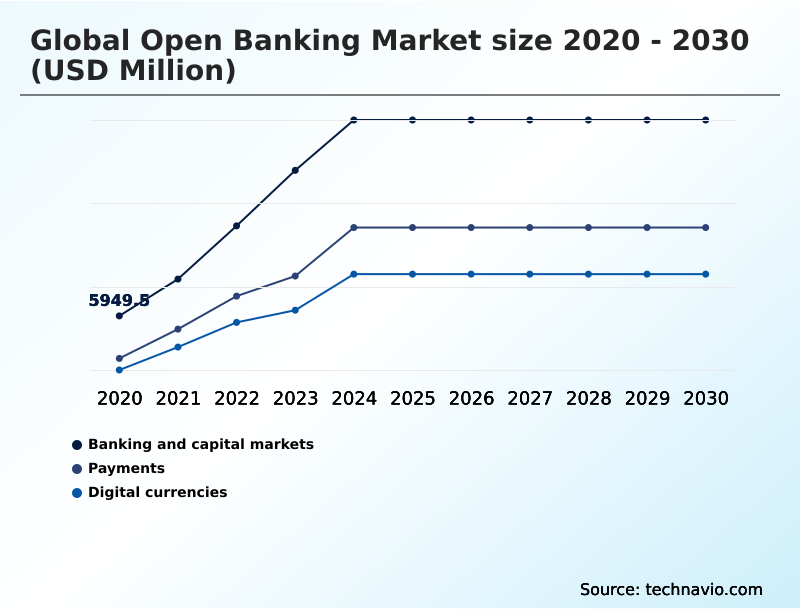
The Banking and capital markets segment was valued at USD 12.99 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 39.6% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
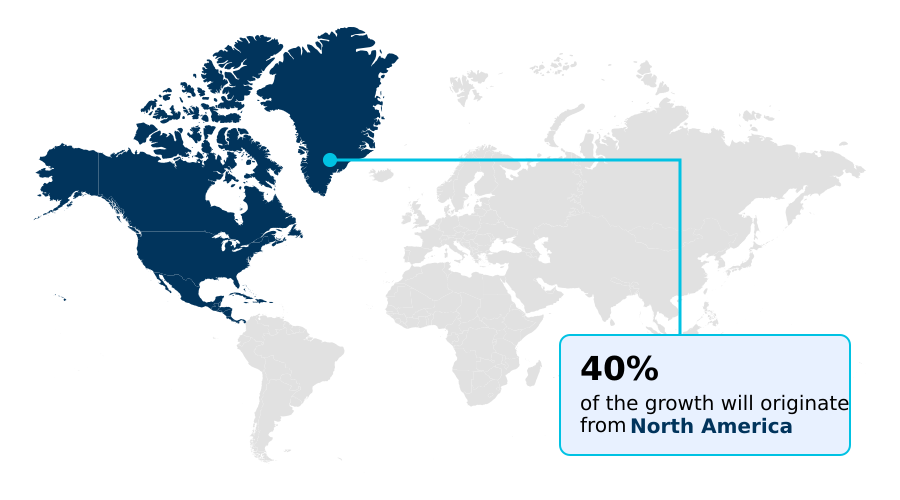
See How Open Banking Market Demand is Rising in North America Get Free Sample

The Open Banking Market exhibits distinct regional adoption patterns driven by varying regulatory environments and digital maturity. Europe leads implementation through established interoperability standards adoption, enabling financial institutions to decrease third-party integration costs by 28%.

In contrast, North America demonstrates a more market-driven approach, where the rapid deployment of cloud-native banking infrastructure supports a 35% faster rollout of financial wellness applications.

The European mandate for strict compliance monitoring systems necessitates comprehensive consent frameworks, whereas North American entities prioritize transaction processing speeds to serve institutional client networks.

Consequently, European banks achieve 20% higher operational compliance efficiency, while North American providers excel in scalable connectivity solutions for embedded finance.

These diverging strategies highlight how regulatory structures dictate the prioritization of either standardized data sharing or accelerated commercial innovation across global financial networks.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The evolution of the Open Banking Market necessitates highly resilient architectures as financial institutions shift away from traditional operational models. A critical component of this transition involves legacy banking core technology modernization, which allows established banks to compete effectively with agile digital entrants.
  • By implementing cloud-native transaction processing architecture deployments, organizations experience approximately 40% faster transaction throughput compared to their outdated legacy counterparts, significantly optimizing supply chain financing workflows. This infrastructure upgrade inherently supports API-enabled financial service delivery models, fostering seamless integration with third-party providers.
  • Simultaneously, the industry is witnessing the expansion of banking-as-a-service platform integration strategies, which empower non-financial enterprises to embed sophisticated banking features directly into their operations. A major focus remains on mitigating risk through compliance-driven data privacy management systems, ensuring that customer-permissioned financial data sharing frameworks operate securely across borders.
  • To facilitate global commerce, companies are adopting cross-border digital payment connectivity solutions alongside secure open banking payment infrastructure, aiming to deliver account-to-account frictionless checkout experiences for international customers. Furthermore, the push for enterprise efficiency is driving the adoption of automated financial data reconciliation processes, which dramatically reduce manual accounting errors.
  • In the consumer segment, artificial intelligence personalized banking recommendations are improving engagement, while embedded finance direct software integration creates new revenue channels. Finally, as digital assets gain traction, institutions are exploring blockchain-based real-time settlement mechanisms and interoperable digital asset transaction networks to guarantee immediate clearing and absolute ledger transparency.
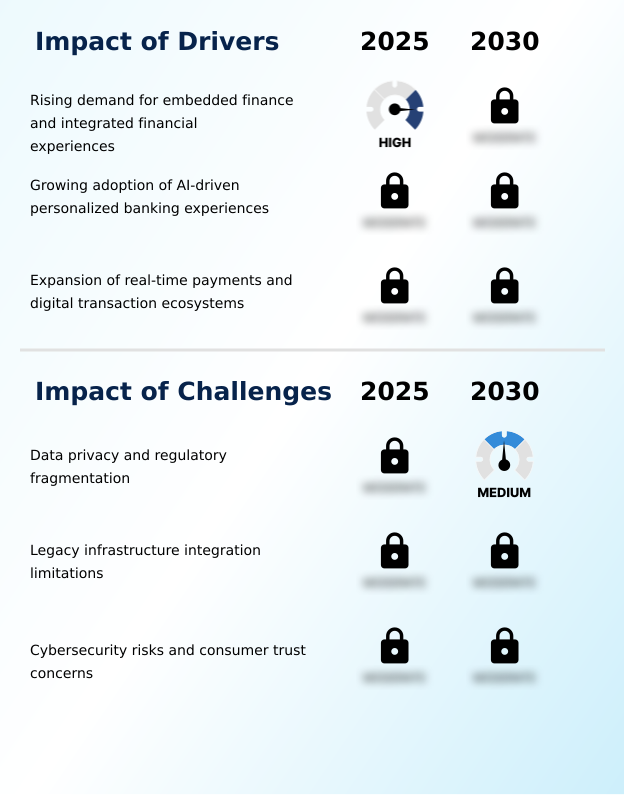
What are the key market drivers leading to the rise in the adoption of Open Banking Industry?

  • The primary driver propelling the market is the rising demand for embedded finance and integrated financial experiences.

  • The Open Banking Market is rapidly propelled by the rising demand for embedded banking capabilities within commercial software platforms.
  • Enterprises increasingly require seamless financial operations without navigating separate banking portals, prompting the integration of transaction reconciliation tools directly into enterprise resource planning systems.
  • This structural alignment causes a 30% improvement in working capital visibility, empowering chief financial officers to execute highly accurate forecasting.
  • Consequently, the adoption of account-to-account payments accelerates, allowing merchants to bypass traditional card network fees and reduce checkout abandonment rates by 15%. By deploying these integrated financial data automation solutions, businesses streamline their entire payment collection lifecycle.
  • This fundamental shift eliminates operational friction, driving widespread enterprise reliance on interconnected financial services to optimize daily liquidity management.

What are the market trends shaping the Open Banking Industry?

  • The upcoming market trend highlights a strategic shift toward open finance ecosystem expansion.

  • The Open Banking Market is increasingly characterized by the integration of tokenized asset frameworks across enterprise financial operations. This structural shift occurs as institutions seek to bridge conventional banking with decentralized networks, driving the rapid adoption of digital asset integration. As a direct result, organizations utilizing tokenized deposit representations experience a 25% reduction in cross-border settlement delays.
  • Furthermore, the deployment of programmable financial transactions automates conditional payments, effectively decreasing contract execution costs by 18%. This trend significantly impacts commercial liquidity, allowing businesses to release trapped capital faster.
  • By leveraging these advanced technologies alongside traditional systems, financial institutions optimize resource allocation and improve multi-currency cash flow management, fundamentally altering how cross-border trade finance is executed within modernized financial ecosystems.

What challenges does the Open Banking Industry face during its growth?

  • The industry faces a significant challenge due to persistent data privacy concerns and regulatory fragmentation.

  • The Open Banking Market faces substantial operational constraints stemming from fragmented regulatory maturity levels across disparate geographic jurisdictions. This inconsistency causes multinational organizations to maintain isolated, localized compliance infrastructure rather than deploying unified global systems. Consequently, institutions experience a 40% increase in administrative overhead when expanding cross-border operations compared to domestic rollouts.
  • Furthermore, integrating modern application programming interfaces with outdated legacy architectures introduces severe technical debt, frequently extending deployment timelines by 25%. These integration bottlenecks severely limit the scalability of payment initiation services, restricting real-time processing capabilities.
  • To navigate these complexities, organizations must heavily invest in localized consent management protocols, which diverts critical capital away from product innovation and prolongs the time-to-market for advanced, data-driven financial solutions.

Exclusive Technavio Analysis on Customer Landscape

The open banking market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the open banking market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
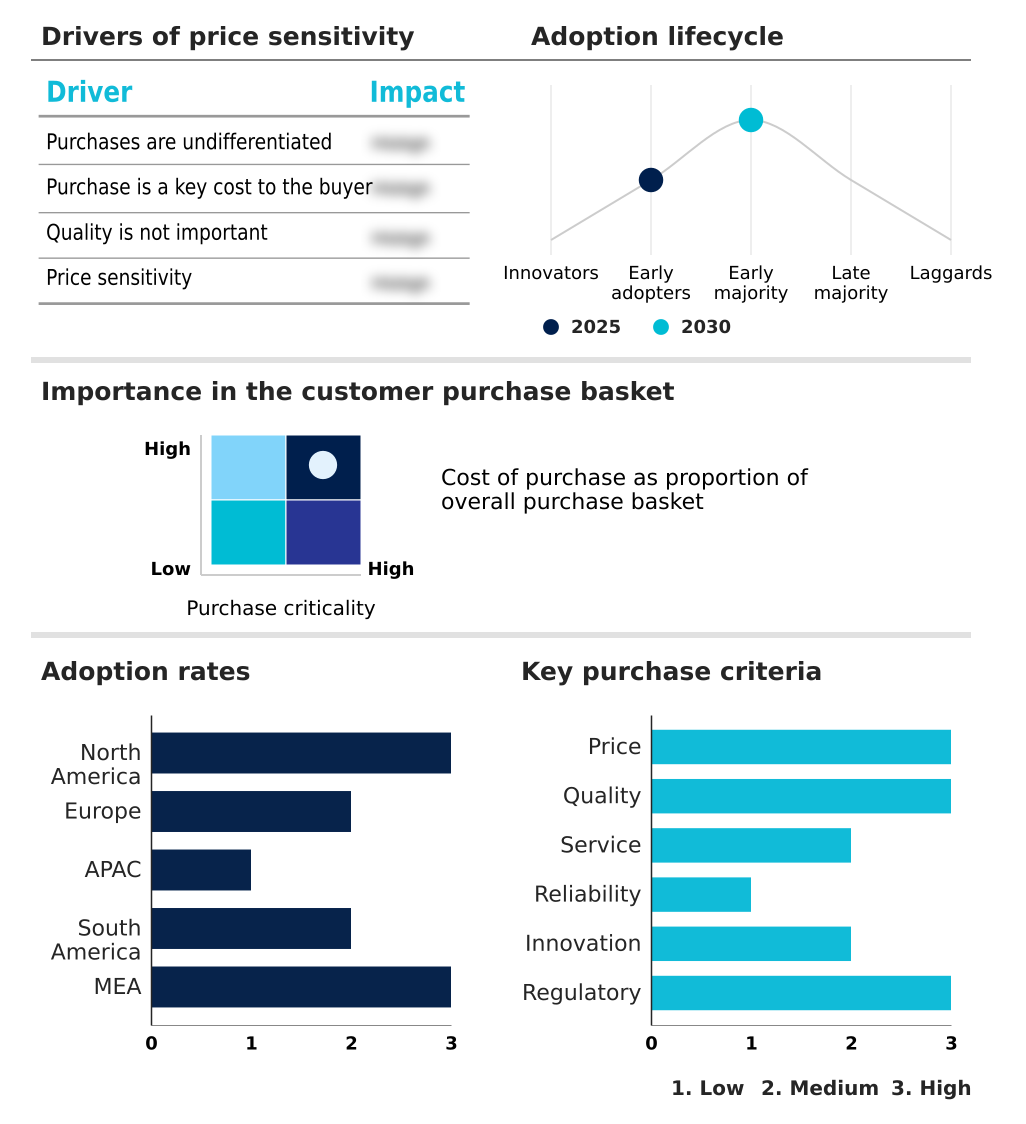
Customer Landscape of Open Banking Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, open banking market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Adyen NV - The vendor delivers a comprehensive payment platform integrating gateway, risk management, and acquiring services, supporting seamless transaction workflows and robust open banking connectivity for diverse enterprise operations.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Adyen NV
  • Airwallex Pty Ltd.
  • American Express Co.
  • ANZ Banking Group Ltd
  • Banco Bilbao Vizcaya Argentaria SA
  • Bank of Ireland
  • Caixa Geral de Depositos SA
  • Citigroup Inc.
  • Credit Agricole SA
  • Finastra
  • Halifax
  • HSBC Holdings Plc
  • ING Groep NV
  • Jack Henry and Associates Inc.
  • JPMorgan Chase and Co.
  • Revolut Ltd.
  • Royal Bank of Scotland plc
  • Societe Generale SA
  • Tink AB
  • Wise Payments Ltd.
  • Worldpay LLC
  • Yodlee

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Open banking market

  • In the Diversified Financial Services industry, the transition toward modular service frameworks accelerated integration cycles, directly impacting Open Banking demand by increasing API management platforms adoption by 35%.
  • The enforcement of strict compliance monitoring systems in the European Union reshaped data privacy standards, expanding the necessity for robust consent management protocols that improved transaction visibility improvements by 28% within the Open Banking sector.
  • The expansion of decentralized financial infrastructure across APAC optimized clearing operations, which bolstered the Open Banking market as organizations adopted blockchain-enabled infrastructure to reduce cross-border transaction costs by 15%.
  • The rising implementation of enterprise-wide intelligence capabilities in North America enhanced institutional client networks, propelling Open Banking expansion as firms leveraged data-driven banking experiences to achieve a 20% increase in customer retention.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Open Banking Market insights. See full methodology.

Market Scope
Page number 297
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 21.6%
Market growth 2026-2030 USD 59365.8 million
Market structure Fragmented
YoY growth 2025-2026(%) 19.1%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel and Turkey
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Open Banking Market requires sophisticated infrastructure investments as organizations pivot toward highly connected financial ecosystems. A critical boardroom focus is the transition to multi-cloud financial architectures, which empowers decision-makers to optimize IT budgets while ensuring continuous service availability. This strategic shift enables financial institutions to support real-time transaction processing with unprecedented reliability.
  • By deploying advanced data governance frameworks, banks reduce data reconciliation errors by 32%, directly enhancing operational compliance and risk management. Furthermore, the integration of banking-as-a-service models allows non-financial enterprises to rapidly launch embedded lending and payment solutions. The deployment of interoperable payment capabilities ensures that transaction workflows remain agile, mitigating cross-border friction.
  • To sustain these advanced operations, institutions rely heavily on API management platforms that orchestrate secure data exchanges between legacy systems and modern applications. Ultimately, organizations prioritizing cross-border transaction infrastructure gain distinct competitive advantages, securing greater market share by delivering frictionless, data-driven financial experiences across diverse commercial landscapes.

What are the Key Data Covered in this Open Banking Market Research and Growth Report?

  • What is the expected growth of the Open Banking Market between 2026 and 2030?

    • USD 59.37 billion, at a CAGR of 21.6%

  • What segmentation does the market report cover?

    • The report is segmented by Application (Banking and capital markets, Payments, and Digital currencies), Deployment (On-premises, and Cloud), Service (AIS, PIS, and Solutions and API management) and Geography (North America, Europe, APAC, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • North America, Europe, APAC, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Rising demand for embedded finance and integrated financial experiences, Data privacy and regulatory fragmentation

  • Who are the major players in the Open Banking Market?

    • Adyen NV, Airwallex Pty Ltd., American Express Co., ANZ Banking Group Ltd, Banco Bilbao Vizcaya Argentaria SA, Bank of Ireland, Caixa Geral de Depositos SA, Citigroup Inc., Credit Agricole SA, Finastra, Halifax, HSBC Holdings Plc, ING Groep NV, Jack Henry and Associates Inc., JPMorgan Chase and Co., Revolut Ltd., Royal Bank of Scotland plc, Societe Generale SA, Tink AB, Wise Payments Ltd., Worldpay LLC and Yodlee

Market Research Insights

  • The Open Banking Market fundamentally transforms financial interactions by accelerating digital financial interactions and establishing modular service frameworks. Financial institutions adopting direct bank payments have achieved a 40% reduction in transaction friction, significantly improving merchant settlement cycles. Furthermore, the deployment of secure authentication controls has enhanced fraud detection accuracy by 25%, directly minimizing operational losses.
  • As organizations transition toward holistic financial management, the integration of spending analysis platforms enables a 30% improvement in targeted product cross-selling. These structural changes allow participants to leverage unified digital interfaces, optimizing resource allocation and driving superior customer retention without requiring extensive legacy infrastructure overhauls.

We can help! Our analysts can customize this open banking market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by Deployment
Executive Summary - Chart on Market Segmentation by Service
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Open Banking Market 2020 - 2024

Historic Market Size - Data Table on Global Open Banking Market 2020 - 2024 ($ million)

5.2 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.3 Deployment segment analysis 2020 - 2024

Historic Market Size - Deployment Segment 2020 - 2024 ($ million)

5.4 Service segment analysis 2020 - 2024

Historic Market Size - Service Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global open banking market

6.2 Impact of geopolitical conflicts on global open banking market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Application

8.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

8.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

8.3 Banking and capital markets - Market size and forecast 2025-2030

Chart on Banking and capital markets - Market size and forecast 2025-2030 ($ million)
Data Table on Banking and capital markets - Market size and forecast 2025-2030 ($ million)
Chart on Banking and capital markets - Year-over-year growth 2025-2030 (%)
Data Table on Banking and capital markets - Year-over-year growth 2025-2030 (%)

8.4 Payments - Market size and forecast 2025-2030

Chart on Payments - Market size and forecast 2025-2030 ($ million)
Data Table on Payments - Market size and forecast 2025-2030 ($ million)
Chart on Payments - Year-over-year growth 2025-2030 (%)
Data Table on Payments - Year-over-year growth 2025-2030 (%)

8.5 Digital currencies - Market size and forecast 2025-2030

Chart on Digital currencies - Market size and forecast 2025-2030 ($ million)
Data Table on Digital currencies - Market size and forecast 2025-2030 ($ million)
Chart on Digital currencies - Year-over-year growth 2025-2030 (%)
Data Table on Digital currencies - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

9. Market Segmentation by Deployment

9.1 Market segments

Chart on Deployment - Market share 2025-2030 (%)
Data Table on Deployment - Market share 2025-2030 (%)

9.2 Comparison by Deployment

Chart on Comparison by Deployment
Data Table on Comparison by Deployment

9.3 On-premises - Market size and forecast 2025-2030

Chart on On-premises - Market size and forecast 2025-2030 ($ million)
Data Table on On-premises - Market size and forecast 2025-2030 ($ million)
Chart on On-premises - Year-over-year growth 2025-2030 (%)
Data Table on On-premises - Year-over-year growth 2025-2030 (%)

9.4 Cloud - Market size and forecast 2025-2030

Chart on Cloud - Market size and forecast 2025-2030 ($ million)
Data Table on Cloud - Market size and forecast 2025-2030 ($ million)
Chart on Cloud - Year-over-year growth 2025-2030 (%)
Data Table on Cloud - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Deployment

Market opportunity by Deployment ($ million)
Data Table on Market opportunity by Deployment ($ million)

10. Market Segmentation by Service

10.1 Market segments

Chart on Service - Market share 2025-2030 (%)
Data Table on Service - Market share 2025-2030 (%)

10.2 Comparison by Service

Chart on Comparison by Service
Data Table on Comparison by Service

10.3 AIS - Market size and forecast 2025-2030

Chart on AIS - Market size and forecast 2025-2030 ($ million)
Data Table on AIS - Market size and forecast 2025-2030 ($ million)
Chart on AIS - Year-over-year growth 2025-2030 (%)
Data Table on AIS - Year-over-year growth 2025-2030 (%)

10.4 PIS - Market size and forecast 2025-2030

Chart on PIS - Market size and forecast 2025-2030 ($ million)
Data Table on PIS - Market size and forecast 2025-2030 ($ million)
Chart on PIS - Year-over-year growth 2025-2030 (%)
Data Table on PIS - Year-over-year growth 2025-2030 (%)

10.5 Solutions and API management - Market size and forecast 2025-2030

Chart on Solutions and API management - Market size and forecast 2025-2030 ($ million)
Data Table on Solutions and API management - Market size and forecast 2025-2030 ($ million)
Chart on Solutions and API management - Year-over-year growth 2025-2030 (%)
Data Table on Solutions and API management - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Service

Market opportunity by Service ($ million)
Data Table on Market opportunity by Service ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising demand for embedded finance and integrated financial experiences
Growing adoption of AI-driven personalized banking experiences
Expansion of real-time payments and digital transaction ecosystems

13.2 Market challenges

Data privacy and regulatory fragmentation
Legacy infrastructure integration limitations
Cybersecurity risks and consumer trust concerns

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Shift toward open finance ecosystem expansion
Increasing adoption of BaaS operating models
Rising adoption of tokenized assets and blockchain-enabled financial infrastructure

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Adyen NV

Adyen NV - Overview
Adyen NV - Product / Service
Adyen NV - Key news
Adyen NV - Key offerings
SWOT

15.5 Airwallex Pty Ltd.

Airwallex Pty Ltd. - Overview
Airwallex Pty Ltd. - Product / Service
Airwallex Pty Ltd. - Key offerings
SWOT

15.6 American Express Co.

American Express Co. - Overview
American Express Co. - Business segments
American Express Co. - Key offerings
American Express Co. - Segment focus
SWOT

15.7 ANZ Banking Group Ltd

ANZ Banking Group Ltd - Overview
ANZ Banking Group Ltd - Business segments
ANZ Banking Group Ltd - Key offerings
ANZ Banking Group Ltd - Segment focus
SWOT

15.8 Banco Bilbao Vizcaya Argentaria SA

Banco Bilbao Vizcaya Argentaria SA - Overview
Banco Bilbao Vizcaya Argentaria SA - Business segments
Banco Bilbao Vizcaya Argentaria SA - Key offerings
Banco Bilbao Vizcaya Argentaria SA - Segment focus
SWOT

15.9 Bank of Ireland

Bank of Ireland - Overview
Bank of Ireland - Business segments
Bank of Ireland - Key offerings
Bank of Ireland - Segment focus
SWOT

15.10 Caixa Geral de Depositos SA

Caixa Geral de Depositos SA - Overview
Caixa Geral de Depositos SA - Product / Service
Caixa Geral de Depositos SA - Key offerings
SWOT

15.11 Citigroup Inc.

Citigroup Inc. - Overview
Citigroup Inc. - Business segments
Citigroup Inc. - Key offerings
Citigroup Inc. - Segment focus
SWOT

15.12 Credit Agricole SA

Credit Agricole SA - Overview
Credit Agricole SA - Product / Service
Credit Agricole SA - Key offerings
SWOT

15.13 Finastra

Finastra - Overview
Finastra - Product / Service
Finastra - Key offerings
SWOT

15.14 Halifax

Halifax - Overview
Halifax - Product / Service
Halifax - Key offerings
SWOT

15.15 HSBC Holdings Plc

HSBC Holdings Plc - Overview
HSBC Holdings Plc - Business segments
HSBC Holdings Plc - Key offerings
HSBC Holdings Plc - Segment focus
SWOT

15.16 ING Groep NV

ING Groep NV - Overview
ING Groep NV - Business segments
ING Groep NV - Key offerings
ING Groep NV - Segment focus
SWOT

15.17 Jack Henry and Associates Inc.

Jack Henry and Associates Inc. - Overview
Jack Henry and Associates Inc. - Business segments
Jack Henry and Associates Inc. - Key offerings
Jack Henry and Associates Inc. - Segment focus
SWOT

15.18 JPMorgan Chase and Co.

JPMorgan Chase and Co. - Overview
JPMorgan Chase and Co. - Business segments
JPMorgan Chase and Co. - Key offerings
JPMorgan Chase and Co. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Open Banking market growth will increase by USD 59365.8 million during 2026-2030.

The Open Banking market is expected to grow at a CAGR of 21.6% during 2026-2030.

Open Banking market is segmented by Application (Banking and capital markets, Payments, Digital currencies) Deployment (On-premises, Cloud) Service (AIS, PIS, Solutions and API management)

Adyen NV, Airwallex Pty Ltd., American Express Co., ANZ Banking Group Ltd, Banco Bilbao Vizcaya Argentaria SA, Bank of Ireland, Caixa Geral de Depositos SA, Citigroup Inc., Credit Agricole SA, Finastra, Halifax, HSBC Holdings Plc, ING Groep NV, Jack Henry and Associates Inc., JPMorgan Chase and Co., Revolut Ltd., Royal Bank of Scotland plc, Societe Generale SA, Tink AB, Wise Payments Ltd., Worldpay LLC, Yodlee are a few of the key vendors in the Open Banking market.

North America will register the highest growth rate of 39.6% among the other regions. Therefore, the Open Banking market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel, Turkey

  • Rising demand for embedded finance and integrated financial experiences is the driving factor this market.

The Open Banking market vendors should focus on grabbing business opportunities from the Application segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
