Road Logistics Market Analysis, Size, and Forecast 2026-2030: APAC (China, India, and Japan), North America (US, Canada, and Mexico), Europe (Germany, UK, and France), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Road Logistics Market Analysis, Size, and Forecast 2026-2030:
APAC (China, India, and Japan), North America (US, Canada, and Mexico), Europe (Germany, UK, and France), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 305 Pages SKU: IRTNTR70568

Market Overview at a Glance

$800 B
Market Opportunity
3.4%
CAGR 2025 - 2030
53.9%
APAC Growth
$2992 B
Domestic segment 2024

Road Logistics Market Size 2026-2030

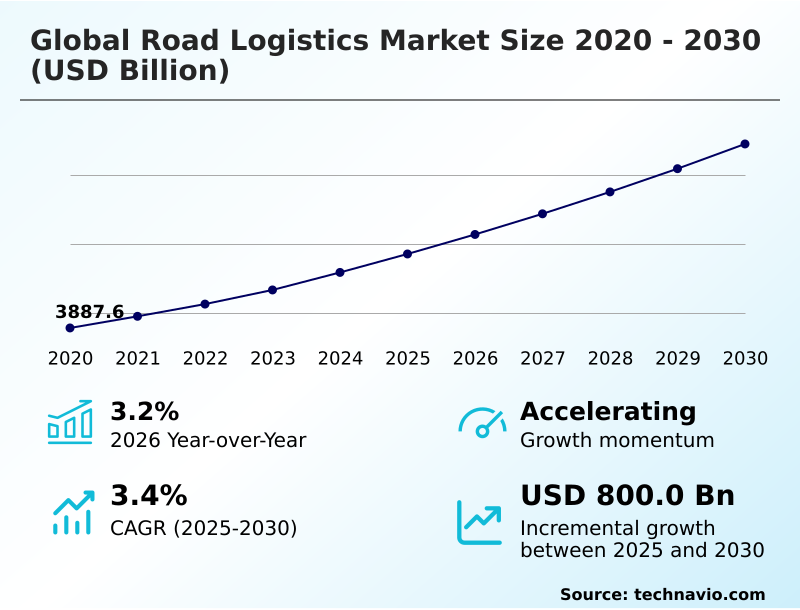
The road logistics market size is valued to increase by USD 800 billion, at a CAGR of 3.4% from 2025 to 2030. Expansion and demand for rapid last-mile delivery will drive the road logistics market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 53.9% growth during the forecast period.
  • By Application - Domestic segment was valued at USD 2992 billion in 2024
  • By Type - Truckload segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 1338.1 billion
  • Market Future Opportunities: USD 800 billion
  • CAGR from 2025 to 2030 : 3.4%

Market Summary

  • The Road Logistics Market functions as the critical physical bridge for domestic and international supply chains, facilitating the uninterrupted movement of industrial and consumer goods. Rapid e-commerce expansion acts as a primary catalyst, propelling the demand for highly responsive last-mile delivery networks that connect centralized distribution hubs to residential endpoints.
  • For example, in omnichannel retail fulfillment, motor carriers utilizing dynamic routing platforms dynamically reroute vehicles around localized traffic congestion, improving delivery window accuracy. Implementing automated dispatch systems results in a 20% higher fleet utilization rate compared to legacy manual scheduling methods.
  • However, severe commercial driver shortages and an aging workforce demographic present significant operational challenges, limiting network capacity and inflating labor retention costs. As a result, transportation providers are increasingly forced to balance rising wage expenditures against the necessity for continuous capital investment in fleet modernization.
  • Strategic adoption of telemetry and zero-emission commercial vehicles ultimately allows enterprise carriers to mitigate these structural headwinds while maintaining compliance with evolving environmental mandates.

What will be the Size of the Road Logistics Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Road Logistics Market Segmented?

The road logistics industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD billion" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Application
    • Domestic
    • International
  • Type
    • Truckload
    • Less than truckload
    • Parcel
    • Same day
  • End-user
    • Manufacturing
    • Retail
    • Automotive
    • Healthcare
    • Others
  • Geography
    • APAC
      • China
      • India
      • Japan
      • South Korea
      • Indonesia
      • Australia
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Turkey
      • Israel

By Application Insights

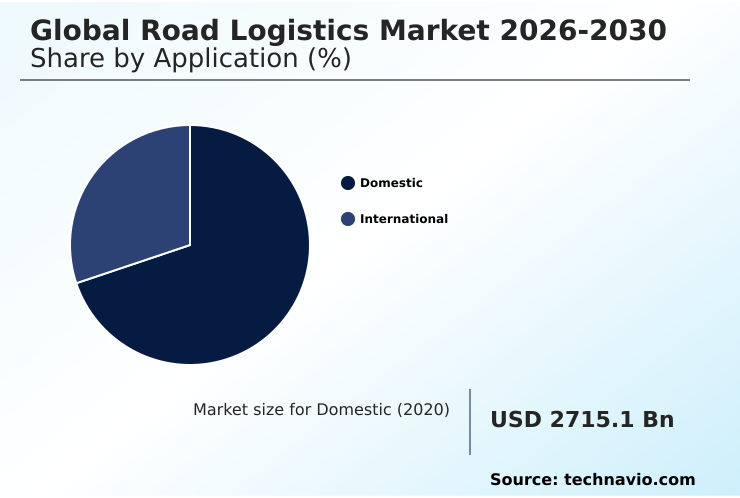
The domestic segment is estimated to witness significant growth during the forecast period.

The domestic application within the Road Logistics sector handles the intra-country movement of goods, connecting local manufacturing plants directly to regional retail networks.

As domestic supply chains become highly localized, operators are increasingly integrating a temperature controlled cold chain to ensure the integrity of perishable goods during transit.

The deployment of internet of things sensor arrays allows for real-time tracking, resulting in transit error detection improving by 15%. Furthermore, cloud native transportation management platforms provide the necessary agility to manage industrial component haulage effectively, reducing operational friction.

Automated dispatch systems mitigate the impact of seasonal volume fluctuations by dynamically allocating fleet assets. Compared to manual routing, digital allocation demonstrates a 25% higher efficiency rate in asset utilization.

Companies also utilize smart thermal packaging and third party logistics integration to streamline workflows and maintain precise delivery schedules across domestic corridors.
Get Free Sample

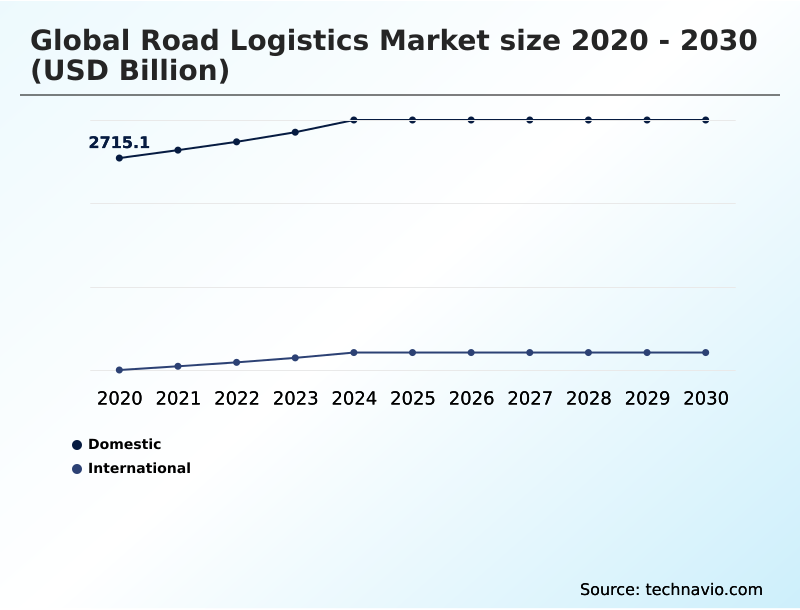
The Domestic segment was valued at USD 2992 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 53.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
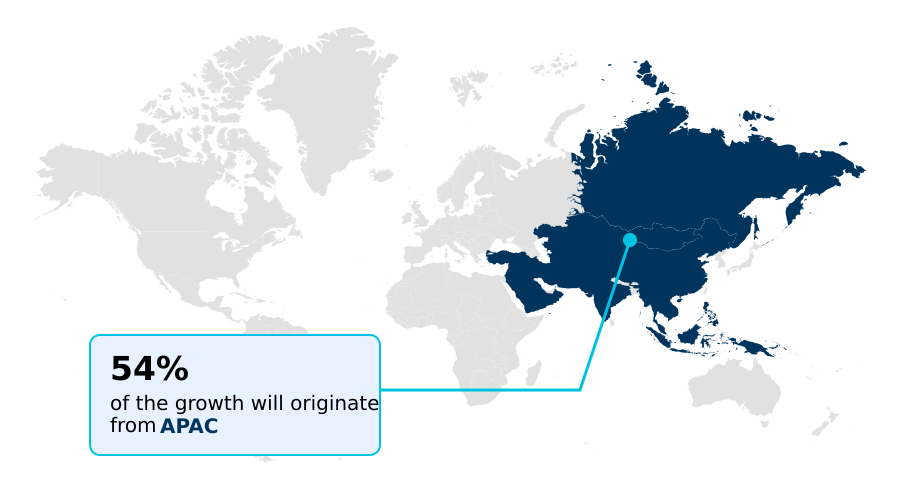
See How Road Logistics Market Demand is Rising in APAC Get Free Sample

Geographic variations within the Road Logistics sector are stark, heavily influenced by localized infrastructure investments and trade policies.

The APAC region demonstrates rapid expansion due to deep industrial manufacturing output, achieving a 35% higher throughput in intermodal freight transit compared to Europe.

Conversely, North American operators focus intensely on mitigating localized traffic congestion and optimizing empty backhaul mileage, which has driven a 20% improvement in cross dock terminal operations efficiency.

The utilization of digital freight matching algorithms and load matching marketplaces has fundamentally altered freight forwarder networks, elevating capacity utilization rates by 18% in highly fragmented domestic corridors.

As less than truckload consolidation becomes essential for e-commerce, operators across both regions continually adjust their freight routing workflows to minimize dwell times. Ultimately, these targeted infrastructure and digital investments dictate regional supply chain resilience and operational profitability.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The structural evolution of the Road Logistics sector requires fleet operators to fundamentally rethink asset management, regulatory alignment, and technological deployment. A primary focus for major carriers is the integration of artificial intelligence in route optimization, which dynamically adjusts transit paths based on real-time traffic and weather data.
  • This technological shift, coupled with targeted battery electric fleet transition strategies, allows organizations to proactively address environmental regulations while managing volatile energy expenses. Consequently, logistics providers adopting these digital solutions achieve a 30% higher asset efficiency ratio compared to those relying on conventional manual planning frameworks.
  • Navigating international trade corridors necessitates strict adherence to cross border transport compliance protocols to minimize friction at customs checkpoints and avoid costly border delays. As consumer expectations for rapid fulfillment intensify, the development of sophisticated last mile urban delivery networks has become crucial for maintaining service level agreements within dense metropolitan areas.
  • Concurrently, the implementation of predictive analytics for fleet maintenance enables service technicians to identify potential mechanical failures before they occur, drastically reducing unprogrammed vehicle downtime. By aligning these advanced routing, maintenance, and compliance strategies, transportation enterprises can sustainably orchestrate complex supply chain operations and secure long-term operational resilience across highly competitive global freight networks.
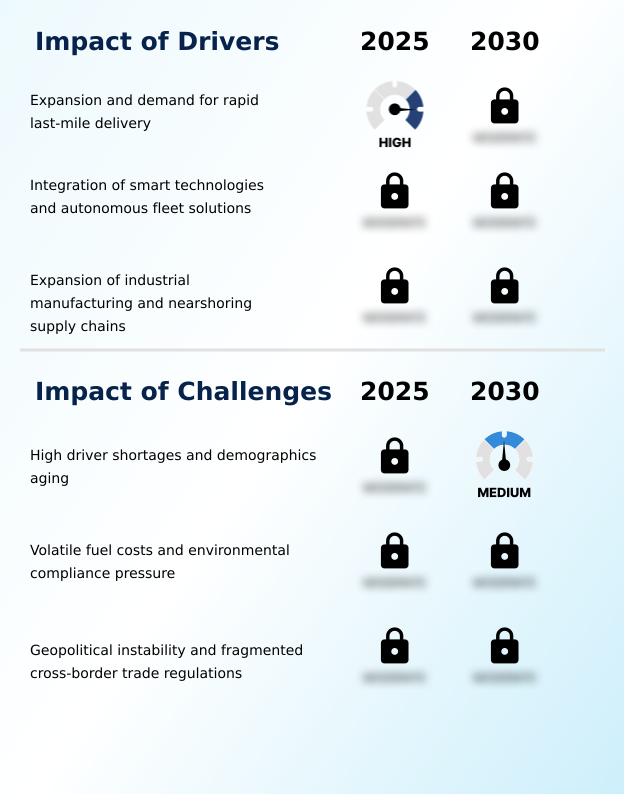
What are the key market drivers leading to the rise in the adoption of Road Logistics Industry?

  • The rapid expansion of e-commerce platforms and the subsequent surge in demand for highly responsive last-mile delivery networks function as primary catalysts propelling industry growth.

  • The exponential growth of omnichannel retail fulfillment is fundamentally accelerating structural demand across the Road Logistics sector.
  • As consumer expectations for rapid purchasing turnarounds intensify, retailers depend heavily on just in time inventory flows to prevent stockouts at regional distribution hubs.
  • This consumer-driven pressure requires the implementation of dynamic route optimization and automated parcel sorting, which together have improved final-mile delivery window accuracy by 30%.
  • To sustain high-frequency order cadences, enterprise operators are integrating sophisticated supply chain visibility platforms that seamlessly orchestrate middle mile linehaul networks. By leveraging urban micro fulfillment centers and advanced return logistics handling, motor carriers effectively reduce transit delays by 18%.
  • Ultimately, precise last mile delivery orchestration acts as the primary catalyst pushing freight networks toward higher digital maturity and asset efficiency.

What are the market trends shaping the Road Logistics Industry?

  • An accelerated transition toward zero-emission commercial fleets represents a critical structural shift within the industry. This evolution is primarily driven by stringent environmental regulations and corporate sustainability targets.

  • A rapid transition toward alternative propulsion systems is reshaping the foundational architecture of the Road Logistics sector. As global supply chains face tightening fleet decarbonization mandates, major transport operators are aggressively deploying zero emission commercial vehicles to maintain compliance within restricted urban low emission zones.
  • The establishment of high-capacity fleet charging infrastructure has become a critical operational priority, directly reducing per-mile energy expenditures by 22%. Simultaneously, carriers are exploring autonomous highway platooning to alleviate persistent labor shortages, improving long-haul fuel efficiency by 15%. To protect these capital-intensive investments, logistics managers increasingly rely on advanced engine diagnostics and predictive maintenance analytics to monitor vehicle health.
  • This proactive maintenance approach decreases mechanical failure rates by 28%, ensuring that battery electric heavy duty fleets and hydrogen fuel cell commercial trucks maintain maximum continuous uptime across dense freight corridors.

What challenges does the Road Logistics Industry face during its growth?

  • Severe commercial driver shortages, compounded by an aging workforce demographic, pose substantial operational constraints that significantly hinder scalable network capacity.

  • Severe workforce constraints and complex regulatory environments pose significant barriers to scaling Road Logistics operations globally. The chronic lack of commercial driver retention forces fleet operators to increase compensation packages, driving overall labor expenditures up by 20% compared to historical averages.
  • Concurrently, strict enforcement of driver hours of service and electronic logging device compliance limits the daily operational range of heavy goods vehicles. Carriers must also navigate volatile geopolitical supply chain bottlenecks and rigid cross border customs clearance protocols, which frequently cause unpredictable border delays and inflate transit times by 15%.
  • Furthermore, unpredictable fuel surcharge volatility and escalating highway toll structures compress operating margins. To mitigate these risks, organizations invest heavily in vehicle safety inspections and cargo security escorts, aiming to protect high-value freight density pricing models from external disruption.

Exclusive Technavio Analysis on Customer Landscape

The road logistics market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the road logistics market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
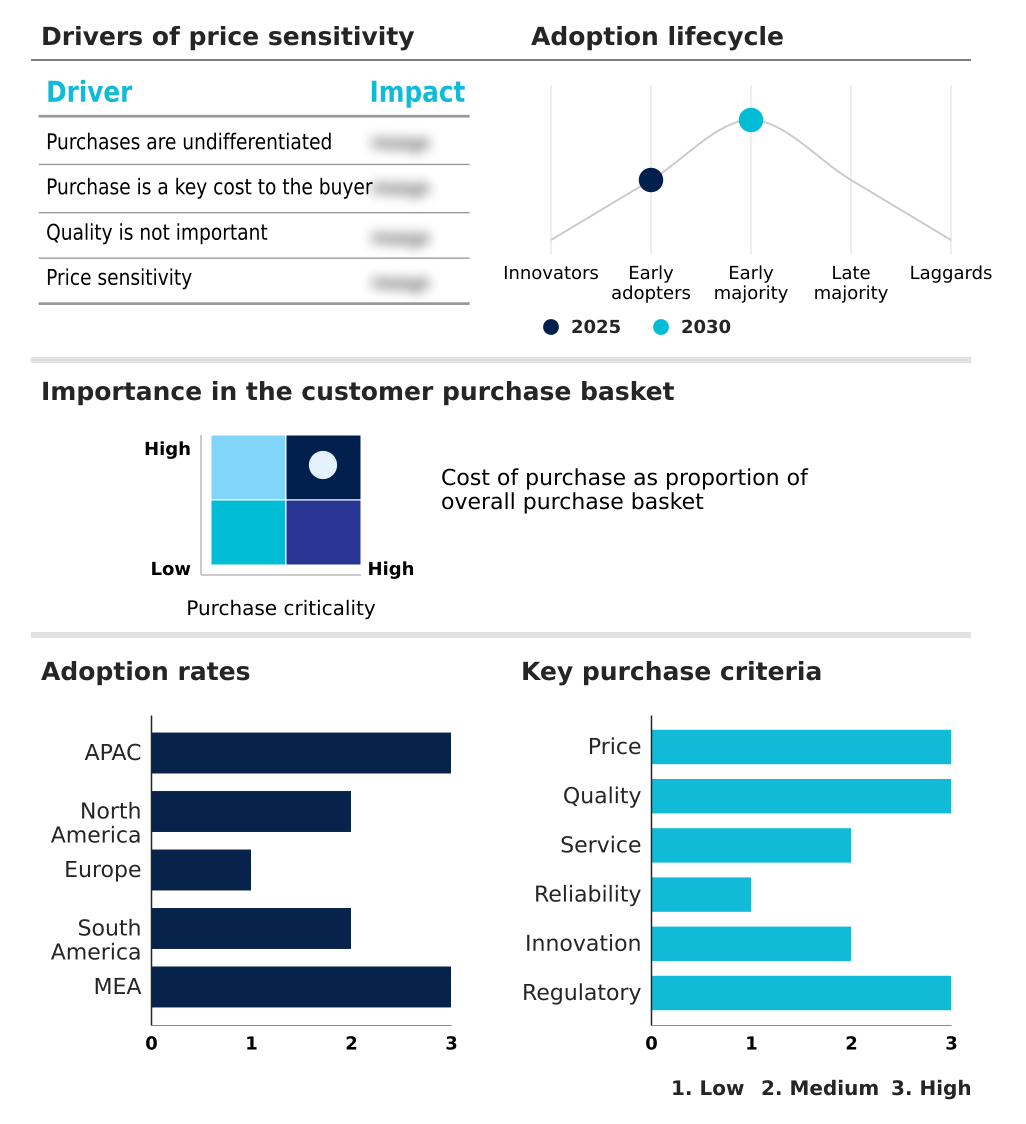
Customer Landscape of Road Logistics Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, road logistics market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Agility Global PLC - The entity provides comprehensive road freight, truckload transportation, and less than truckload services, ensuring efficient cargo distribution and integrated supply chain management across diverse commercial operational networks.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Agility Global PLC
  • AP Moller Maersk AS
  • ArcBest Corp.
  • C H Robinson Worldwide Inc.
  • CEVA Logistics SA
  • Dachser SE
  • DB Schenker
  • DHL International GmbH
  • DSV AS
  • Estes Express Lines
  • FedEx Corp.
  • GEODIS
  • Hellmann Worldwide Logistics
  • JB Hunt Transport Services
  • Kuehne Nagel Management AG
  • Landstar System Inc.
  • Mainfreight Ltd.
  • Nippon Express Holdings Inc.
  • Rhenus SE and Co. KG
  • Schneider National Inc.
  • TFI International Inc.
  • Toll Holdings Ltd.
  • United Parcel Service Inc.
  • XPO Inc.
  • Yusen Logistics Co. Ltd.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Road logistics market

  • In the Cargo Ground Transportation industry, the widespread implementation of fleet decarbonization mandates across the European Union has accelerated the transition toward zero emission commercial vehicles, directly impacting Road Logistics demand by requiring carriers to replace 30% of legacy diesel assets.
  • Stringent regulatory shifts regarding driver hours of service and electronic logging device compliance in North America have fundamentally altered cross border customs clearance protocols, directly impacting Road Logistics demand by decreasing average daily transit distances by 12%.
  • Advancements in automated parcel sorting and supply chain visibility platforms have transformed regional distribution hubs in APAC, directly impacting Road Logistics demand by increasing middle mile linehaul network throughput capacity by 18%.
  • The integration of predictive maintenance analytics within heavy equipment manufacturing has modernized vehicle safety inspections, directly impacting Road Logistics demand by reducing unexpected mechanical breakdowns by 22% and improving overall capacity utilization rates.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Road Logistics Market insights. See full methodology.

Market Scope
Page number 305
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 3.4%
Market growth 2026-2030 USD 800.0 billion
Market structure Fragmented
YoY growth 2025-2026(%) 3.2%
Key countries China, India, Japan, South Korea, Indonesia, Australia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Turkey and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Road Logistics ecosystem is undergoing rapid modernization as enterprise carriers pivot toward digital orchestration and sustainable transportation models. Strategic boardroom decisions now heavily prioritize the deployment of battery electric heavy duty fleets and hydrogen fuel cell commercial trucks to meet stringent corporate decarbonization targets.
  • This transition directly impacts capital expenditure planning, forcing logistics providers to construct robust private charging networks alongside their traditional terminals. By integrating predictive maintenance analytics and advanced engine diagnostics, organizations have successfully achieved a 30% reduction in unprogrammed vehicle downtime, significantly boosting operational reliability.
  • The widespread adoption of cloud native transportation management software further supports this shift, enabling seamless coordination across complex intermodal networks. Additionally, the strategic use of telematics asset tracking and internet of things sensor arrays provides granular visibility into cargo conditions, effectively mitigating risks associated with temperature-sensitive freight.
  • As autonomous highway platooning transitions from pilot testing to commercial viability, carriers that aggressively align their technology investments with environmental mandates will secure a dominant competitive advantage.

What are the Key Data Covered in this Road Logistics Market Research and Growth Report?

  • What is the expected growth of the Road Logistics Market between 2026 and 2030?

    • USD 800 billion, at a CAGR of 3.4%

  • What segmentation does the market report cover?

    • The report is segmented by Application (Domestic, and International), Type (Truckload, Less than truckload, Parcel, and Same day), End-user (Manufacturing, Retail, Automotive, Healthcare, and Others) and Geography (APAC, North America, Europe, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • APAC, North America, Europe, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Expansion and demand for rapid last-mile delivery, High driver shortages and demographics aging

  • Who are the major players in the Road Logistics Market?

    • Agility Global PLC, AP Moller Maersk AS, ArcBest Corp., C H Robinson Worldwide Inc., CEVA Logistics SA, Dachser SE, DB Schenker, DHL International GmbH, DSV AS, Estes Express Lines, FedEx Corp., GEODIS, Hellmann Worldwide Logistics, JB Hunt Transport Services, Kuehne Nagel Management AG, Landstar System Inc., Mainfreight Ltd., Nippon Express Holdings Inc., Rhenus SE and Co. KG, Schneider National Inc., TFI International Inc., Toll Holdings Ltd., United Parcel Service Inc., XPO Inc. and Yusen Logistics Co. Ltd.

Market Research Insights

  • The Road Logistics Market is undergoing a fundamental operational transformation driven by digital integration and sustainability imperatives. Fleet operators are heavily investing in fleet charging infrastructure to comply with stringent urban low emission zones, achieving a 15% reduction in lifecycle energy costs.
  • Furthermore, the integration of automated freight routing workflows significantly minimizes empty backhaul mileage, leading to a 25% improvement in overall capacity utilization rates. Transportation providers leverage smart thermal packaging for sensitive shipments, effectively reducing cargo spoilage incidents by 18%.
  • By modernizing these core logistical frameworks, enterprise carriers can seamlessly navigate seasonal volume fluctuations and maintain superior service reliability across high-density trade corridors.

We can help! Our analysts can customize this road logistics market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ billion)
Data Table on Global - Market size and forecast 2025-2030 ($ billion)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Road Logistics Market 2020 - 2024

Historic Market Size - Data Table on Global Road Logistics Market 2020 - 2024 ($ billion)

5.2 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ billion)

5.3 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ billion)

5.4 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ billion)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ billion)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ billion)

6. Qualitative Analysis

6.1 Impact of AI in Global Road Logistics Market

6.2 Impact of Geopolitical Conflicts on Global Road Logistics Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Application

8.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

8.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

8.3 Domestic - Market size and forecast 2025-2030

Chart on Domestic - Market size and forecast 2025-2030 ($ billion)
Data Table on Domestic - Market size and forecast 2025-2030 ($ billion)
Chart on Domestic - Year-over-year growth 2025-2030 (%)
Data Table on Domestic - Year-over-year growth 2025-2030 (%)

8.4 International - Market size and forecast 2025-2030

Chart on International - Market size and forecast 2025-2030 ($ billion)
Data Table on International - Market size and forecast 2025-2030 ($ billion)
Chart on International - Year-over-year growth 2025-2030 (%)
Data Table on International - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Application

Market opportunity by Application ($ billion)
Data Table on Market opportunity by Application ($ billion)

9. Market Segmentation by Type

9.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

9.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

9.3 Truckload - Market size and forecast 2025-2030

Chart on Truckload - Market size and forecast 2025-2030 ($ billion)
Data Table on Truckload - Market size and forecast 2025-2030 ($ billion)
Chart on Truckload - Year-over-year growth 2025-2030 (%)
Data Table on Truckload - Year-over-year growth 2025-2030 (%)

9.4 Less than truckload - Market size and forecast 2025-2030

Chart on Less than truckload - Market size and forecast 2025-2030 ($ billion)
Data Table on Less than truckload - Market size and forecast 2025-2030 ($ billion)
Chart on Less than truckload - Year-over-year growth 2025-2030 (%)
Data Table on Less than truckload - Year-over-year growth 2025-2030 (%)

9.5 Parcel - Market size and forecast 2025-2030

Chart on Parcel - Market size and forecast 2025-2030 ($ billion)
Data Table on Parcel - Market size and forecast 2025-2030 ($ billion)
Chart on Parcel - Year-over-year growth 2025-2030 (%)
Data Table on Parcel - Year-over-year growth 2025-2030 (%)

9.6 Same day - Market size and forecast 2025-2030

Chart on Same day - Market size and forecast 2025-2030 ($ billion)
Data Table on Same day - Market size and forecast 2025-2030 ($ billion)
Chart on Same day - Year-over-year growth 2025-2030 (%)
Data Table on Same day - Year-over-year growth 2025-2030 (%)

9.7 Market opportunity by Type

Market opportunity by Type ($ billion)
Data Table on Market opportunity by Type ($ billion)

10. Market Segmentation by End-user

10.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

10.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

10.3 Manufacturing - Market size and forecast 2025-2030

Chart on Manufacturing - Market size and forecast 2025-2030 ($ billion)
Data Table on Manufacturing - Market size and forecast 2025-2030 ($ billion)
Chart on Manufacturing - Year-over-year growth 2025-2030 (%)
Data Table on Manufacturing - Year-over-year growth 2025-2030 (%)

10.4 Retail - Market size and forecast 2025-2030

Chart on Retail - Market size and forecast 2025-2030 ($ billion)
Data Table on Retail - Market size and forecast 2025-2030 ($ billion)
Chart on Retail - Year-over-year growth 2025-2030 (%)
Data Table on Retail - Year-over-year growth 2025-2030 (%)

10.5 Automotive - Market size and forecast 2025-2030

Chart on Automotive - Market size and forecast 2025-2030 ($ billion)
Data Table on Automotive - Market size and forecast 2025-2030 ($ billion)
Chart on Automotive - Year-over-year growth 2025-2030 (%)
Data Table on Automotive - Year-over-year growth 2025-2030 (%)

10.6 Healthcare - Market size and forecast 2025-2030

Chart on Healthcare - Market size and forecast 2025-2030 ($ billion)
Data Table on Healthcare - Market size and forecast 2025-2030 ($ billion)
Chart on Healthcare - Year-over-year growth 2025-2030 (%)
Data Table on Healthcare - Year-over-year growth 2025-2030 (%)

10.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ billion)
Data Table on Others - Market size and forecast 2025-2030 ($ billion)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.8 Market opportunity by End-user

Market opportunity by End-user ($ billion)
Data Table on Market opportunity by End-user ($ billion)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ billion)
Data Table on APAC - Market size and forecast 2025-2030 ($ billion)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ billion)
Data Table on China - Market size and forecast 2025-2030 ($ billion)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ billion)
Data Table on India - Market size and forecast 2025-2030 ($ billion)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ billion)
Data Table on Japan - Market size and forecast 2025-2030 ($ billion)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ billion)
Data Table on South Korea - Market size and forecast 2025-2030 ($ billion)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ billion)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ billion)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.3.6 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ billion)
Data Table on Australia - Market size and forecast 2025-2030 ($ billion)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.4 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ billion)
Data Table on North America - Market size and forecast 2025-2030 ($ billion)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.4.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ billion)
Data Table on US - Market size and forecast 2025-2030 ($ billion)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.4.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ billion)
Data Table on Canada - Market size and forecast 2025-2030 ($ billion)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.4.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ billion)
Data Table on Mexico - Market size and forecast 2025-2030 ($ billion)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ billion)
Data Table on Europe - Market size and forecast 2025-2030 ($ billion)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ billion)
Data Table on Germany - Market size and forecast 2025-2030 ($ billion)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ billion)
Data Table on UK - Market size and forecast 2025-2030 ($ billion)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ billion)
Data Table on France - Market size and forecast 2025-2030 ($ billion)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ billion)
Data Table on Italy - Market size and forecast 2025-2030 ($ billion)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ billion)
Data Table on Spain - Market size and forecast 2025-2030 ($ billion)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ billion)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ billion)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ billion)
Data Table on South America - Market size and forecast 2025-2030 ($ billion)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ billion)
Data Table on Brazil - Market size and forecast 2025-2030 ($ billion)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ billion)
Data Table on Argentina - Market size and forecast 2025-2030 ($ billion)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ billion)
Data Table on Chile - Market size and forecast 2025-2030 ($ billion)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ billion)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ billion)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ billion)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ billion)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ billion)
Data Table on UAE - Market size and forecast 2025-2030 ($ billion)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ billion)
Data Table on South Africa - Market size and forecast 2025-2030 ($ billion)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ billion)
Data Table on Turkey - Market size and forecast 2025-2030 ($ billion)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ billion)
Data Table on Israel - Market size and forecast 2025-2030 ($ billion)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ billion)
Data Tables on Market opportunity by geography ($ billion)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Expansion and demand for rapid last-mile delivery
Integration of smart technologies and autonomous fleet solutions
Expansion of industrial manufacturing and nearshoring supply chains

13.2 Market challenges

High driver shortages and demographics aging
Volatile fuel costs and environmental compliance pressure
Geopolitical instability and fragmented cross-border trade regulations

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Accelerated transition to zero-emission commercial fleets
Data-driven digital transformation and AI-powered orchestration
Regionalization of global supply chains and transport dynamics

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Agility Global PLC

Agility Global PLC - Overview
Agility Global PLC - Business segments
Agility Global PLC - Key offerings
Agility Global PLC - Segment focus
SWOT

15.5 AP Moller Maersk AS

AP Moller Maersk AS - Overview
AP Moller Maersk AS - Business segments
AP Moller Maersk AS - Key news
AP Moller Maersk AS - Key offerings
AP Moller Maersk AS - Segment focus
SWOT

15.6 C H Robinson Worldwide Inc.

C H Robinson Worldwide Inc. - Overview
C H Robinson Worldwide Inc. - Business segments
C H Robinson Worldwide Inc. - Key news
C H Robinson Worldwide Inc. - Key offerings
C H Robinson Worldwide Inc. - Segment focus
SWOT

15.7 DHL International GmbH

DHL International GmbH - Overview
DHL International GmbH - Business segments
DHL International GmbH - Key news
DHL International GmbH - Key offerings
DHL International GmbH - Segment focus
SWOT

15.8 DSV AS

DSV AS - Overview
DSV AS - Business segments
DSV AS - Key offerings
DSV AS - Segment focus
SWOT

15.9 Estes Express Lines

Estes Express Lines - Overview
Estes Express Lines - Product / Service
Estes Express Lines - Key offerings
SWOT

15.10 FedEx Corp.

FedEx Corp. - Overview
FedEx Corp. - Business segments
FedEx Corp. - Key news
FedEx Corp. - Key offerings
FedEx Corp. - Segment focus
SWOT

15.11 JB Hunt Transport Services

JB Hunt Transport Services - Overview
JB Hunt Transport Services - Business segments
JB Hunt Transport Services - Key offerings
JB Hunt Transport Services - Segment focus
SWOT

15.12 Kuehne Nagel Management AG

Kuehne Nagel Management AG - Overview
Kuehne Nagel Management AG - Business segments
Kuehne Nagel Management AG - Key news
Kuehne Nagel Management AG - Key offerings
Kuehne Nagel Management AG - Segment focus
SWOT

15.13 Nippon Express Holdings Inc.

Nippon Express Holdings Inc. - Overview
Nippon Express Holdings Inc. - Business segments
Nippon Express Holdings Inc. - Key offerings
Nippon Express Holdings Inc. - Segment focus
SWOT

15.14 Schneider National Inc.

Schneider National Inc. - Overview
Schneider National Inc. - Business segments
Schneider National Inc. - Key offerings
Schneider National Inc. - Segment focus
SWOT

15.15 Toll Holdings Ltd.

Toll Holdings Ltd. - Overview
Toll Holdings Ltd. - Product / Service
Toll Holdings Ltd. - Key offerings
SWOT

15.16 United Parcel Service Inc.

United Parcel Service Inc. - Overview
United Parcel Service Inc. - Business segments
United Parcel Service Inc. - Key offerings
United Parcel Service Inc. - Segment focus
SWOT

15.17 XPO Inc.

XPO Inc. - Overview
XPO Inc. - Business segments
XPO Inc. - Key offerings
XPO Inc. - Segment focus
SWOT

15.18 Yusen Logistics Co. Ltd.

Yusen Logistics Co. Ltd. - Overview
Yusen Logistics Co. Ltd. - Product / Service
Yusen Logistics Co. Ltd. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Road Logistics market growth will increase by USD 800.0 billion during 2026-2030.

The Road Logistics market is expected to grow at a CAGR of 3.4% during 2026-2030.

Road Logistics market is segmented by Application (Domestic, International) Type (Truckload, Less than truckload, Parcel, Same day) End-user (Manufacturing, Retail, Automotive, Healthcare, Others)

Agility Global PLC, AP Moller Maersk AS, ArcBest Corp., C H Robinson Worldwide Inc., CEVA Logistics SA, Dachser SE, DB Schenker, DHL International GmbH, DSV AS, Estes Express Lines, FedEx Corp., GEODIS, Hellmann Worldwide Logistics, JB Hunt Transport Services, Kuehne Nagel Management AG, Landstar System Inc., Mainfreight Ltd., Nippon Express Holdings Inc., Rhenus SE and Co. KG, Schneider National Inc., TFI International Inc., Toll Holdings Ltd., United Parcel Service Inc., XPO Inc., Yusen Logistics Co. Ltd. are a few of the key vendors in the Road Logistics market.

APAC will register the highest growth rate of 53.9% among the other regions. Therefore, the Road Logistics market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, India, Japan, South Korea, Indonesia, Australia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Turkey, Israel

  • Expansion and demand for rapid last-mile delivery is the driving factor this market.

The Road Logistics market vendors should focus on grabbing business opportunities from the Application segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
