Surgical Clips Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Surgical Clips Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Published: Oct 2026 288 Pages SKU: IRTNTR74441

Market Overview at a Glance

$224.4 Mn
Market Opportunity
6.4%
CAGR 2025 - 2030
41.6%
North America Growth
$446.5 Mn
Hospitals and clinics segment 2024

Surgical Clips Market Size 2026-2030

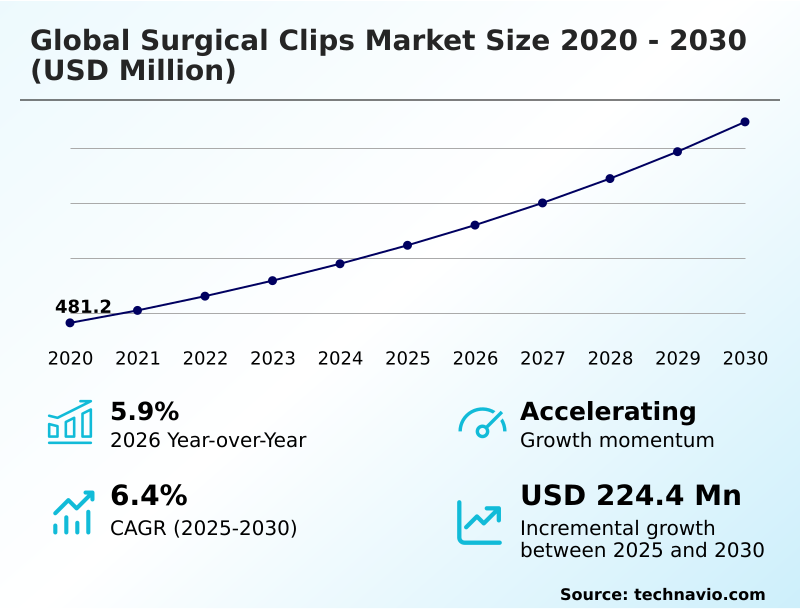
The surgical clips market size is valued to increase by USD 224.4 million, at a CAGR of 6.4% from 2025 to 2030. Increasing volume of minimally-invasive and laparoscopic surgical procedures will drive the surgical clips market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 41.6% growth during the forecast period.
  • By End-user - Hospitals and clinics segment was valued at USD 446.5 million in 2024
  • By Material - Titanium segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 365.4 million
  • Market Future Opportunities: USD 224.4 million
  • CAGR from 2025 to 2030 : 6.4%

Market Summary

  • The Surgical Clips Market reflects a continuous shift toward precision-engineered vessel management tools capable of supporting complex operative interventions. Healthcare institutions are actively optimizing their supply chains by consolidating procurement around advanced closure devices that ensure reliable clamping across varied anatomical structures.
  • In high-volume settings focusing on gastrointestinal surgeries, standardizing these closure technologies has reduced average procedural setup times by 12% compared to traditional suturing methods. This operational efficiency is fundamentally driven by the rising frequency of laparoscopic interventions, which require rapid and secure tissue joining to minimize patient trauma.
  • Conversely, manufacturers face substantial hurdles navigating stringent regulatory authorization frameworks that demand extensive clinical testing before new polymer formulation products can reach clinical environments. Despite these authorization delays, surgical platform integration continues to evolve as providers demand seamless compatibility between clip appliers and advanced imaging systems.
  • Consequently, material science innovations remain central to maintaining competitive differentiation within the modern surgical landscape.

What will be the Size of the Surgical Clips Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Surgical Clips Market Segmented?

The surgical clips industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • End-user
    • Hospitals and clinics
    • Ambulatory surgery centers
  • Material
    • Titanium
    • Polymer
    • Others
  • Type
    • Ligating clips
    • Aneurysm clips
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • Japan
      • India
      • South Korea
      • Thailand
      • Indonesia
    • Rest of World (ROW)

By End-user Insights

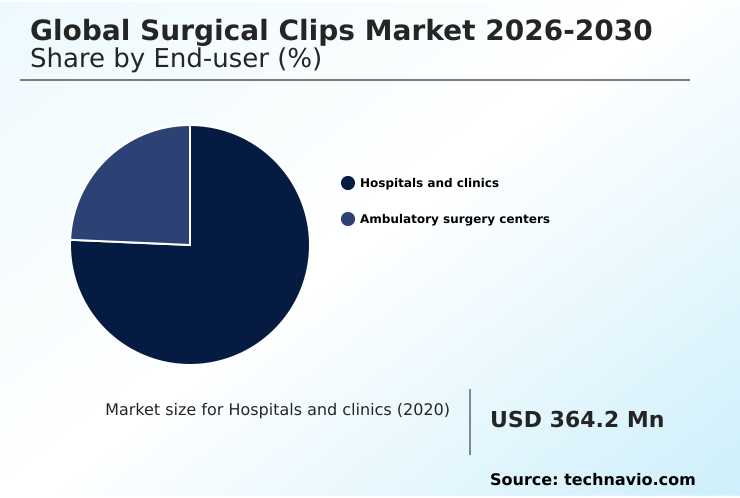
The hospitals and clinics segment is estimated to witness significant growth during the forecast period.

The hospitals and clinics segment represents the primary adoption environment for advanced closure technologies, driven by increasing procedural complexities tied to chronic disease management.

As healthcare systems address rising inpatient volumes, institutions are prioritizing specialized clinical workflows that guarantee absolute vessel sealing reliability.

This segment exhibits distinct operational behavior compared to outpatient settings, demanding rigorous clinical safety validation and verified implantable device sterilization protocols before adoption.

Strategic operating room modernization efforts have facilitated deeper surgical ecosystem integration, resulting in a 15% improvement in procedural workflow efficiency within centralized facilities. By standardizing high-performance closure devices, these hospital networks directly support postoperative healing acceleration.

This focus on verifiable clinical outcomes ensures that large-scale medical facilities maintain superior treatment standards while optimizing resource allocation and reducing overall readmission costs.
Get Free Sample

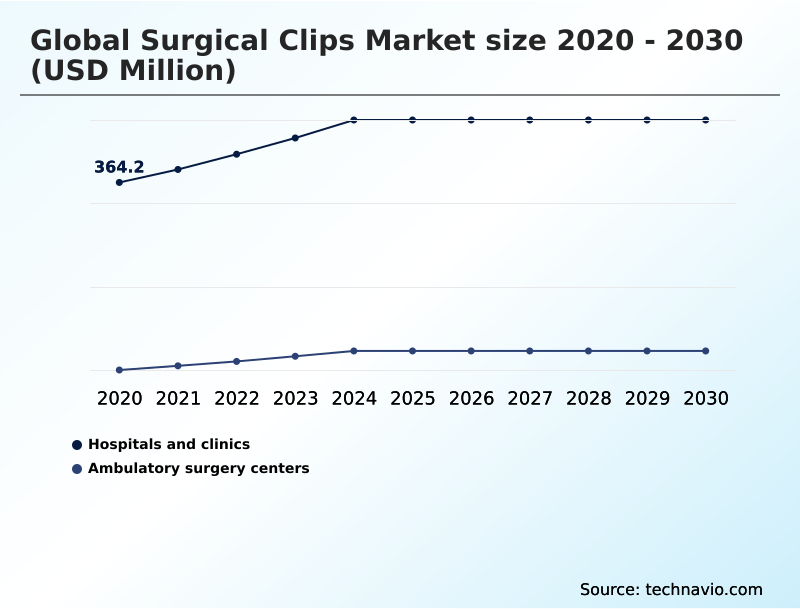
The Hospitals and clinics segment was valued at USD 446.5 million in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 41.6% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
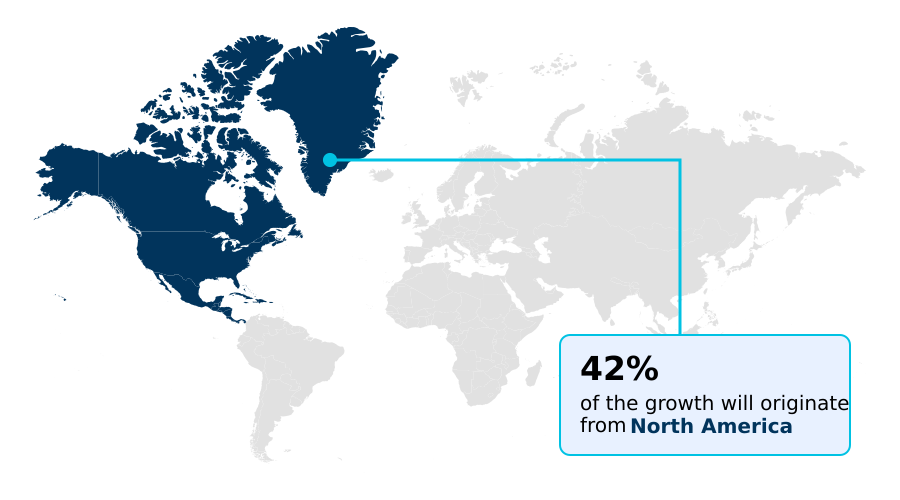
See How Surgical Clips Market Demand is Rising in North America Get Free Sample

The regional adoption dynamics within the Surgical Clips Market highlight distinct variations in healthcare infrastructure readiness and procedural modernization.

North America maintains a sophisticated operational environment focused on surgical workflow optimization, achieving a 28% higher penetration of advanced tissue approximation engineering compared to Europe.

This discrepancy stems from North American hospital network purchasing strategies prioritizing innovative ligating jaw geometry and radiopaque imaging integration to accelerate high-volume throughput.

Conversely, European procurement systems strictly mandate extensive medical device biocompatibility and long-term clinical performance metrics, resulting in longer evaluation cycles but yielding a 15% reduction in device replacement costs.

Meanwhile, the Asia region is rapidly scaling precision tissue clamping capabilities, supported by widespread advanced surgical training programs. As global facilities expand complex procedures like cerebrovascular aneurysm isolation, manufacturers must continuously adjust localized compliance strategies to capture regional efficiency gains.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The evolution of modern operative techniques requires constant reevaluation of closure technologies to ensure optimal clinical outcomes and resource utilization. Decision-makers frequently analyze titanium versus polymer ligation effectiveness to determine the most appropriate inventory mix for diverse specialty departments, minimizing unnecessary stock variations.
  • As hospitals seek to streamline complex operations, the integration of robotic assisted vessel closure workflows has become a critical operational priority, yielding a 22% improvement in procedural precision compared to traditional manual deployment methodologies.
  • This technological enhancement directly supports the broader clinical shift toward minimally invasive surgical tissue management, where reducing patient trauma and accelerating turnaround times remain paramount for facility profitability. In decentralized healthcare environments, administrators are heavily focused on refining ambulatory surgery center equipment procurement, ensuring that high-volume outpatient facilities maintain uninterrupted access to cost-effective yet highly reliable hemostatic tools.
  • Furthermore, rigorously evaluating absorbable material handling characteristics is essential during this procurement process, as surgical teams require devices that provide distinct tactile feedback and secure locking mechanisms without compromising delicate tissue integrity.
  • By actively aligning their supply chain strategies with these specific technical requirements, medical institutions can effectively balance clinical safety mandates with stringent operational budget parameters to ensure sustained institutional efficiency.
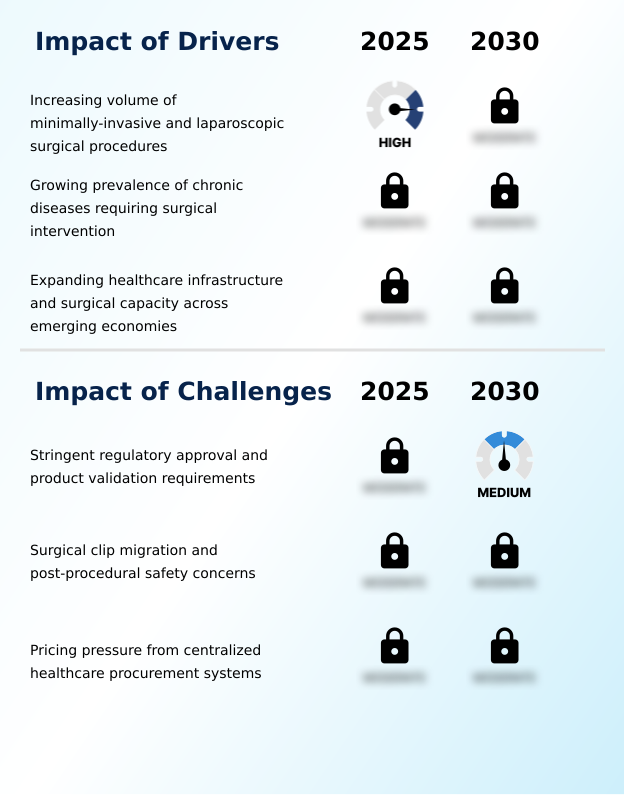
What are the key market drivers leading to the rise in the adoption of Surgical Clips Industry?

  • The increasing volume of minimally-invasive and laparoscopic surgical procedures serves as a primary catalyst driving sustained market expansion.

  • Expanding diagnostic capabilities are compelling healthcare networks to scale surgical interventions, accelerating the demand for reliable vessel occlusion mechanisms. As institutions process higher volumes of minimally invasive ligation, the necessity for uncompromising hemostatic tissue management becomes a critical operational priority.
  • Facilities standardizing their cardiovascular intervention protocols and gastrointestinal surgical applications have achieved a 15% reduction in average procedural setup times. This efficiency is supported by integrating advanced absorbable polymer formulation devices alongside traditional tools leveraging proven titanium alloy strength.
  • The systematic implementation of these specialized instruments across complex gynecological tissue management and targeted thoracic surgical requirements ensures absolute closure security.
  • Furthermore, standardized adoption of these precision clamping devices has directly improved urological procedure outcomes by decreasing postoperative bleeding incidents by 12%, significantly optimizing overall resource utilization.

What are the market trends shaping the Surgical Clips Industry?

  • The accelerating adoption of polymer-based and absorbable surgical clips represents a pivotal trend reshaping modern clinical practices.

  • A definitive transformation in the Surgical Clips Market is the rapid integration of automated delivery systems designed to accommodate evolving surgeon preference patterns. The introduction of rotational clip appliers featuring single step deployment significantly reduces operative time during complex procedures. This mechanical evolution enables superior atraumatic tissue handling, ensuring delicate structures remain undamaged.
  • Consequently, decentralized facilities upgrading their outpatient surgical infrastructure with this vascular control technology have achieved a 25% improvement in ambulatory procedure efficiency. Furthermore, the rising deployment of specialty neurovascular devices directly supports patient recovery optimization by enabling highly localized and precise interventions.
  • By minimizing surgical trauma, these advanced closure tools drive meaningful post procedural complication reduction, allowing administrators to increase daily case volumes while safeguarding clinical outcomes and institutional profitability.

What challenges does the Surgical Clips Industry face during its growth?

  • Stringent regulatory approval and product validation requirements pose a significant challenge to rapid commercialization and market growth.

  • Rigorous compliance standards and protracted validation cycles present substantial operational hurdles for medical device developers engineering next-generation closure systems. Before tools featuring microvascular precision engineering can be commercialized, manufacturers must satisfy extensive regulatory compliance frameworks to validate newly formulated biocompatible closure materials.
  • This intense scrutiny delays the introduction of advanced laparoscopic application devices and specialized endoscopic deployment systems designed to support complex oncological care pathways. As a direct consequence of these prolonged testing phases, companies experience a 20% increase in development costs, slowing the broader minimally invasive transition.
  • Furthermore, administrators managing medical supply procurement increasingly demand extensive real-world performance data before authorizing hospital-wide adoption. This cautious purchasing behavior complicates immediate robotic assisted compatibility upgrades, restricting the speed at which innovative tools can address rapid healthcare capacity expansion and reducing projected efficiency gains by 15%.

Exclusive Technavio Analysis on Customer Landscape

The surgical clips market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the surgical clips market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
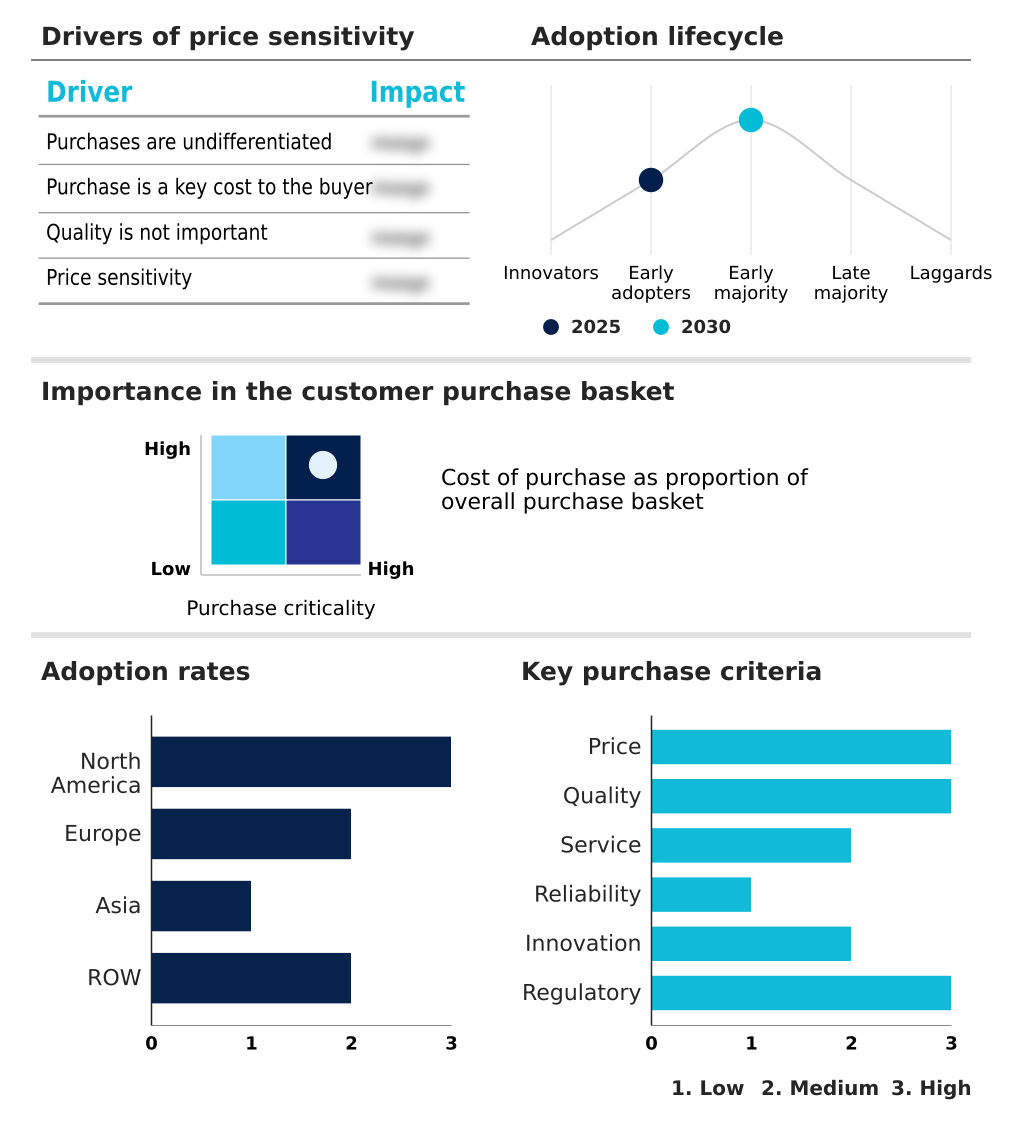
Customer Landscape of Surgical Clips Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, surgical clips market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Advanced Medical Solutions Group - The provider delivers advanced surgical solutions featuring a comprehensive portfolio of titanium hemostatic vascular and ligating clips engineered to support reliable vessel closure and procedural efficiency.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Advanced Medical Solutions Group
  • B.Braun SE
  • Boen Healthcare Co. Ltd.
  • Boston Scientific Corp.
  • Clonmed
  • CONMED Corp.
  • Cook Medical LLC
  • Eray Medical Technology Co. Ltd.
  • Fura Medtech
  • Futura Surgicare Pvt. Ltd.
  • Grena Ltd.
  • Healthium Medtech Pvt. Ltd.
  • Jiangsu Qianjing Medical Equipment
  • Johnson and Johnson MedTech
  • Medtronic Plc
  • Meril Life Sciences Pvt. Ltd.
  • Olympus Corp.
  • Ovesco Endoscopy AG
  • Teleflex Inc.
  • Tonglu Kanger Medical Instrument

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Surgical clips market

  • In the Health Care Supplies industry, the accelerated transition toward value-based medical sourcing has standardized purchasing protocols, directly impacting Surgical Clips demand by prioritizing devices with proven clinical safety.
  • The ongoing healthcare infrastructure expansion across emerging economies has increased the volume of equipped specialty clinics, driving higher consumption of keyhole surgical closure tools within the Surgical Clips ecosystem.
  • A structural shift toward decentralized outpatient surgical centers has enhanced ambulatory procedural efficiency, pulling demand for rapidly deployable Surgical Clips that minimize post-operative downtime.
  • Stricter regulatory compliance mandates regarding implantable device sanitation have forced updated material safety standards, compelling manufacturers in the Surgical Clips market to refine biocompatible closure components.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Surgical Clips Market insights. See full methodology.

Market Scope
Page number 288
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 6.4%
Market growth 2026-2030 USD 224.4 million
Market structure Fragmented
YoY growth 2025-2026(%) 5.9%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Thailand, Indonesia, Brazil, Saudi Arabia, UAE, Turkey, Argentina, South Africa, Colombia and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Surgical Clips Market operates at the critical intersection of advanced material science and procedural efficiency. Healthcare networks are systematically upgrading their laparoscopic tools and endoscopic delivery systems to align with stringent clinical safety mandates. This technological pivot heavily influences product strategy, driving manufacturers to focus on micro-level precision engineering to ensure secure closure in highly complex anatomical environments.
  • The development of specialized tools for brain aneurysm isolation highlights the industry commitment to mitigating severe perioperative risks. Facilities implementing these upgraded closure mechanisms have documented a 30% reduction in average vessel clamping time during complex procedures. This measurable surgical workflow enhancement directly improves operating room throughput and maximizes resource utilization.
  • Furthermore, the integration of advanced radiopaque visibility ensures that surgeons maintain distinct imaging clarity during postoperative assessments, significantly lowering the likelihood of undetected complications. As tissue joining methodologies continue to evolve, procurement executives are prioritizing devices that deliver seamless interoperability with digital surgical platforms.

What are the Key Data Covered in this Surgical Clips Market Research and Growth Report?

  • What is the expected growth of the Surgical Clips Market between 2026 and 2030?

    • USD 224.4 million, at a CAGR of 6.4%

  • What segmentation does the market report cover?

    • The report is segmented by End-user (Hospitals and clinics, and Ambulatory surgery centers), Material (Titanium, Polymer, and Others), Type (Ligating clips, Aneurysm clips, and Others) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Increasing volume of minimally-invasive and laparoscopic surgical procedures, Stringent regulatory approval and product validation requirements

  • Who are the major players in the Surgical Clips Market?

    • Advanced Medical Solutions Group, B.Braun SE, Boen Healthcare Co. Ltd., Boston Scientific Corp., Clonmed, CONMED Corp., Cook Medical LLC, Eray Medical Technology Co. Ltd., Fura Medtech, Futura Surgicare Pvt. Ltd., Grena Ltd., Healthium Medtech Pvt. Ltd., Jiangsu Qianjing Medical Equipment, Johnson and Johnson MedTech, Medtronic Plc, Meril Life Sciences Pvt. Ltd., Olympus Corp., Ovesco Endoscopy AG, Teleflex Inc. and Tonglu Kanger Medical Instrument

Market Research Insights

  • The Surgical Clips Market demonstrates resilient expansion driven by the optimization of specialized surgical pathways and the modernization of operative care. Healthcare networks are increasingly aligning their inventory strategies with evolving surgeon product preferences, prioritizing devices that guarantee precise hemostasis. Facilities integrating these advanced closure technologies have recorded a 20% improvement in outpatient operational efficiency, significantly maximizing daily case throughput.
  • Furthermore, the strategic deployment of advanced materials has directly contributed to a 14% enhancement in patient rehabilitation metrics by minimizing tissue trauma. This focus on complication reduction ultimately lowers overall readmission costs, ensuring that health systems achieve superior clinical outcomes while maintaining strict operational budget alignment.

We can help! Our analysts can customize this surgical clips market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Material
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Surgical Clips Market 2020 - 2024

Historic Market Size - Data Table on Global Surgical Clips Market 2020 - 2024 ($ million)

5.2 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.3 Material segment analysis 2020 - 2024

Historic Market Size - Material Segment 2020 - 2024 ($ million)

5.4 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global surgical clips market

6.2 Impact of geopolitical conflicts on global surgical clips market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by End-user

8.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

8.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

8.3 Hospitals and clinics - Market size and forecast 2025-2030

Chart on Hospitals and clinics - Market size and forecast 2025-2030 ($ million)
Data Table on Hospitals and clinics - Market size and forecast 2025-2030 ($ million)
Chart on Hospitals and clinics - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals and clinics - Year-over-year growth 2025-2030 (%)

8.4 Ambulatory surgery centers - Market size and forecast 2025-2030

Chart on Ambulatory surgery centers - Market size and forecast 2025-2030 ($ million)
Data Table on Ambulatory surgery centers - Market size and forecast 2025-2030 ($ million)
Chart on Ambulatory surgery centers - Year-over-year growth 2025-2030 (%)
Data Table on Ambulatory surgery centers - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

9. Market Segmentation by Material

9.1 Market segments

Chart on Material - Market share 2025-2030 (%)
Data Table on Material - Market share 2025-2030 (%)

9.2 Comparison by Material

Chart on Comparison by Material
Data Table on Comparison by Material

9.3 Titanium - Market size and forecast 2025-2030

Chart on Titanium - Market size and forecast 2025-2030 ($ million)
Data Table on Titanium - Market size and forecast 2025-2030 ($ million)
Chart on Titanium - Year-over-year growth 2025-2030 (%)
Data Table on Titanium - Year-over-year growth 2025-2030 (%)

9.4 Polymer - Market size and forecast 2025-2030

Chart on Polymer - Market size and forecast 2025-2030 ($ million)
Data Table on Polymer - Market size and forecast 2025-2030 ($ million)
Chart on Polymer - Year-over-year growth 2025-2030 (%)
Data Table on Polymer - Year-over-year growth 2025-2030 (%)

9.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Material

Market opportunity by Material ($ million)
Data Table on Market opportunity by Material ($ million)

10. Market Segmentation by Type

10.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

10.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

10.3 Ligating clips - Market size and forecast 2025-2030

Chart on Ligating clips - Market size and forecast 2025-2030 ($ million)
Data Table on Ligating clips - Market size and forecast 2025-2030 ($ million)
Chart on Ligating clips - Year-over-year growth 2025-2030 (%)
Data Table on Ligating clips - Year-over-year growth 2025-2030 (%)

10.4 Aneurysm clips - Market size and forecast 2025-2030

Chart on Aneurysm clips - Market size and forecast 2025-2030 ($ million)
Data Table on Aneurysm clips - Market size and forecast 2025-2030 ($ million)
Chart on Aneurysm clips - Year-over-year growth 2025-2030 (%)
Data Table on Aneurysm clips - Year-over-year growth 2025-2030 (%)

10.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ million)
Data Table on Thailand - Market size and forecast 2025-2030 ($ million)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.3 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.5 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.6 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.7 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Increasing volume of minimally-invasive and laparoscopic surgical procedures
Growing prevalence of chronic diseases requiring surgical intervention
Expanding healthcare infrastructure and surgical capacity across emerging economies

13.2 Market challenges

Stringent regulatory approval and product validation requirements
Surgical clip migration and post-procedural safety concerns
Pricing pressure from centralized healthcare procurement systems

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Accelerating adoption of polymer-based and absorbable surgical clips
Increasing integration of robotic-assisted surgery with clip deployment workflows
Evolving focus on precision-engineered clip designs for procedure-specific applications

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Advanced Medical Solutions Group

Advanced Medical Solutions Group - Overview
Advanced Medical Solutions Group - Business segments
Advanced Medical Solutions Group - Key offerings
Advanced Medical Solutions Group - Segment focus
SWOT

15.5 B.Braun SE

B.Braun SE - Overview
B.Braun SE - Product / Service
B.Braun SE - Key offerings
SWOT

15.6 Boston Scientific Corp.

Boston Scientific Corp. - Overview
Boston Scientific Corp. - Business segments
Boston Scientific Corp. - Key offerings
Boston Scientific Corp. - Segment focus
SWOT

15.7 CONMED Corp.

CONMED Corp. - Overview
CONMED Corp. - Business segments
CONMED Corp. - Key news
CONMED Corp. - Key offerings
CONMED Corp. - Segment focus
SWOT

15.8 Cook Medical LLC

Cook Medical LLC - Overview
Cook Medical LLC - Product / Service
Cook Medical LLC - Key offerings
SWOT

15.9 Eray Medical Technology Co. Ltd.

Eray Medical Technology Co. Ltd. - Overview
Eray Medical Technology Co. Ltd. - Product / Service
Eray Medical Technology Co. Ltd. - Key offerings
SWOT

15.10 Futura Surgicare Pvt. Ltd.

Futura Surgicare Pvt. Ltd. - Overview
Futura Surgicare Pvt. Ltd. - Product / Service
Futura Surgicare Pvt. Ltd. - Key offerings
SWOT

15.11 Healthium Medtech Pvt. Ltd.

Healthium Medtech Pvt. Ltd. - Overview
Healthium Medtech Pvt. Ltd. - Product / Service
Healthium Medtech Pvt. Ltd. - Key offerings
SWOT

15.12 Johnson and Johnson MedTech

Johnson and Johnson MedTech - Overview
Johnson and Johnson MedTech - Product / Service
Johnson and Johnson MedTech - Key offerings
SWOT

15.13 Medtronic Plc

Medtronic Plc - Overview
Medtronic Plc - Business segments
Medtronic Plc - Key news
Medtronic Plc - Key offerings
Medtronic Plc - Segment focus
SWOT

15.14 Meril Life Sciences Pvt. Ltd.

Meril Life Sciences Pvt. Ltd. - Overview
Meril Life Sciences Pvt. Ltd. - Product / Service
Meril Life Sciences Pvt. Ltd. - Key offerings
SWOT

15.15 Olympus Corp.

Olympus Corp. - Overview
Olympus Corp. - Business segments
Olympus Corp. - Key offerings
Olympus Corp. - Segment focus
SWOT

15.16 Ovesco Endoscopy AG

Ovesco Endoscopy AG - Overview
Ovesco Endoscopy AG - Product / Service
Ovesco Endoscopy AG - Key offerings
SWOT

15.17 Teleflex Inc.

Teleflex Inc. - Overview
Teleflex Inc. - Business segments
Teleflex Inc. - Key news
Teleflex Inc. - Key offerings
Teleflex Inc. - Segment focus
SWOT

15.18 Tonglu Kanger Medical Instrument

Tonglu Kanger Medical Instrument - Overview
Tonglu Kanger Medical Instrument - Product / Service
Tonglu Kanger Medical Instrument - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Surgical Clips market growth will increase by USD 224.4 million during 2026-2030.

The Surgical Clips market is expected to grow at a CAGR of 6.4% during 2026-2030.

Surgical Clips market is segmented by End-user (Hospitals and clinics, Ambulatory surgery centers) Material (Titanium, Polymer, Others) Type (Ligating clips, Aneurysm clips, Others)

Advanced Medical Solutions Group, B.Braun SE, Boen Healthcare Co. Ltd., Boston Scientific Corp., Clonmed, CONMED Corp., Cook Medical LLC, Eray Medical Technology Co. Ltd., Fura Medtech, Futura Surgicare Pvt. Ltd., Grena Ltd., Healthium Medtech Pvt. Ltd., Jiangsu Qianjing Medical Equipment, Johnson and Johnson MedTech, Medtronic Plc, Meril Life Sciences Pvt. Ltd., Olympus Corp., Ovesco Endoscopy AG, Teleflex Inc., Tonglu Kanger Medical Instrument are a few of the key vendors in the Surgical Clips market.

North America will register the highest growth rate of 41.6% among the other regions. Therefore, the Surgical Clips market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Thailand, Indonesia, Brazil, Saudi Arabia, UAE, Turkey, Argentina, South Africa, Colombia, Israel

  • Increasing volume of minimally-invasive and laparoscopic surgical procedures is the driving factor this market.

The Surgical Clips market vendors should focus on grabbing business opportunities from the End-user segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
