Surgical Sutures Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Turkey, Saudi Arabia, and South Africa), Rest of World (ROW)

Surgical Sutures Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Turkey, Saudi Arabia, and South Africa), Rest of World (ROW)

Published: Oct 2026 286 Pages SKU: IRTNTR45388

Market Overview at a Glance

$1.22 B
Market Opportunity
4.6%
CAGR 2025 - 2030
32.1%
North America Growth
$2.36 B
Absorbable surgical sutures segment 2024

Surgical Sutures Market Size 2026-2030

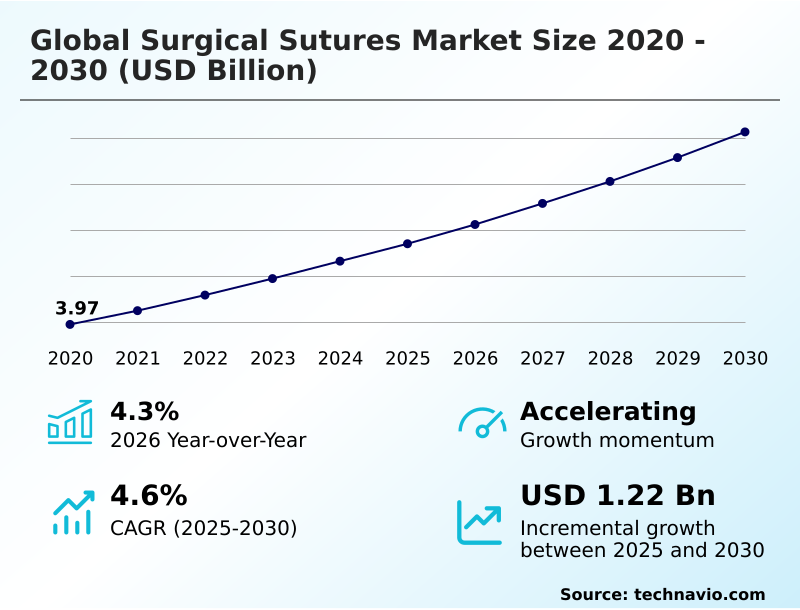
The surgical sutures market size is valued to increase by USD 1.22 billion, at a CAGR of 4.6% from 2025 to 2030. Rising volume of surgical procedures globally will drive the surgical sutures market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 32.1% growth during the forecast period.
  • By Product - Absorbable surgical sutures segment was valued at USD 2.36 billion in 2024
  • By End-user - Hospitals segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 2.10 billion
  • Market Future Opportunities: USD 1.22 billion
  • CAGR from 2025 to 2030 : 4.6%

Market Summary

  • The Surgical Sutures landscape demonstrates robust operational momentum due to continuous advancements in biomedical engineering and the escalating frequency of complex operative procedures. The demographic shift toward an aging population directly drives demand, as a higher prevalence of chronic cardiovascular and orthopedic conditions necessitates frequent surgical interventions.
  • To accommodate this demand, major hospital networks are streamlining their supply chain optimization strategies by transitioning to customized, procedure-specific sterile trays, which has successfully reduced surgical preparation times by 22% compared to traditional individual packaging methods. This operational pivot significantly enhances daily surgical throughput and lowers inventory waste.
  • However, the industry faces severe structural challenges from intense pricing pressures enforced by group purchasing organizations aiming to minimize per-capita healthcare expenditures. The commoditization of standard wound closure materials forces manufacturers to demonstrate undeniable clinical value to maintain profitability.
  • Despite these fiscal constraints, the relentless integration of advanced minimally invasive technologies ensures that specialized tissue approximation devices remain absolutely indispensable for modern clinical outcomes, driving continuous material innovation across the competitive landscape.

What will be the Size of the Surgical Sutures Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Surgical Sutures Market Segmented?

The surgical sutures industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product
    • Absorbable surgical sutures
    • Non-absorbable surgical sutures
    • Suture-assist devices
  • End-user
    • Hospitals
    • ASCs
    • Others
  • Product type
    • Coated sutures
    • Uncoated sutures
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • Japan
      • India
      • South Korea
      • Indonesia
      • Thailand
    • Rest of World (ROW)

By Product Insights

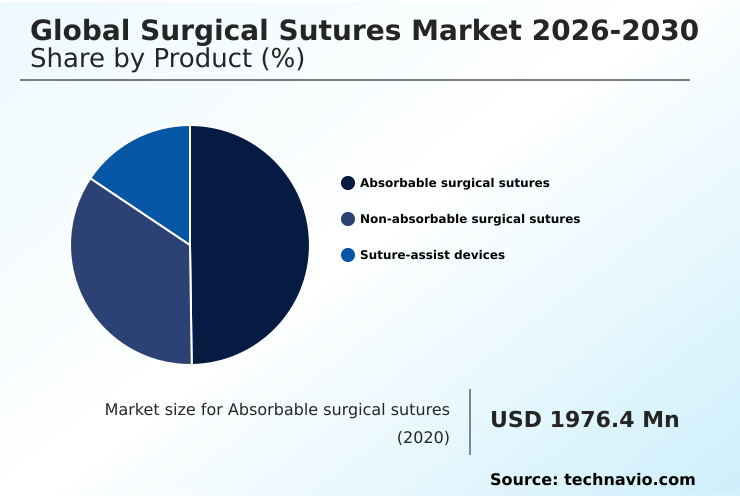
The absorbable surgical sutures segment is estimated to witness significant growth during the forecast period.

The absorbable segment of the Surgical Sutures industry is undergoing rapid technological transformation driven by advances in bioabsorbable material degradation and chemical hydrolysis breakdown.

Medical facilities increasingly rely on these solutions to eliminate secondary removal procedures, directly improving outpatient clinical throughput. Facilities adopting synthetic bioabsorbable wound closure methods have achieved a 15% reduction in average patient discharge times.

This efficiency stems from enhanced tensile strength retention and optimized enzymatic degradation profiles, ensuring prolonged mechanical tissue support during critical healing phases. The transition toward knotless barbed wound closure and polydioxanone structural integrity fundamentally changes wound margin adaptation.

Furthermore, integration with robotic assisted microsurgery tissue approximation streamlines operative workflows, allowing surgical teams to manage complex internal repairs with unprecedented reliability and structural consistency.
Get Free Sample

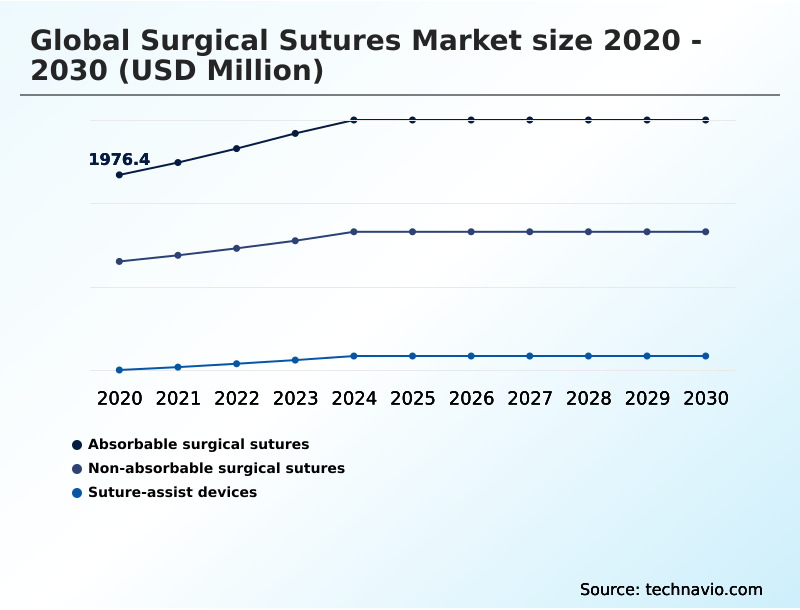
The Absorbable surgical sutures segment was valued at USD 2.36 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 32.1% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
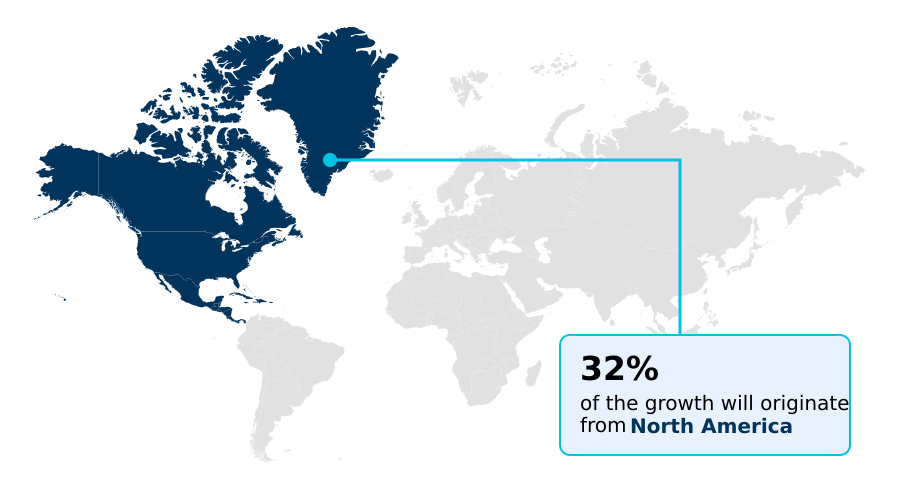
See How Surgical Sutures Market Demand is Rising in North America Get Free Sample

The regional dynamics of the Surgical Sutures sector highlight a stark contrast between North America and APAC.

North America maintains exceptional outpatient clinical efficiency, where a highly structured ambulatory surgery workflow has increased the adoption of advanced laparoscopic closure instruments by 28% compared to traditional inpatient methods.

Surgeons in this region heavily utilize cardiovascular anastomosis threads and orthopedic joint reinforcement tools to execute complex procedures rapidly.

Conversely, APAC demonstrates a rapid expansion in fundamental hospital infrastructure, leading to a 35% higher adoption rate of basic monofilament polypropylene and standard tissue approximation mechanisms to manage vast patient volumes.

While North American facilities focus on biocompatible polymer extrusion techniques to enhance dermal closure techniques and achieve postoperative complication reduction, APAC prioritizes supply chain scalability and localized manufacturing.

These distinct regional priorities force medical device manufacturers to deploy highly tailored product distribution strategies to optimize operational performance across diverse global healthcare frameworks.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The operational landscape of the Surgical Sutures sector is being fundamentally reshaped by continuous biomedical innovations and the urgent need for enhanced clinical workflow efficiency. Healthcare facilities are aggressively transitioning toward synthetic bioabsorbable wound closure methods to streamline postoperative care and reduce the administrative burden of follow-up appointments.
  • Simultaneously, the expanding utilization of antimicrobial coated surgical thread applications acts as a frontline defense against hospital-acquired infections, directly lowering long-term patient recovery costs. When hospital procurement teams assess supply chain reliability, facilities utilizing customized sterile procedural tray integration report a 40% improvement in inventory turnaround efficiency compared to institutions relying on disjointed component sourcing.
  • This optimized procurement strategy eliminates unnecessary packaging waste and accelerates operating room preparation. Furthermore, the rapid modernization of surgical suites has accelerated the adoption of robotic assisted microsurgery tissue approximation, allowing clinicians to perform complex maneuvers with unmatched precision in highly confined anatomical spaces.
  • This technological leap is heavily supported by knotless barbed continuous suturing techniques, which evenly distribute tension across the incision line and significantly curtail operative durations. By reducing the time patients spend under anesthesia, hospitals can safely increase their daily procedural volume, optimizing resource allocation without expanding their physical footprint.
  • Ultimately, these integrated advancements in biomaterials and automated closure mechanisms ensure that medical providers can meet the escalating demands of an aging demographic while maintaining strict adherence to value-based healthcare standards and rigorous patient safety protocols.
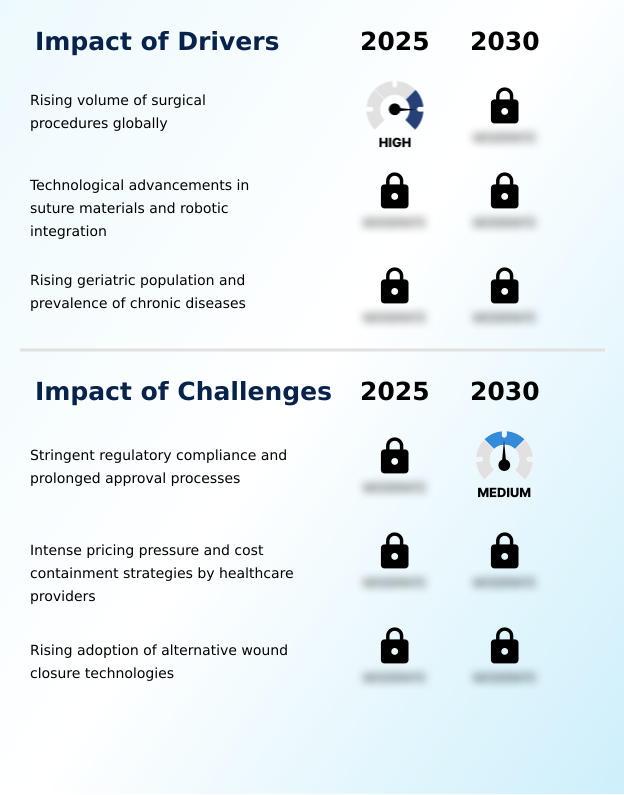
What are the key market drivers leading to the rise in the adoption of Surgical Sutures Industry?

  • The surging global volume of elective and emergency surgical procedures, driven by expanding healthcare access and an aging population, acts as the primary catalyst for the sustained expansion of the industry.

  • The sheer escalation in chronic disease surgical intervention and age related operative care acts as the predominant catalyst propelling the Surgical Sutures sector forward.
  • As global life expectancies rise, the necessity for geriatric tissue regeneration and high volume trauma care has driven a 40% surge in the utilization of specialized antimicrobial coated threads.
  • This demographic shift compels facilities to adopt minimally invasive operative protocols to accelerate patient recovery. The rapid proliferation of advanced robotic integration and automated suturing consoles empowers clinicians to execute highly complex repairs with unmatched precision.
  • Hospitals leveraging robotic assisted microsurgery needles report a 25% reduction in unintentional tissue trauma. By proactively prioritizing surgical site infection mitigation, medical device manufacturers provide the essential tools required to sustain the unprecedented volume of modern operative throughput safely.

What are the market trends shaping the Surgical Sutures Industry?

  • The increasing industry focus on environmental sustainability is driving a structural shift toward eco-friendly manufacturing practices and biodegradable packaging solutions. Consequently, healthcare procurement committees are actively prioritizing suppliers that integrate circular economy principles into their medical device production lifecycles.

  • The Surgical Sutures landscape is rapidly pivoting toward sustainable operational practices and extreme workflow optimization. Healthcare administrators are actively enforcing circular economy principles by demanding biodegradable sterile packaging, which has successfully reduced non-recyclable medical waste output by 35% in early-adopter facilities. This shift forces a complete reevaluation of biomedical polymer synthesis and sterile procedural packaging protocols.
  • Simultaneously, the push for surgical prep time optimization has accelerated the implementation of customized procedural trays. By standardizing inventory management standardization, surgical centers have achieved a 22% improvement in supply room efficiency, eliminating redundant stock and expired materials. To further safeguard against logistical bottlenecks, manufacturers are accelerating supply chain nearshoring and establishing a regionalized manufacturing footprint.
  • These strategic realignments ensure consistent access to critical synthetic absorbable polymers, completely insulating high-volume surgical centers from international shipping disruptions while aggressively driving down total procurement expenditures.

What challenges does the Surgical Sutures Industry face during its growth?

  • The necessity to navigate stringent regulatory compliance frameworks and prolonged product approval cycles imposes substantial operational and financial burdens on medical device manufacturers.

  • Stringent regulatory compliance auditing and exhaustive health economic evaluations severely constrain the rapid commercialization of novel wound closure devices within the Surgical Sutures sector. As institutions transition to value based care delivery, procurement committees demand incontrovertible clinical evidence that premium products lower long-term treatment costs, extending the average sales cycle by 30%.
  • Furthermore, the increasing clinical acceptance of alternative wound adhesives and mechanical stapling replacement actively displaces traditional polyglactin 910 and collagen based filaments in superficial procedures. The integration of hemostatic sealing integration has reduced the reliance on conventional threads for minor epidermal approximations by 18% in high-turnover clinics.
  • Balancing these intense competitive pressures with strict sterilization protocol adherence and hospital infection control mandates forces manufacturers to continuously absorb escalating research and operational expenditures.

Exclusive Technavio Analysis on Customer Landscape

The surgical sutures market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the surgical sutures market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
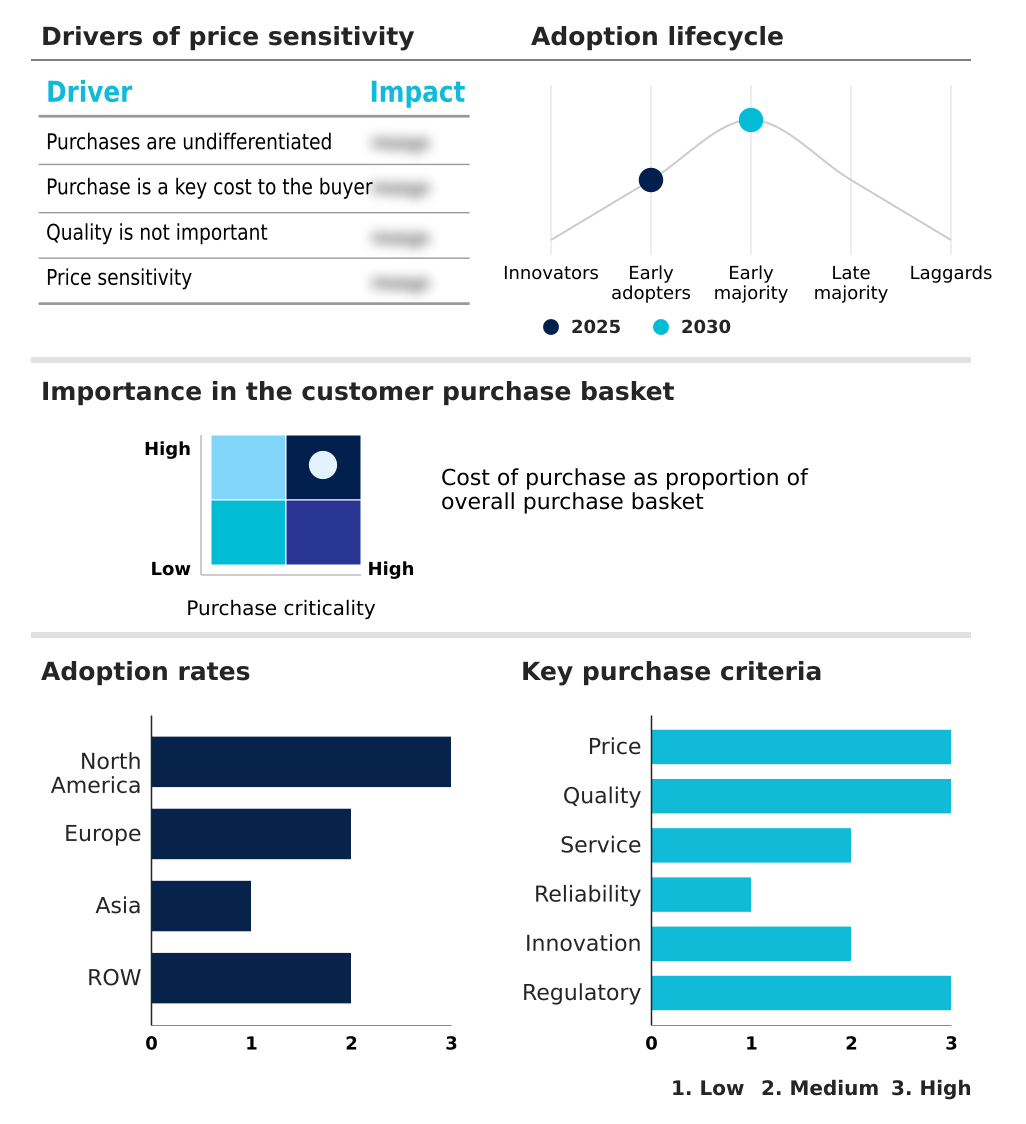
Customer Landscape of Surgical Sutures Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, surgical sutures market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

ASSUT EUROPE SpA - Advanced synthetic absorbable and non-absorbable wound closure solutions integrate antimicrobial coatings and high-tensile monofilament structures to significantly enhance procedural precision and minimize postoperative infection risks across diverse surgical applications.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • ASSUT EUROPE SpA
  • B.Braun SE
  • Centennial Surgical Suture Ltd.
  • Corza Medical
  • Demetech AB
  • Ethicon Inc.
  • Futura Surgicare Pvt. Ltd.
  • Healthium Medtech Pvt. Ltd.
  • Internacional Farmaceutica SA de
  • Lotus Surgicals Pvt. Ltd.
  • LUXSUTURES
  • Medtronic Plc
  • Meril Life Sciences Pvt. Ltd.
  • Peters Surgical
  • Smith and Nephew plc
  • Stryker Corp.
  • Teleflex Inc.
  • Unilene S.A.C.
  • W. L. Gore and Associates Inc.
  • Zimmer Biomet Holdings Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Surgical sutures market

  • In the Health Care Supplies industry, the widespread adoption of stringent hospital infection control protocols has directly accelerated the demand for antimicrobial-coated wound closure devices within the Surgical Sutures market to lower postoperative readmissions.
  • The transition toward localized manufacturing and supply chain nearshoring in the Health Care Supplies sector has stabilized regional medical device inventories, ensuring uninterrupted availability of critical Surgical Sutures during global shipping disruptions.
  • The rapid integration of advanced robotic-assisted platforms across Health Care Supplies has necessitated the development of highly specialized microneedles and automated instruments, significantly altering product design requirements in the Surgical Sutures market.
  • The implementation of circular economy principles and biodegradable packaging mandates within Health Care Supplies procurement has forced manufacturers in the Surgical Sutures market to innovate eco-friendly sterile barrier systems without compromising product integrity.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Surgical Sutures Market insights. See full methodology.

Market Scope
Page number 286
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 4.6%
Market growth 2026-2030 USD 1216.8 million
Market structure Fragmented
YoY growth 2025-2026(%) 4.3%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Indonesia, Thailand, Brazil, Turkey, Saudi Arabia, Argentina, South Africa, UAE, Colombia and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Surgical Sutures sector continues to undergo profound structural transformations driven by the rapid development of synthetic absorbable polymers and antimicrobial coated threads. Modern healthcare administrators actively align their product procurement strategies with strict infection control mandates, forcing a paradigm shift away from traditional natural fibers.
  • The continuous transition toward knotless barbed wound closure and sophisticated tissue approximation mechanisms fundamentally changes how surgical teams approach time-sensitive operations. Hospitals integrating these advanced closure technologies have recorded a 20% reduction in intraoperative suturing time, directly optimizing operating room utilization rates.
  • As minimally invasive techniques become the clinical standard, the necessity for specialized robotic assisted microsurgery needles and high-performance polyglactin 910 formulations intensifies. These materials offer highly predictable enzymatic degradation profiles, ensuring optimal tissue support during the most vulnerable healing stages.
  • By mitigating the risks of surgical site infections, healthcare facilities drastically reduce costly patient readmissions and align with rigorous quality-of-care standards. The relentless pursuit of material biocompatibility and enhanced tensile strength retention ensures that modern closure solutions remain a foundational pillar of advanced surgical infrastructure and patient safety protocols.

What are the Key Data Covered in this Surgical Sutures Market Research and Growth Report?

  • What is the expected growth of the Surgical Sutures Market between 2026 and 2030?

    • USD 1.22 billion, at a CAGR of 4.6%

  • What segmentation does the market report cover?

    • The report is segmented by Product (Absorbable surgical sutures, Non-absorbable surgical sutures, and Suture-assist devices), End-user (Hospitals, ASCs, and Others), Product Type (Coated sutures, and Uncoated sutures) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Rising volume of surgical procedures globally, Stringent regulatory compliance and prolonged approval processes

  • Who are the major players in the Surgical Sutures Market?

    • ASSUT EUROPE SpA, B.Braun SE, Centennial Surgical Suture Ltd., Corza Medical, Demetech AB, Ethicon Inc., Futura Surgicare Pvt. Ltd., Healthium Medtech Pvt. Ltd., Internacional Farmaceutica SA de, Lotus Surgicals Pvt. Ltd., LUXSUTURES, Medtronic Plc, Meril Life Sciences Pvt. Ltd., Peters Surgical, Smith and Nephew plc, Stryker Corp., Teleflex Inc., Unilene S.A.C., W. L. Gore and Associates Inc. and Zimmer Biomet Holdings Inc.

Market Research Insights

  • The Surgical Sutures sector is rapidly evolving as healthcare systems prioritize outpatient clinical efficiency and ambulatory surgery workflow optimization. By standardizing customized procedural trays, surgical centers have realized a 25% decrease in operating room turnover times and a 14% reduction in sterile material waste.
  • Furthermore, the integration of postoperative complication reduction strategies has driven a 30% increase in the utilization of antimicrobial-coated threads. These operational adjustments directly support value based care delivery by minimizing hospital readmissions and curbing excess clinical expenditures.
  • As advanced robotic integration becomes standard practice across specialized medical disciplines, the demand for high-precision, automated tissue approximation instruments continues to rise, firmly establishing these essential medical devices as critical components of modern surgical infrastructure.

We can help! Our analysts can customize this surgical sutures market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Product Type
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Surgical Sutures Market 2020 - 2024

Historic Market Size - Data Table on Global Surgical Sutures Market 2020 - 2024 ($ million)

5.2 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Product Type segment analysis 2020 - 2024

Historic Market Size - Product Type Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global surgical sutures market

6.2 Impact of geopolitical conflicts on global surgical sutures market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product

8.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

8.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

8.3 Absorbable surgical sutures - Market size and forecast 2025-2030

Chart on Absorbable surgical sutures - Market size and forecast 2025-2030 ($ million)
Data Table on Absorbable surgical sutures - Market size and forecast 2025-2030 ($ million)
Chart on Absorbable surgical sutures - Year-over-year growth 2025-2030 (%)
Data Table on Absorbable surgical sutures - Year-over-year growth 2025-2030 (%)

8.4 Non-absorbable surgical sutures - Market size and forecast 2025-2030

Chart on Non-absorbable surgical sutures - Market size and forecast 2025-2030 ($ million)
Data Table on Non-absorbable surgical sutures - Market size and forecast 2025-2030 ($ million)
Chart on Non-absorbable surgical sutures - Year-over-year growth 2025-2030 (%)
Data Table on Non-absorbable surgical sutures - Year-over-year growth 2025-2030 (%)

8.5 Suture-assist devices - Market size and forecast 2025-2030

Chart on Suture-assist devices - Market size and forecast 2025-2030 ($ million)
Data Table on Suture-assist devices - Market size and forecast 2025-2030 ($ million)
Chart on Suture-assist devices - Year-over-year growth 2025-2030 (%)
Data Table on Suture-assist devices - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Hospitals - Market size and forecast 2025-2030

Chart on Hospitals - Market size and forecast 2025-2030 ($ million)
Data Table on Hospitals - Market size and forecast 2025-2030 ($ million)
Chart on Hospitals - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals - Year-over-year growth 2025-2030 (%)

9.4 ASCs - Market size and forecast 2025-2030

Chart on ASCs - Market size and forecast 2025-2030 ($ million)
Data Table on ASCs - Market size and forecast 2025-2030 ($ million)
Chart on ASCs - Year-over-year growth 2025-2030 (%)
Data Table on ASCs - Year-over-year growth 2025-2030 (%)

9.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Product Type

10.1 Market segments

Chart on Product Type - Market share 2025-2030 (%)
Data Table on Product Type - Market share 2025-2030 (%)

10.2 Comparison by Product Type

Chart on Comparison by Product Type
Data Table on Comparison by Product Type

10.3 Coated sutures - Market size and forecast 2025-2030

Chart on Coated sutures - Market size and forecast 2025-2030 ($ million)
Data Table on Coated sutures - Market size and forecast 2025-2030 ($ million)
Chart on Coated sutures - Year-over-year growth 2025-2030 (%)
Data Table on Coated sutures - Year-over-year growth 2025-2030 (%)

10.4 Uncoated sutures - Market size and forecast 2025-2030

Chart on Uncoated sutures - Market size and forecast 2025-2030 ($ million)
Data Table on Uncoated sutures - Market size and forecast 2025-2030 ($ million)
Chart on Uncoated sutures - Year-over-year growth 2025-2030 (%)
Data Table on Uncoated sutures - Year-over-year growth 2025-2030 (%)

10.5 Market opportunity by Product Type

Market opportunity by Product Type ($ million)
Data Table on Market opportunity by Product Type ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5.6 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ million)
Data Table on Thailand - Market size and forecast 2025-2030 ($ million)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.3 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.4 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.5 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.6 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.7 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising volume of surgical procedures globally
Technological advancements in suture materials and robotic integration
Rising geriatric population and prevalence of chronic diseases

13.2 Market challenges

Stringent regulatory compliance and prolonged approval processes
Intense pricing pressure and cost containment strategies by healthcare providers
Rising adoption of alternative wound closure technologies

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Shift toward sustainable manufacturing and eco friendly packaging
Increasing preference for customized and procedure specific suture kits
Expansion of localized manufacturing and supply chain nearshoring

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 B.Braun SE

B.Braun SE - Overview
B.Braun SE - Product / Service
B.Braun SE - Key offerings
SWOT

15.5 Corza Medical

Corza Medical - Overview
Corza Medical - Product / Service
Corza Medical - Key offerings
SWOT

15.6 Demetech AB

Demetech AB - Overview
Demetech AB - Product / Service
Demetech AB - Key offerings
SWOT

15.7 Ethicon Inc.

Ethicon Inc. - Overview
Ethicon Inc. - Product / Service
Ethicon Inc. - Key offerings
SWOT

15.8 Futura Surgicare Pvt. Ltd.

Futura Surgicare Pvt. Ltd. - Overview
Futura Surgicare Pvt. Ltd. - Product / Service
Futura Surgicare Pvt. Ltd. - Key offerings
SWOT

15.9 Healthium Medtech Pvt. Ltd.

Healthium Medtech Pvt. Ltd. - Overview
Healthium Medtech Pvt. Ltd. - Product / Service
Healthium Medtech Pvt. Ltd. - Key offerings
SWOT

15.10 Internacional Farmaceutica SA de

Internacional Farmaceutica SA de - Overview
Internacional Farmaceutica SA de - Product / Service
Internacional Farmaceutica SA de - Key offerings
SWOT

15.11 Medtronic Plc

Medtronic Plc - Overview
Medtronic Plc - Business segments
Medtronic Plc - Key news
Medtronic Plc - Key offerings
Medtronic Plc - Segment focus
SWOT

15.12 Meril Life Sciences Pvt. Ltd.

Meril Life Sciences Pvt. Ltd. - Overview
Meril Life Sciences Pvt. Ltd. - Product / Service
Meril Life Sciences Pvt. Ltd. - Key offerings
SWOT

15.13 Peters Surgical

Peters Surgical - Overview
Peters Surgical - Product / Service
Peters Surgical - Key offerings
SWOT

15.14 Smith and Nephew plc

Smith and Nephew plc - Overview
Smith and Nephew plc - Business segments
Smith and Nephew plc - Key offerings
Smith and Nephew plc - Segment focus
SWOT

15.15 Stryker Corp.

Stryker Corp. - Overview
Stryker Corp. - Business segments
Stryker Corp. - Key offerings
Stryker Corp. - Segment focus
SWOT

15.16 Teleflex Inc.

Teleflex Inc. - Overview
Teleflex Inc. - Business segments
Teleflex Inc. - Key news
Teleflex Inc. - Key offerings
Teleflex Inc. - Segment focus
SWOT

15.17 W. L. Gore and Associates Inc.

W. L. Gore and Associates Inc. - Overview
W. L. Gore and Associates Inc. - Product / Service
W. L. Gore and Associates Inc. - Key offerings
SWOT

15.18 Zimmer Biomet Holdings Inc.

Zimmer Biomet Holdings Inc. - Overview
Zimmer Biomet Holdings Inc. - Business segments
Zimmer Biomet Holdings Inc. - Key news
Zimmer Biomet Holdings Inc. - Key offerings
Zimmer Biomet Holdings Inc. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Surgical Sutures market growth will increase by USD 1216.8 million during 2026-2030.

The Surgical Sutures market is expected to grow at a CAGR of 4.6% during 2026-2030.

Surgical Sutures market is segmented by Product (Absorbable surgical sutures, Non-absorbable surgical sutures, Suture-assist devices) End-user (Hospitals, ASCs, Others) Product type (Coated sutures, Uncoated sutures)

ASSUT EUROPE SpA, B.Braun SE, Centennial Surgical Suture Ltd., Corza Medical, Demetech AB, Ethicon Inc., Futura Surgicare Pvt. Ltd., Healthium Medtech Pvt. Ltd., Internacional Farmaceutica SA de, Lotus Surgicals Pvt. Ltd., LUXSUTURES, Medtronic Plc, Meril Life Sciences Pvt. Ltd., Peters Surgical, Smith and Nephew plc, Stryker Corp., Teleflex Inc., Unilene S.A.C., W. L. Gore and Associates Inc., Zimmer Biomet Holdings Inc. are a few of the key vendors in the Surgical Sutures market.

North America will register the highest growth rate of 32.1% among the other regions. Therefore, the Surgical Sutures market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Indonesia, Thailand, Brazil, Turkey, Saudi Arabia, Argentina, South Africa, UAE, Colombia, Israel

  • Rising volume of surgical procedures globally is the driving factor this market.

The Surgical Sutures market vendors should focus on grabbing business opportunities from the Product segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
