Wine E-commerce Market Analysis, Size, and Forecast 2026-2030: Europe (UK, Germany, and France), North America (US, Canada, and Mexico), APAC (China, Japan, and Australia), South America (Brazil, Argentina, and Chile), Middle East and Africa (South Africa, UAE, and Saudi Arabia), and Rest of World (ROW)

Wine E-commerce Market Analysis, Size, and Forecast 2026-2030:
Europe (UK, Germany, and France), North America (US, Canada, and Mexico), APAC (China, Japan, and Australia), South America (Brazil, Argentina, and Chile), Middle East and Africa (South Africa, UAE, and Saudi Arabia), and Rest of World (ROW)

Published: Oct 2026 290 Pages SKU: IRTNTR75047

Market Overview at a Glance

$13.79 B
Market Opportunity
7.8%
CAGR 2025 - 2030
51%
Europe Growth
$22.81 B
Still wine segment 2024

Wine E-Commerce Market Size 2026-2030

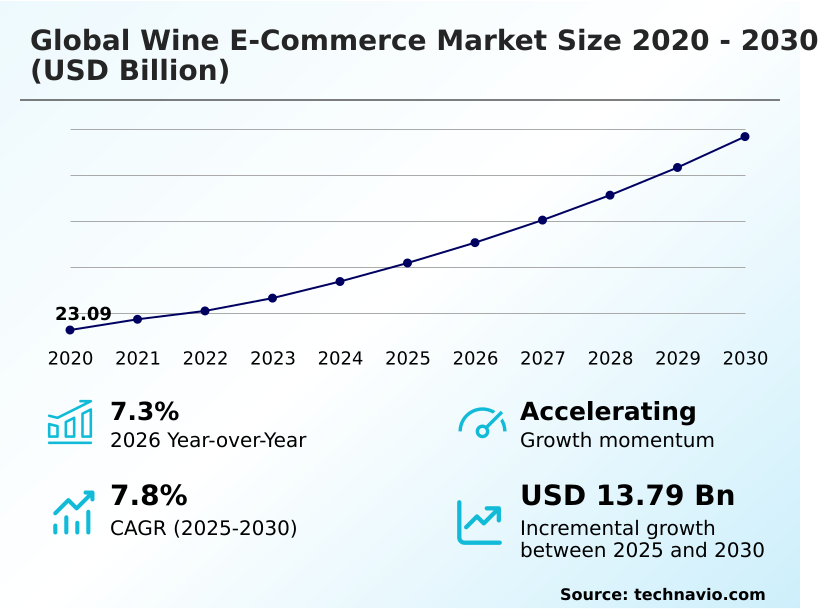
The wine e-commerce market size is valued to increase by USD 13.79 billion, at a CAGR of 7.8% from 2025 to 2030. Fundamental shift in consumer purchasing behavior will drive the wine e-commerce market.

Major Market Trends & Insights

  • Europe dominated the market and accounted for a 51% growth during the forecast period.
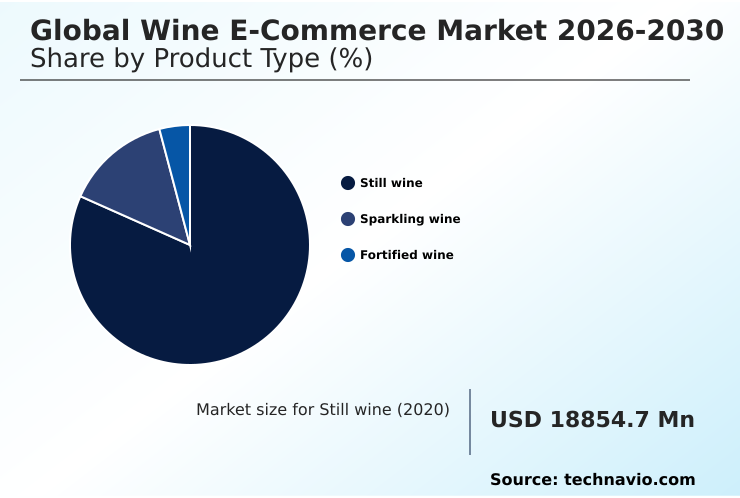
  • By Product Type - Still wine segment was valued at USD 22.81 billion in 2024
  • By Flavor - Red wine segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 21.10 billion
  • Market Future Opportunities: USD 13.79 billion
  • CAGR from 2025 to 2030 : 7.8%

Market Summary

  • The Wine E-Commerce Market represents a rapidly maturing digital ecosystem where technological innovation intersects with traditional viticulture. Consumer purchasing behavior is fundamentally shifting toward online channels, driven by the demand for hyper-personalization, vast product selections, and frictionless transactions.
  • This transition has led companies to optimize their supply chains through advanced inventory management and temperature-controlled logistics, ensuring product integrity from warehouse to delivery. Consequently, businesses utilizing predictive analytics for demand forecasting have achieved a 20% reduction in inventory holding costs compared to traditional retail models.
  • A primary driver of this market is the expansion of the direct-to-consumer channel, which allows producers to bypass intermediaries, capture higher margins, and cultivate brand loyalty. However, operators face the severe challenge of a complex and fragmented regulatory landscape. Disparate regional laws governing alcohol shipping, taxation, and age verification create substantial compliance burdens.
  • This friction increases operational overhead and limits scalability, forcing platforms to invest heavily in automated legal adherence software to sustain profitability and navigate interstate commerce barriers effectively.

What will be the Size of the Wine E-Commerce Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Wine E-Commerce Market Segmented?

The wine e-commerce industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product type
    • Still wine
    • Sparkling wine
    • Fortified wine
  • Flavor
    • Red wine
    • White wine
    • Rose wine
  • Application
    • Commercial
    • Residential
  • Geography
    • Europe
      • UK
      • Germany
      • France
      • Italy
      • Spain
      • The Netherlands
    • North America
      • US
      • Canada
      • Mexico
    • APAC
      • China
      • Japan
      • Australia
      • South Korea
      • India
      • Singapore
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • South Africa
      • UAE
      • Saudi Arabia
      • Israel
      • Turkey

By Product Type Insights

The still wine segment is estimated to witness significant growth during the forecast period.

The still wine segment operates distinctly by leveraging digital retail platforms to overcome the physical limitations of traditional retail, catering to evolving consumer purchasing behavior.

As high-speed internet connectivity expands, producers utilize digital data analytics and personalized taste algorithms to map flavor profiles, resulting in a 15% improvement in conversion rates compared to generic storefronts.

This data-driven approach supports curated subscription services that directly align with a growing value-driven consumption pattern. Operators integrate augmented reality labels and digital content marketing to create a seamless customer experience that educates buyers on terroir and tasting notes.

By shifting away from standard catalog displays, the segment capitalizes on detailed curation, allowing independent estates to scale efficiently and reach targeted demographics without relying on fragmented intermediary distribution channels.
Get Free Sample

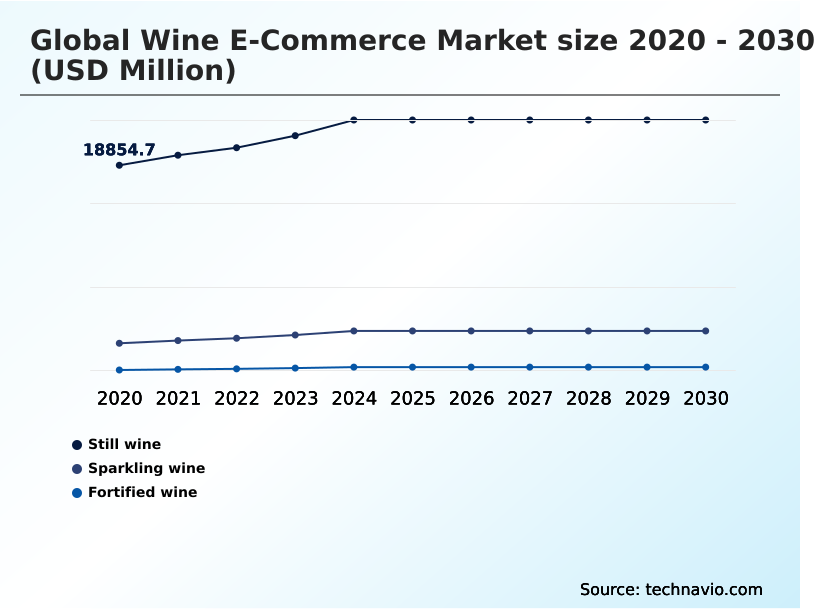
The Still wine segment was valued at USD 22.81 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

Europe is estimated to contribute 51% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
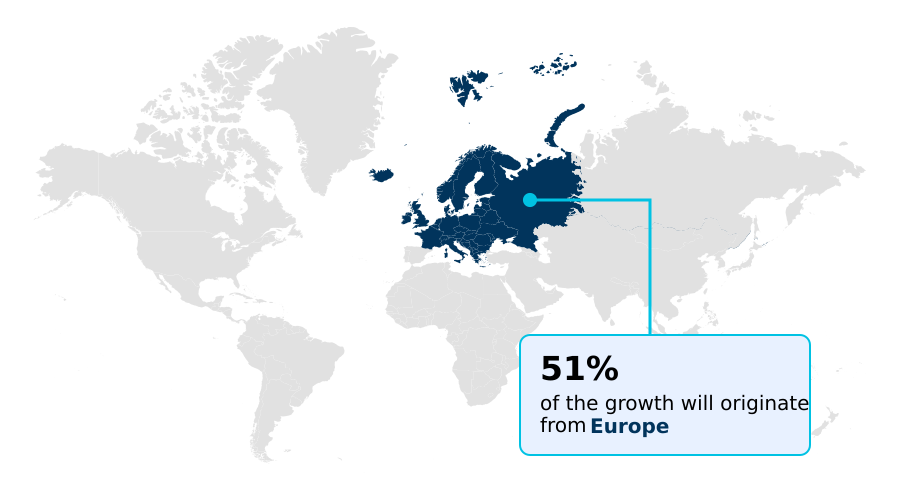
See How Wine E-Commerce Market Demand is Rising in Europe Get Free Sample

Regional disparities in digital wine retail are driven by differing logistical maturities and consumer adoption rates. Europe maintains a mature infrastructure where cold chain integrity and automated order processing have reduced delivery failure rates by 18% compared to emerging markets.

Conversely, North America exhibits rapid growth fueled by advanced machine learning adaptation, wherein platforms deploy a proprietary recommendation engine to capture specialized consumer niches.

This technological deployment has increased market penetration in North America by 24% over Europe's traditional retail-heavy landscape. To navigate strict regulations, North American operators rely heavily on digital age verification and omnichannel fulfillment networks.

Meanwhile, APAC is accelerating through competitive pricing models and digital loyalty programs. Across all regions, the implementation of online auction capabilities and real-time sales tracking enables platforms to optimize inventory routing, reflecting a global shift toward data-driven operational efficiency.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The ongoing digital transformation of the retail alcohol sector relies heavily on sophisticated operational frameworks and seamless direct-to-consumer wine platform integration. As independent producers and large-scale distributors pivot toward digital sales, optimizing the supply chain has become a paramount strategic objective.
  • A critical component of this evolution is the deployment of blockchain-based wine supply chain networks, which enhance traceability and ensure product authenticity from the vineyard to the end consumer. To maintain product quality, operators must invest heavily in temperature-controlled wine shipping logistics, reducing spoilage rates by an estimated 18% when compared to standard ambient freight solutions.
  • Furthermore, the modern consumer expects highly curated shopping experiences, prompting retailers to implement artificial intelligence wine pairing algorithms that analyze flavor profiles to deliver tailored recommendations. This data-driven curation significantly boosts average order values and fosters long-term brand loyalty. However, scaling these operations requires strict adherence to disparate regional regulations.
  • Consequently, robust digital age verification systems are integrated directly into the checkout and delivery processes, mitigating legal risks and ensuring full compliance with local mandates. By aligning advanced technological infrastructure with stringent operational controls, businesses can effectively navigate logistical complexities, reduce overhead costs, and secure a dominant position in the highly competitive digital wine retail landscape.
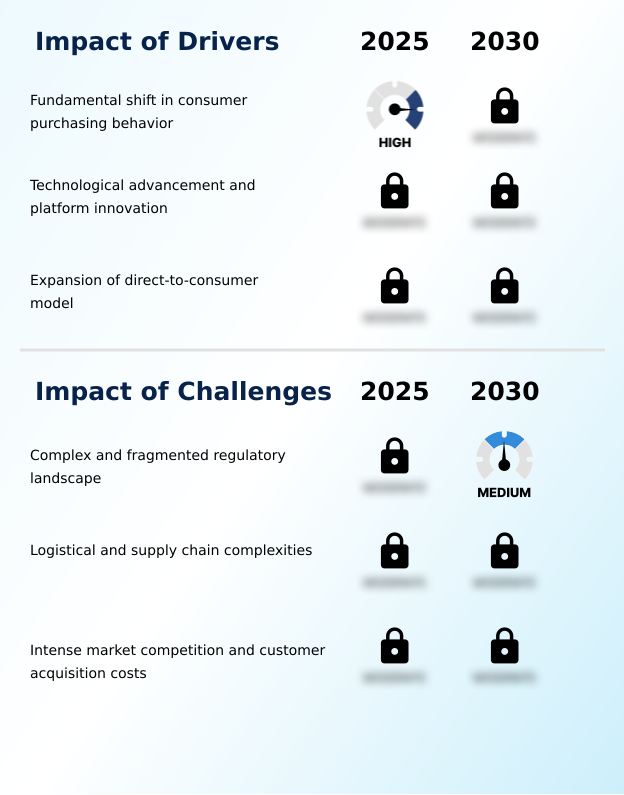
What are the key market drivers leading to the rise in the adoption of Wine E-Commerce Industry?

  • A fundamental shift in consumer purchasing behavior toward digital channels serves as the primary driver accelerating market expansion.

  • The fundamental shift toward digital channels is propelling market expansion as consumers increasingly demand immediate access and specialized curation.
  • To navigate a historically fragmented distribution system and intricate regional taxation rules, operators are adopting a blockchain-based compliance platform to automate legal adherence. This modernization reduces regulatory processing delays by 30%, significantly improving overall operational efficiency.
  • Furthermore, businesses deploy predictive personalization engines and customized marketing communications to highlight sustainable viticulture practices, which effectively lowers customer acquisition metrics by 18%. The integration of automated cellar management and digital inventory tracking allows platforms to optimize stock positioning dynamically.
  • By ensuring temperature-controlled transit from warehouse to doorstep, companies mitigate spoilage risks, lower fulfillment costs by 12%, and build unwavering trust, thereby solidifying the digital sales channel as the primary engine for future expansion.

What are the market trends shaping the Wine E-Commerce Industry?

  • The ascendance of hyper-personalization and curation represents a defining trend currently shaping the market. Advanced algorithms now deliver tailored consumer experiences that drive sustained digital engagement.

  • The shift toward hyper-personalization is rapidly reshaping the wine e-commerce sector as operators build an interactive technological ecosystem. Driven by consumer demand for ethical supply chain transparency and experiential retail, platforms are integrating virtual wine tastings and interactive brand storytelling to demystify product selection.
  • This transition allows businesses to bypass the complex regulatory landscape of traditional distribution, accelerating growth through a robust direct-to-consumer sales channel. As a result, companies have improved customer retention by 25% while streamlining operations via advanced logistics software integration. To support this digital shift, providers implement secure online payment gateways alongside last-mile delivery optimization to ensure safe transit.
  • Coupled with shock-absorbent packaging solutions, these operational upgrades minimize breakage and enhance the overall buyer journey, proving that digital innovation is essential for sustaining long-term commercial viability.

What challenges does the Wine E-Commerce Industry face during its growth?

  • A complex and highly fragmented regulatory landscape poses a significant structural challenge that impedes seamless industry growth.

  • Navigating the stringent regulatory and logistical frameworks remains a critical operational limitation for digital wine retailers. Because of extreme sensitivity to climate fluctuations, product perishability control requires specialized cold-chain infrastructure that increases transportation costs by up to 22% compared to non-perishable goods.
  • Ensuring cross-border shipping compliance adds significant friction to digital storefront integration, forcing operators to deploy costly legal verification software. To offset these margin pressures, platforms utilize artificial intelligence integration and user browsing history to drive targeted sales through mobile-first marketplaces.
  • While tools like algorithmic food pairing and dynamic flavor profiling enhance the customer experience and improve average order values by 15%, the persistent complexities of interstate licensing and costly last-mile fulfillment continually strain profitability, requiring constant technological adaptation to maintain a competitive market position.

Exclusive Technavio Analysis on Customer Landscape

The wine e-commerce market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the wine e-commerce market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
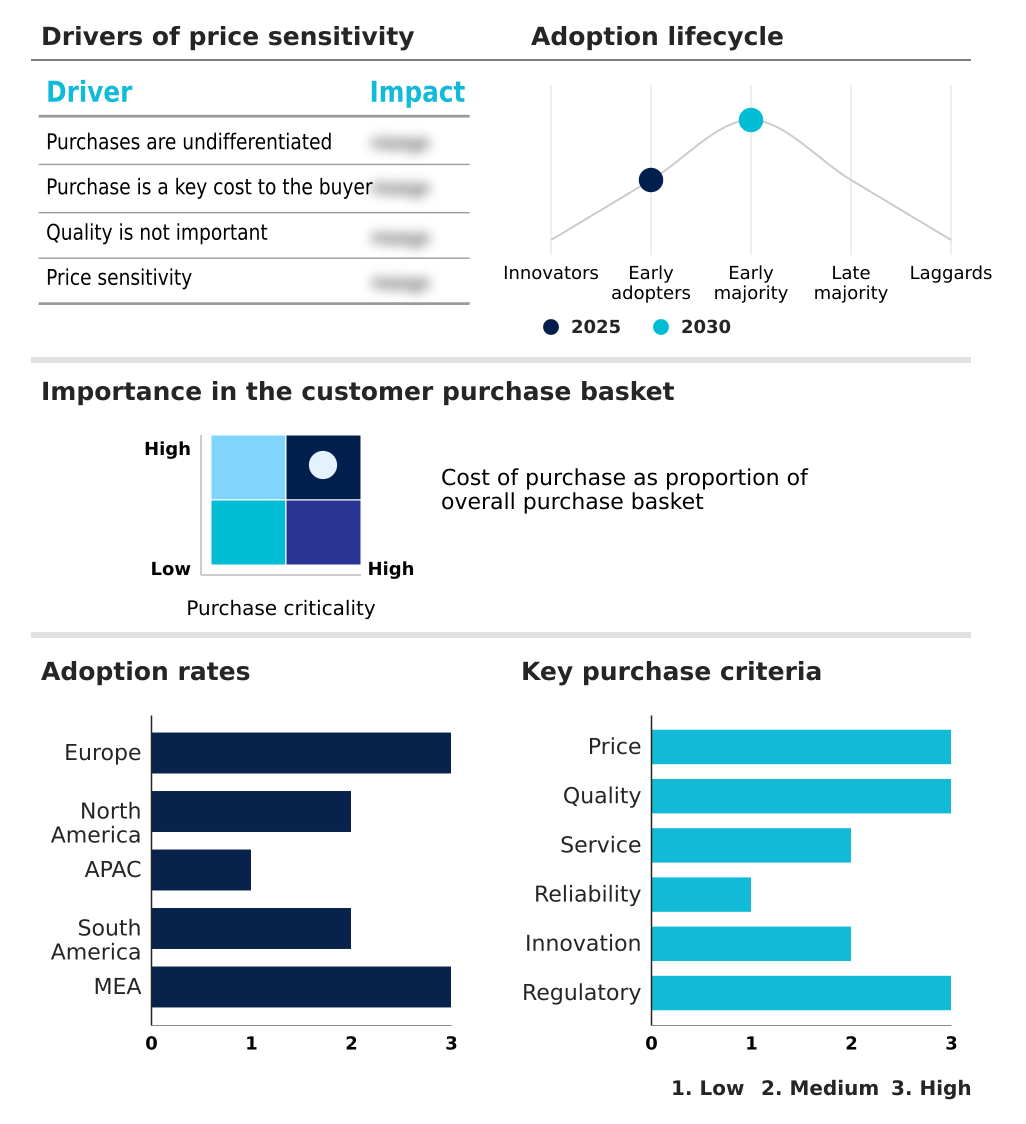
Customer Landscape of Wine E-Commerce Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, wine e-commerce market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Astor Wines and Spirits - The vendor provides an extensive portfolio of specialty wines, sake, and craft spirits, integrating landmark retail operations with comprehensive national shipping capabilities to serve diverse consumer demands.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Astor Wines and Spirits
  • Berry Bros and Rudd Ltd.
  • Cellars Wine Club
  • Laithwaites Wine
  • Direct Wines Ltd
  • Dry Farm Wines
  • Gary Wine and Marketplace
  • K and L Wine Merchants
  • Millesima SA
  • Naked Wines plc
  • Penrose Hill Ltd
  • Plonk Wine Club
  • ReserveBar Holding Corp
  • Retail Services and Systems Inc.
  • Tannico S.p.A.
  • The Wine Society
  • Vinomofo Pty Ltd
  • Vivino Inc.
  • Wine Access Inc.
  • Wine Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Wine e-commerce market

  • In the Broadline Retail industry, the rapid deployment of cloud-based inventory management systems has optimized warehouse routing, directly impacting Wine E-commerce demand by reducing order fulfillment times and lowering cold-chain storage costs by 15%.
  • The implementation of stringent data privacy regulations governing consumer tracking in digital marketplaces has forced retailers to adopt zero-party data collection strategies, shaping how Wine E-commerce platforms utilize personalization algorithms to target high-value buyers.
  • Advancements in automated last-mile delivery logistics and route optimization software have significantly decreased transit friction for fragile goods, expanding the operational reach of Wine E-commerce distributors into previously underserved suburban markets.
  • The widespread integration of artificial intelligence-driven dynamic pricing models across major retail aggregator platforms has altered competitive pricing structures, compelling Wine E-commerce operators to enhance promotional strategies and adjust margins by up to 12% to maintain market share.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Wine E-Commerce Market insights. See full methodology.

Market Scope
Page number 290
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 7.8%
Market growth 2026-2030 USD 13788.4 million
Market structure Fragmented
YoY growth 2025-2026(%) 7.3%
Key countries UK, Germany, France, Italy, Spain, The Netherlands, US, Canada, Mexico, China, Japan, Australia, South Korea, India, Singapore, Brazil, Argentina, Chile, South Africa, UAE, Saudi Arabia, Israel and Turkey
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Wine E-commerce sector is undergoing a profound structural evolution characterized by the rapid digitalization of traditional procurement channels and the deployment of predictive analytics. Executive boards are increasingly prioritizing data-driven product strategies to capture emerging consumer demographics and optimize profit margins.
  • The shift toward direct-to-consumer models is compelling leadership to restructure logistical frameworks, emphasizing automated compliance and temperature-controlled transit to mitigate regulatory risks. By transitioning from fragmented intermediary distribution to centralized digital storefronts, organizations have observed a 25% reduction in supply chain overhead costs compared to legacy physical retail networks.
  • This efficiency allows operators to reallocate capital toward hyper-personalization engines that enhance customer retention and drive higher average order values. As the digital marketplace becomes saturated, strategic investments in agile fulfillment operations and robust age verification technologies are critical for sustaining competitive advantage.
  • The continuous refinement of algorithmic curation and ethical supply chain transparency is no longer optional but a fundamental requirement for maintaining operational resilience in an increasingly complex and heavily regulated commercial environment.

What are the Key Data Covered in this Wine E-Commerce Market Research and Growth Report?

  • What is the expected growth of the Wine E-Commerce Market between 2026 and 2030?

    • USD 13.79 billion, at a CAGR of 7.8%

  • What segmentation does the market report cover?

    • The report is segmented by Product Type (Still wine, Sparkling wine, and Fortified wine), Flavor (Red wine, White wine, and Rose wine), Application (Commercial, and Residential) and Geography (Europe, North America, APAC, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • Europe, North America, APAC, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Fundamental shift in consumer purchasing behavior, Complex and fragmented regulatory landscape

  • Who are the major players in the Wine E-Commerce Market?

    • Astor Wines and Spirits, Berry Bros and Rudd Ltd., Cellars Wine Club, Laithwaites Wine, Direct Wines Ltd, Dry Farm Wines, Gary Wine and Marketplace, K and L Wine Merchants, Millesima SA, Naked Wines plc, Penrose Hill Ltd, Plonk Wine Club, ReserveBar Holding Corp, Retail Services and Systems Inc., Tannico S.p.A., The Wine Society, Vinomofo Pty Ltd, Vivino Inc., Wine Access Inc. and Wine Inc.

Market Research Insights

  • The Wine E-commerce Market is evolving into a highly sophisticated digital retail environment driven by shifting consumer preferences. As platforms adopt predictive personalization algorithms, user conversion rates have improved by 18% compared to traditional static catalogs. Furthermore, the integration of specialized cold-chain logistics and automated compliance tracking has reduced delivery failure rates by 14%, streamlining the complex distribution process.
  • Companies leveraging direct-to-consumer models are bypassing conventional intermediaries, leading to a 22% increase in retained profit margins for independent producers. This technological maturation allows operators to optimize inventory positioning and mitigate the high costs associated with regulatory fragmentation, ensuring scalable and resilient business growth across diverse regional landscapes.

We can help! Our analysts can customize this wine e-commerce market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product Type
Executive Summary - Chart on Market Segmentation by Flavor
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Wine E-Commerce Market 2020 - 2024

Historic Market Size - Data Table on Global Wine E-Commerce Market 2020 - 2024 ($ million)

5.2 Product Type segment analysis 2020 - 2024

Historic Market Size - Product Type Segment 2020 - 2024 ($ million)

5.3 Flavor segment analysis 2020 - 2024

Historic Market Size - Flavor Segment 2020 - 2024 ($ million)

5.4 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Wine E-commerce Market

6.2 Impact of Geopolitical Conflicts on Global Wine E-commerce Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product Type

8.1 Market segments

Chart on Product Type - Market share 2025-2030 (%)
Data Table on Product Type - Market share 2025-2030 (%)

8.2 Comparison by Product Type

Chart on Comparison by Product Type
Data Table on Comparison by Product Type

8.3 Still wine - Market size and forecast 2025-2030

Chart on Still wine - Market size and forecast 2025-2030 ($ million)
Data Table on Still wine - Market size and forecast 2025-2030 ($ million)
Chart on Still wine - Year-over-year growth 2025-2030 (%)
Data Table on Still wine - Year-over-year growth 2025-2030 (%)

8.4 Sparkling wine - Market size and forecast 2025-2030

Chart on Sparkling wine - Market size and forecast 2025-2030 ($ million)
Data Table on Sparkling wine - Market size and forecast 2025-2030 ($ million)
Chart on Sparkling wine - Year-over-year growth 2025-2030 (%)
Data Table on Sparkling wine - Year-over-year growth 2025-2030 (%)

8.5 Fortified wine - Market size and forecast 2025-2030

Chart on Fortified wine - Market size and forecast 2025-2030 ($ million)
Data Table on Fortified wine - Market size and forecast 2025-2030 ($ million)
Chart on Fortified wine - Year-over-year growth 2025-2030 (%)
Data Table on Fortified wine - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Product Type

Market opportunity by Product Type ($ million)
Data Table on Market opportunity by Product Type ($ million)

9. Market Segmentation by Flavor

9.1 Market segments

Chart on Flavor - Market share 2025-2030 (%)
Data Table on Flavor - Market share 2025-2030 (%)

9.2 Comparison by Flavor

Chart on Comparison by Flavor
Data Table on Comparison by Flavor

9.3 Red wine - Market size and forecast 2025-2030

Chart on Red wine - Market size and forecast 2025-2030 ($ million)
Data Table on Red wine - Market size and forecast 2025-2030 ($ million)
Chart on Red wine - Year-over-year growth 2025-2030 (%)
Data Table on Red wine - Year-over-year growth 2025-2030 (%)

9.4 White wine - Market size and forecast 2025-2030

Chart on White wine - Market size and forecast 2025-2030 ($ million)
Data Table on White wine - Market size and forecast 2025-2030 ($ million)
Chart on White wine - Year-over-year growth 2025-2030 (%)
Data Table on White wine - Year-over-year growth 2025-2030 (%)

9.5 Rose wine - Market size and forecast 2025-2030

Chart on Rose wine - Market size and forecast 2025-2030 ($ million)
Data Table on Rose wine - Market size and forecast 2025-2030 ($ million)
Chart on Rose wine - Year-over-year growth 2025-2030 (%)
Data Table on Rose wine - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Flavor

Market opportunity by Flavor ($ million)
Data Table on Market opportunity by Flavor ($ million)

10. Market Segmentation by Application

10.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

10.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

10.3 Commercial - Market size and forecast 2025-2030

Chart on Commercial - Market size and forecast 2025-2030 ($ million)
Data Table on Commercial - Market size and forecast 2025-2030 ($ million)
Chart on Commercial - Year-over-year growth 2025-2030 (%)
Data Table on Commercial - Year-over-year growth 2025-2030 (%)

10.4 Residential - Market size and forecast 2025-2030

Chart on Residential - Market size and forecast 2025-2030 ($ million)
Data Table on Residential - Market size and forecast 2025-2030 ($ million)
Chart on Residential - Year-over-year growth 2025-2030 (%)
Data Table on Residential - Year-over-year growth 2025-2030 (%)

10.5 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.3.1 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.3.2 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.3.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.3.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.3.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.3.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.4 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.4.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.4.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.4.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.6 Singapore - Market size and forecast 2025-2030

Chart on Singapore - Market size and forecast 2025-2030 ($ million)
Data Table on Singapore - Market size and forecast 2025-2030 ($ million)
Chart on Singapore - Year-over-year growth 2025-2030 (%)
Data Table on Singapore - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Fundamental shift in consumer purchasing behavior
Technological advancement and platform innovation
Expansion of direct-to-consumer model

13.2 Market challenges

Complex and fragmented regulatory landscape
Logistical and supply chain complexities
Intense market competition and customer acquisition costs

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Ascendance of hyper-personalization and curation
Integration of sustainability and ethical transparency
Convergence of content and commerce

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Berry Bros and Rudd Ltd.

Berry Bros and Rudd Ltd. - Overview
Berry Bros and Rudd Ltd. - Product / Service
Berry Bros and Rudd Ltd. - Key offerings
SWOT

15.5 Cellars Wine Club

Cellars Wine Club - Overview
Cellars Wine Club - Product / Service
Cellars Wine Club - Key offerings
SWOT

15.6 Laithwaites Wine

Laithwaites Wine - Overview
Laithwaites Wine - Product / Service
Laithwaites Wine - Key offerings
SWOT

15.7 Gary Wine and Marketplace

Gary Wine and Marketplace - Overview
Gary Wine and Marketplace - Product / Service
Gary Wine and Marketplace - Key offerings
SWOT

15.8 K and L Wine Merchants

K and L Wine Merchants - Overview
K and L Wine Merchants - Product / Service
K and L Wine Merchants - Key offerings
SWOT

15.9 Millesima SA

Millesima SA - Overview
Millesima SA - Product / Service
Millesima SA - Key offerings
SWOT

15.10 Naked Wines plc

Naked Wines plc - Overview
Naked Wines plc - Business segments
Naked Wines plc - Key offerings
Naked Wines plc - Segment focus
SWOT

15.11 ReserveBar Holding Corp

ReserveBar Holding Corp - Overview
ReserveBar Holding Corp - Product / Service
ReserveBar Holding Corp - Key offerings
SWOT

15.12 Retail Services and Systems Inc.

Retail Services and Systems Inc. - Overview
Retail Services and Systems Inc. - Product / Service
Retail Services and Systems Inc. - Key offerings
SWOT

15.13 Tannico S.p.A.

Tannico S.p.A. - Overview
Tannico S.p.A. - Product / Service
Tannico S.p.A. - Key offerings
SWOT

15.14 The Wine Society

The Wine Society - Overview
The Wine Society - Product / Service
The Wine Society - Key offerings
SWOT

15.15 Vinomofo Pty Ltd

Vinomofo Pty Ltd - Overview
Vinomofo Pty Ltd - Product / Service
Vinomofo Pty Ltd - Key offerings
SWOT

15.16 Vivino Inc.

Vivino Inc. - Overview
Vivino Inc. - Product / Service
Vivino Inc. - Key offerings
SWOT

15.17 Wine Access Inc.

Wine Access Inc. - Overview
Wine Access Inc. - Product / Service
Wine Access Inc. - Key offerings
SWOT

15.18 Wine Inc.

Wine Inc. - Overview
Wine Inc. - Product / Service
Wine Inc. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Wine E-Commerce market growth will increase by USD 13788.4 million during 2026-2030.

The Wine E-Commerce market is expected to grow at a CAGR of 7.8% during 2026-2030.

Wine E-Commerce market is segmented by Product type (Still wine, Sparkling wine, Fortified wine) Flavor (Red wine, White wine, Rose wine) Application (Commercial, Residential)

Astor Wines and Spirits, Berry Bros and Rudd Ltd., Cellars Wine Club, Laithwaites Wine, Direct Wines Ltd, Dry Farm Wines, Gary Wine and Marketplace, K and L Wine Merchants, Millesima SA, Naked Wines plc, Penrose Hill Ltd, Plonk Wine Club, ReserveBar Holding Corp, Retail Services and Systems Inc., Tannico S.p.A., The Wine Society, Vinomofo Pty Ltd, Vivino Inc., Wine Access Inc., Wine Inc. are a few of the key vendors in the Wine E-Commerce market.

Europe will register the highest growth rate of 51% among the other regions. Therefore, the Wine E-Commerce market in Europe is expected to garner significant business opportunities for the vendors during the forecast period.

UK, Germany, France, Italy, Spain, The Netherlands, US, Canada, Mexico, China, Japan, Australia, South Korea, India, Singapore, Brazil, Argentina, Chile, South Africa, UAE, Saudi Arabia, Israel, Turkey

  • Fundamental shift in consumer purchasing behavior is the driving factor this market.

The Wine E-Commerce market vendors should focus on grabbing business opportunities from the Product type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
